

Introduction
The Intergovernmental Panel on Climate Change’s (IPCC) fifth assessment report unequivocally underscores the intensification of global warming, predominantly caused by human activities. Consequently, addressing the impact of human actions on the environment through greenhouse gas emission reduction has become a paramount concern for humanity. A cost-efficient approach to combat global warming is to establish a carbon market, wherein the pivotal challenge lies in allocating carbon emission quotas. The allocation of carbon quotas typically involves negotiations between the government and diverse enterprises, constituting a consensus problem [1].
So, the allocation of carbon quotas can be seen as the group decision-making [2-4]. Group decision-making is to give full play to the collective wisdom. Numerous participate in the overall process of decision analysis and decision-making. When making decisions on alternatives, because the decision makers often belong to different organizations and have different identities and knowledge backgrounds, the decision makers often have different opinions during the decision-making. At this time, a moderator with rich negotiation and communication experience and personality charm is needed to coordinate all decision makers, so that they can change their views and finally reach an agreement. However, in the coordination process, the moderator always needs to spend some resources to coordinate the decision-makers. In this process, the moderator always wants to spend the least resources and finally reach a consensus [3, 5-9].
Among many research problems of group decision-making, how to minimize the adjustment cost of individual opinions in what we call the consensus reaching process, is a classical problem. Ben-Arieh et al. [10] supposed that the cost of adjusting opinions is linear and studied the issue of minimum cost consensus without budgetary constraints. Ben-Arieh et al. [11] also studied the group consensus costs, and proposed three methods of reaching consensus. In order to study the problem of adjusting opinions between the moderator and the individual, Gong et al. [12] proposed two new types of consensus reaching models, which are involved in minimum cost and maximum return. Ji et al. [13] proposed Risk Maximum Expert Consensus Model (RMECM) based on mean-variance (MV) theory to account for risk factors. The Robust Risk Maximum Expert Consensus Model (R-RMECM) is developed to address uncertainties arising from estimation errors in the mean and covariance matrix of unit adjustment cost. Dong et al. [14] introduced the consensus opinion operator into the decision-making problems first, and the consensus opinion operator adopted the ordered weighted averaging operator and measured the deviation. According to previous studies, Zhang et al. [15] added an aggregation operator into the minimum cost consensus (MCC) model and introduced the idea of soft consensus into the model. Cheng et al. [16] studied the asymmetry in the unit up-adjustment and down-adjustment costs, and three new asymmetry models are proposed: MCCM-DC model, the ε-MCCM-DC model and TB-MCCM-DC model. Based on the above research, Li et al. [17] studied the uncertain scenarios and extended three models, uncertain unit adjustment cost, and initial opinion, which are based on different scenarios discussed. The two-stage stochastic programming is the main method to analyze uncertain parameters.
Existing group-decision-making (GDM) studies always deem that the unit adjustment cost ci, the initial opinion oi in MCC model are known, but the real world is complex and changeable, ci and oi are generally uncertain. So, combining optimization theory with cost consensus problems for group decision-making in uncertain environments is an important branch of research. Stochastic Programming (SP) and Robust Optimization (RO) are two research ideas that exist in existing research approaches to dispose of uncertainties in cost consensus problems [18-21].
In the stochastic programming method, Gong et al. [22] pioneered to combine group decision-making with uncertainty theory to establish a bridge between deterministic group decision and uncertainty theory, and the preferences of decision individuals are fitted using belief degree and uncertainty distribution to construct an opportunity constrained minimum cost consensus model. Ji et al. [23] studied the strategy weight manipulation problem with uncertainty, which applies the uncertainty theory based on confidence degree, and assumed that the uncertain attributes’ values obey uncertainty distribution of linearity, and then constructed a series of hybrid 0-1 planning models, set the strategy weight vector for the required ranking of specific alternatives. The numerical case results of COVID-19 vaccine can reflect the effectiveness of the model well. Liu et al. [24] considered the real-life management problem of “nail households” in urban demolition and eviction, which is a frequent scenario in urban evolution and renewal, and the problem of “nail households” often plagues governments, property developers, and homeowners. As a classic case study, the minimum cost consensus model, multivariate planning, stochastic chance constrained planning and interval number are applied jointly to build a multi-objective minimum cost consensus model based on interval number constraints. But the method relies heavily on the decision maker’s portrayal of the information of the true probability distribution.
In the robust optimization method, Han et al. [25] considered the uncertainty in the input data and established the minimum cost consensus model based on the RO method with four different uncertainty sets. Wei et al. [26] proposed three robust consensus models which used three different aggregation operators, and set novel Box ambiguous set, Ellipsoid ambiguous set, and Polyhedron ambiguous set to study. Jin et al. [27] used the RO method to study the MADM problem and established mixed 0–1 robust optimization model. But in RO models, these worst-case scenarios do not necessarily occur, so consensus cost problems studied by robust optimization-based approaches [1] inevitably lead to over-conservative results.
Although SP and RO are relatively mature methods to study uncertainty problems, the disadvantages of these two methods are also obvious: the results of SP are vulnerable to the accuracy of unknown parameter estimation and the results of RO are too conservative. Therefore, a more reasonable method is needed to deal with uncertainty to ensure that the results are more in line with social reality. In recent years, the Distributionally Robust Optimization (DRO) approach, which has the advantages of SP and RO, is proposed and has been well studied [18, 28-31]. DRO can effectively deal with the uncertainty caused by complex environment, DRO can effectively solve some problems of RO and SP, combining statistical learning and optimization theory to obtain a sufficiently good solution by assuming that the parameters follow certain possible distributions. DRO has found an ambiguity set that contains the true probability distribution of the problem’s random variables. We can fully utilize historical data to construct this ambiguity set and solve the problem. In this study, we adopt the DRO method to avoid the model being too conservative, while also making good use of historical data, ensuring that the model can have good applicability in uncertain environments. But MCCM problems in an uncertain environment will be accompanied by risks, which cannot be completely ignored. The Conditional Value at Risk (CVaR) is a conditional risk measure used to assess financial investment risk. Currently, in the field of group decision-making, more and more researchers are also using CVaR when considering risks and its advantages include:
Tail Risk Consideration: CVaR focuses on the average loss of a portfolio when losses exceed a certain threshold, providing a more comprehensive view of tail risk and better reflecting the extreme events.
Convexity: CVaR is a convex function, making it easier to handle in risk optimization models. Convex optimization problems are generally easier to solve, and CVaR has an advantage in this regard.
Interpretability: The definition of CVaR is relatively simple – it is the average loss when losses exceed a certain threshold. This simplicity makes CVaR easy to interpret and understand for investors and decision-makers.
Due to the above advantages, using the CVaR risk criterion can offset the adverse effects of random variability in the models.
Based on the above findings, this paper uses DRO and CVaR approximation in the TB-MCCM problem, so as to deal with the uncertainty and risk respectively.
The main contributions of this paper are summarized as follows.
(1) Three new distributionally robust two-stage minimum asymmetric adjustment cost consensus models based on CVaR are proposed.
(2) Considering that it is very difficult to obtain historical decision-making data with risk in the carbon market, novel box ambiguous set and polyhedron ambiguous set are constructed, respectively.
(3) The risk expectation cost of the allocation of carbon emission quotas problem under the worst-case condition is measured and three computable linear equivalent forms of the proposed models are derived in order to facilitate calculation.
The rest of this paper is organized as follows.
Section 2 introduces the background and prior knowledge of the minimum cost consensus model, the distributionally robust optimization theory, a coherent risk measure and presents three new distributionally robust two-stage minimum asymmetric adjustment cost consensus models and two ambiguous sets. Section 3 includes numerical examples based on carbon emission quotas and some discussions. Section 5 concludes and presents future work.
Material and Methods
Material
The material used in this paper is some prior knowledge of the minimum cost consensus model, the distributionally robust optimization theory and a coherent risk measure.
In the minimum cost consensus problem, there are n decision makers participating in the discussion. Let oi represent the initial opinion, õ represent the consensus opinion and ci represent the cost adjusting the initial opinion to the consensus opinion. Finally, the model can be described as follows [12]:
Cheng et al. [16] analyzed the model and found that ci is symmetrical. According to the actual situation, three new minimum cost consensus models with costs which are different in different adjustment directions are proposed. Based on Cheng’s models, the following two-stage stochastic minimum cost consensus models are given by Li et al. [17].
Based on Cheng’s MCCM-DC model, the two-stage stochastic programming method is used and the two-stage stochastic MCCM-DC can be given:
where ϖ is random event,
where
Based on Cheng’s ε-MCCM-DC model, the two-stage stochastic programming method is used and the two-stage stochastic ε-MCCM-DC can be given:
where ϖ is random event,
where
Based on Cheng’s TB-MCCM-DC model, the two-stage stochastic programming method is used and the two-stage stochastic TB-MCCM-DC can be given:
where ϖ is random event,
where
Distributionally Robust Optimization Method
The distributed robust optimization model combines the advantages of SP and RO, and the expression is as follows:
where x is the decision variable, X is the decision space of x,
A Coherent Risk Measure
Suppose
Definition 2.1. [32] Assume that β∈(0,1) is a given confidence level and the function Ψ(x, ξ) is continuous everywhere about ζ. The measure of risk called VaR can be expressed as:
where ζ is the threshold value and p(∙) is the probability density function of the random variable.
Artzner et al. [33] proposed the concept of consistent risk measures, i.e., risk measures should satisfy positivity, chi-squaredness, and subadditivity. Since VaR does not satisfy subadditivity, it is not a consistent risk measure. Rockafellar et al. propose a consistent risk measure, CVaR, which is defined as follows.
Definition 2.2. [34] Suppose β∈(0,1) is a given confidence level and the function Ψ(x, ξ) is continuous everywhere about ζ. The mean of the β truncated tail distribution of the loss function μ(x, ξ) and it can be defined as:
where p(·) is the probability density function of the random variable.
Obviously, CVaR indicates that the risk loss is not less than the expected value of VaR. Since the defining equation of CVaR is not easy to calculate under continuous random variables, Rockafellar et al. [34] give an approximate calculation method that CVaR can be equivalently transformed into
where
The calculation of Fβ(x, ζ) involves multivariate, non-smooth functions with difficult integration problems. The CVaR approximation under discrete random variables is given by Rockafellar et al. as follows:
where n indicates the number of scenarios and pi indicates the probability of occurrence of the i scenario.
Lemma 2.1. [35] Assume that β∈(0,1) and pi denote the probability of occurrence of scenario i. The CVaR minimization problem on x∈X is equivalent to the minimization of Fβ(x, ζ) on (x, ζ)∈X×R, i.e.
Since [∙]+ is a convex function, Fβ(x, ζ) is also convex with respect to (x, ζ)∈X×R.
Methods
Model Construction Considering Risk Aversion with Different Opinion Adjustment Directions
Let oi(ϖ) denote the uncertain initial opinion of DMi. There are two uncertain unit adjustment costs on opinion modification in different directions ciD(ϖ) and ciU(ϖ). Assuming
where
where
Model Construction Considering Risk Aversion with Compromise Limits
Similarly, the following worst-case CVaR distribution-based robust model is proposed for the cost consensus modeling problem in conjunction with the finite compromise constraint εi. Let oi(ϖ) denote the uncertain initial opinion of DMi. There are two uncertain unit adjustment costs on opinion modification in different directions ciD(ϖ) and ciU(ϖ). Assuming
where
where
Model Construction Considering Risk-Averse Cost-Free Thresholds
Assuming uncertainty
where
where
Construction of Ambiguous Sets
Two kinds of ambiguous sets, box ambiguous set P1 and polyhedral ambiguous set P2 are constructed [36]:
where p0 is the nominal distribution of discrete probabilities, i.e., the distribution with the highest probability; e is the unit vector;
To specify the simplest ambiguous set, it is sensible to consider box-type set and polyhedral ambiguous set, and the resulting problem can be formulated in a computationally tractable way.
Linear Equivalent Reconstruction of the Model
Model Reconstruction Considering Risk Aversion with Different Opinion Adjustment Directions
Through simplification, CVaR is transformed into a computable equation, it is given by:
where the probability P has finite support Ω, and
According to Definition 2.2,
where α represents the degree of risk. When α = 0,
The auxiliary vector
Based on the Eq. (25), The objective function of the model (13) can be transformed into
The order of the operators
(28)
Therefore, the proposed RDRO-DC model (13) can be equivalently expressed as
where
Theorem 2.1. Under the box ambiguous set P1, the model (29) can be rewritten as follows:
(30)
where
Proof: The Eq. (24) can be deduced that
Therefore, the equivalent form of
Under the box ambiguous set, the model (31) and (32) are linear programming problems and the model (31) is given by the following equation
among them,
In turn,
among them,
According to the strong duality theory, we can get:
Therefore, the pairwise form of the (31) is expressed as follows:
In this way, the model (32) of the pairwise planning can be derived in the following form
In summary, the model (29) is given by
(38)
With the above proof, it is possible to obtain the model (29) computable reconstruction under the box ambiguous set.
Theorem 2.2. Under the polyhedral ambiguous set
(39)
where
Proof: Under the polyhedral ambiguous set, it can be deduced that
(40)
where
The Lagrangian function of model (41) is described as follows:
The Lagrangian pairwise function of model (41) is described as follows:
(43)
where
Therefore, the dual of the (41) is the following problem:
On this basis, the model (31) of the equivalence planning can be expressed as follows:
Similarly, the model (32) of the equivalent form can be rewritten as
In summary, the model (29) is given by
(48)
With the above proof, it is possible to obtain the model (29) computably reconfigurable under the polyhedral ambiguous set.
Considering Risk Aversion with Compromise Limits for Model Refactoring
Based on the Eq. (25), the objective function of the model (16) can be transformed into
The order of the operators
(50)
Therefore, the proposed ε-RDRO-DC model (16) can be equivalently expressed as
where
Theorem 2.3. Under the box ambiguous set P1, the model (51) can be rewritten as follows:
(52)
where
Proof: The formula (24) can be deduced that
Therefore, the equivalent form of
Under the box ambiguous set, the model (53) and (54) are linear programming problems and the model (53) is given by the following equation:
among them,
In turn,
among them,
According to the strong duality theory, we can get:
Therefore, the pairwise form of the (53) is expressed as follows:
In this way, the model (54) of the pairwise planning can be derived in the following form:
In summary, the model (51) is given by
(60)
With the above proof, it is possible to obtain the model (51) computable reconstruction under the box ambiguous set.
Theorem 2.4. Under the polyhedral ambiguous set P2, the model can be rewritten as follows:
(61)
where
Proof: Under the polyhedral ambiguous set, it can be deduced that
(62)
where
The Lagrangian function of model (63) is described as follows:
The Lagrangian pairwise function of model (63) is described as follows:
(65)
where
Therefore, the dual of the (63) is the following problem:
On this basis, the model (63) of the equivalence planning can be expressed as follows:
Similarly, the model (64) of the equivalent form can be rewritten as
In summary, the model (51) is equivalent to the following linear programming form
(70)
With the above proof, it is possible to obtain the model (51) computably reconfigurable under the polyhedral ambiguous set.
Model Reconstruction Considering Risk Aversion No-Cost Threshold
Based on the Eq. (25), The objective function of the model (19) can be transformed into
The order of the operators
(72)
Therefore, the proposed TB-RDRO-DC model (19) can be equivalently expressed as
where
Theorem 2.5. Under the box ambiguous set P1, the model (73) can be rewritten as follows:
(74)
where
Proof: The Eq. (24) can be deduced that
Therefore, the equivalent form of
Under the box ambiguous set, the model (75) and (76) are linear programming problems. In this case, the model (75) is given by the following equation:
among them,
In turn,
among them,
According to the strong duality theory, we can get:
Therefore, the pairwise form of the (75) is expressed as follows:
In this way, the model (76) of the pairwise planning can be derived in the following form:
In summary, the model (73) is equivalent to the following linear programming form
(82)
With the above proof, it is possible to obtain the model (73) computable reconstruction under the box ambiguous set.
Theorem 2.6. Under the polyhedral ambiguous set P2, the model (73) can be rewritten as follows:
(83)
where
Proof: Under the polyhedral ambiguous set, it can be deduced that
(84)
where
The Lagrangian function of model (85) is as follows:
The Lagrangian pairwise function of model (85) is as follows:
(87)
where
Therefore, the dual of the (85) is the following problem:
On this basis, the model (75) of the equivalence planning can be expressed as follows:
Similarly, the model (76) of the equivalent form can be rewritten as
In summary, the model (73) is given by
(92)
With the above proof, it is possible to obtain the model (73) computably reconfigurable under the polyhedral ambiguous set.
Results and Discussion
Due to the large amount of carbon dioxide generated by burning fossil fuels such as oil and coal, these greenhouse gasses can strongly absorb infrared radiation from the ground, leading to an increase in Earth’s temperature. Global warming not only endangers the balance of natural ecosystems, but also affects human health and even threatens human survival.
Carbon emissions trading is a market mechanism adopted to promote global greenhouse gas emissions reduction and reduce global carbon dioxide emissions. The United Nations Intergovernmental Panel on Climate Change passed the United Nations Framework Convention on Climate Change on May 9, 1992 through difficult negotiations. The first additional agreement to the Convention was passed in Kyoto, Japan in December 1997. The Protocol regards market mechanisms as a new path to solve the problem of greenhouse gas emissions reduction represented by carbon dioxide, which regards carbon dioxide emission rights as a commodity, thus forming the trading of carbon dioxide emission rights, abbreviated as carbon trading. A complete carbon market has been established in China, and the key to it is how to allocate carbon emission quotas. Carbon quotas refer to the legal amount obtained by each enterprise through bargaining with the government over a certain period of time.
In this context, the negotiation of carbon quotas between enterprises and the government has actually formed a consensus process, and the numerical simulation cases in this article are all based on the above issues. Assuming that the government is negotiating carbon quotas with 20 companies, and the adjustment costs for each company in different directions are uncertain, we assume that each company has its own initial opinions (ideas) on carbon quotas. All numerical calculations were done with a laptop computer (Intel i7-7300HQ CPU, 32G RAM), using CPLEX 12.10 to run the solution under JDK11.
Calculation Results
The following example explains the proposed distributionally robust cost consensus model considering risk factors. Suppose
Example 1. (Based on RDRO-DC)
The proposed model’s initial information data is given by Table 1.
The RDRO-DC model is solved using the CPLEX solver. According to the experimental results in Table 2, the RDRO-DC model’s consensus opinion is 6.13 and the minimum consensus cost is 381.12.
Example 2. (Based on ε-RDRO-DC)
The proposed model’s initial information data is given by Table 3.
The ε-RDRO-DC model is solved using the CPLEX solver. According to the experimental results in Table 4., the ε-RDRO-DC model’s consensus opinion is 5.87 and the minimum consensus cost is 375.6.
Example 3. (Based on TB-RDRO-DC)
The proposed model’s initial information data is given by Table 5.
The TB-RDRO-DC model is solved using the CPLEX solver. According to the experimental results in Table 6., the TB-RDRO-DC model’s consensus opinion is 6.06 and the minimum consensus cost is 378.5.
Table 1.
RDRO-DC initial information data.
| i | oi | ciD | ciU |
|---|---|---|---|
| 1 | 4.2 | 15 | 23 |
| 2 | 6.7 | 10 | 26 |
| 3 | 6.2 | 11 | 22 |
| 4 | 5.3 | 12 | 24 |
| 5 | 6.1 | 13 | 25 |
| 6 | 5.5 | 11 | 31 |
| 7 | 3.8 | 16 | 21 |
| 8 | 4.9 | 12 | 23 |
| 9 | 4.6 | 15 | 24 |
| 10 | 5.0 | 16 | 25 |
| 11 | 5.7 | 12 | 31 |
| 12 | 6.3 | 11 | 26 |
| 13 | 4.9 | 14 | 32 |
| 14 | 5.3 | 13 | 23 |
| 15 | 2.8 | 21 | 39 |
| 16 | 3.2 | 18 | 30 |
| 17 | 4.5 | 14 | 24 |
| 18 | 6.8 | 11 | 25 |
| 19 | 7.1 | 9 | 18 |
| 20 | 3.6 | 19 | 30 |
Table 2.
RDRO-DC Consensus Cost Results.
Comparison and Analysis of Results
Different combinations of Ψ and λ are used in the numerical case. As can be seen in Table 2., Table 4., and Table 6., the optimal target value of the model increases as the parameter Ψ increases; because when the parameter Ψ is reduced, the accurate probabilistic information will be obtained and the model will be more accurate and more convenient to solve. It can also be observed that when the coefficient λ decreases, the optimal target value of the model decreases, as CVaR becomes a smaller proportion of the objective function, and there is no need to consider more risks to increase costs.
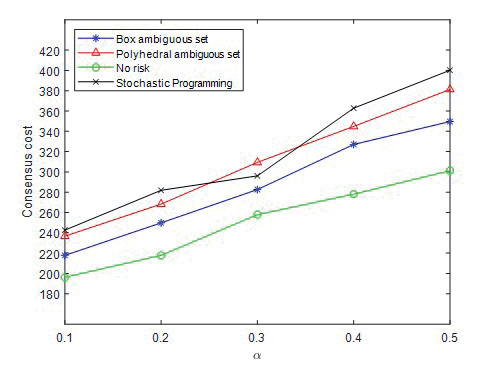
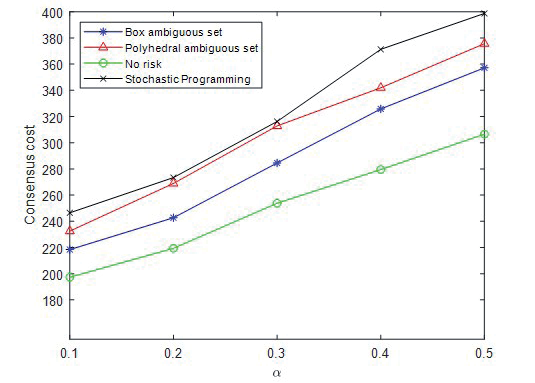
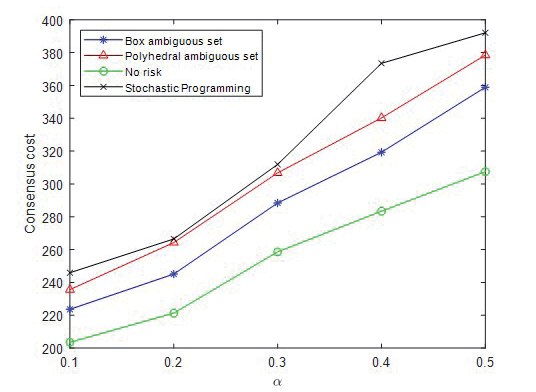
As can be seen from Table 7., the optimal target values of the models increase when the level of risk increases. This is because when the value of α tends to 1, CVaR will express highly risk-averse, and this high level of risk will lead to the overly conservative solution, which means the optimal target value increases. By observing the three uncertainty models proposed in this paper, it is observed that the optimal target value under the box ambiguous set is always smaller than the optimal target value under the polyhedral ambiguous set. This is because the probability distribution of the polyhedral ambiguous set is more perturbed than that of the box ambiguous set. In other words, the box ambiguous set is simpler than the polyhedral ambiguous set, so its probability distribution information is more comprehensive than that of the polyhedral ambiguous set.
Table 3.
ε-RDRO-DC initial information data.
Table 4.
ε-RDRO-DC Consensus Cost Results.
When Ψ = 0, the distributionally robust models will degenerate to a traditional stochastic programming model. The difference between the distributionally robust models and the traditional stochastic programming model will be discussed in the following paragraph. As can be seen from Table 8., under the same risk level, the optimal target values of the uncertainty models are greater than that of the certainty model, this shows that the uncertainty models are more conservative, this conservatism is caused by the robustness of the model. In the traditional stochastic programming model, the uncertainty of the data was not considered, although the uncertainty model increases the cost, the model can avoid the failure caused by the data uncertainty to a certain extent. Therefore, the distributionally robust models are important to the consensus reaching in MCCM.
Compared with the study of Ji et al. [37], According to the results shown in Table 9., it can be found that the distributionally robust models have a significant advantage over the stochastic programming model. Whether based on the box ambiguous set or higher cost polyhedral ambiguous sets, the total consensus cost to be paid is better than the stochastic programming model in most cases. Therefore, when faced with a consensus decision problem that considers the decision maker’s risk preferences, the model is able to obtain consensus opinions at a lower consensus cost.
Figs 1-3. show the comparison of consensus costs of the three models in this paper, the model in Ji et al. [37] and the no-risk model under different α. It can be seen that the addition of risk function will obviously increase the consensus cost, which means that the model is risk sensitive. The total consensus cost of distributionally robust model with risk aversion is higher than that without risk aversion. In other words, it is more difficult to reach consensus when the risk is considered. Meanwhile, the two-stage stochastic minimum cost consensus model with risk aversion is more conservative than that without risk aversion, so the results are worse. However, a comparison with the results under existing stochastic programming-based methods with risk factors shows that the consensus cost of the model proposed in this paper would be better than the existing studies.
Table 5.
TB-RDRO-DC initial information data.
Table 6.
TB-RDRO-DC Consensus Cost Results.
Table 7.
Optimal results of the model with different α.
Table 8.
Comparison of the results of different models.
Table 9.
Comparison of the results of the Distributionally Robust and Stochastic Programming models.
Conclusions and Future Research
Against the backdrop of global warming and increasingly mature carbon emissions trading, the problem of distributional robust consensus decision-making with decision maker risk preferences is considered. The three distributionally robust two-stage minimum asymmetric cost consensus models with risk aversion based on carbon emission quotas are investigated, using a novel box ambiguous set and polyhedral ambiguous set. Through the transformation, the relevant formulas that are convenient for calculation are obtained. Finally, a number of meaningful conclusions can be obtained through numerical examples.
(1) Different values of Ψ, λ and α will lead to the changes in models’ optimal target values The parameter Ψ indicates the accurate probabilistic information, the optimal target value increases as the parameter Ψ increases. The parameter λ represents the proportion of the objective function, the λ decreases, the coefficient λ decreases, the optimal target value decreases. The parameter α shows the level of risk, the optimal target value increases when the value of α tends to 1, which means the model is highly risk-averse.
(2) The optimal target value under the box ambiguous set is always smaller than the optimal target value under the polyhedral ambiguous set. The main reason is: probability distribution information of the box ambiguous set is more comprehensive than that of the polyhedral ambiguous set.
(3) By comparing the distribution robust model with the stochastic programming model, the distribution robust model can use the distribution information in a more robust way than the stochastic programming model. Whether based on the box ambiguous set or polyhedral ambiguous set, the total consensus cost of the distribution robust model to be paid is better than the stochastic programming method in most cases.
(4) The consensus model is sensitive to the risk factor. The total consensus cost of distributionally robust model with risk aversion is higher than that without risk aversion, and it is more difficult to reach consensus when the risk is considered.
In short, it will make the model better avoid uncertainty and risk that introducing distributionally robust method and CVaR into consensus problem. The consensus cost of the models in this paper outperforms the corresponding results under stochastic programming methods and brings new solutions to decision problems in the allocation of carbon emission quotas.
One limitation inherent in this study pertains to its exclusive focus on small-scale group consensus models, involving fewer than 20 decision-makers. In reality, however, large-scale group decision-making scenarios involve the participation of more than 20 individuals, and these have not been comprehensively explored. As a prospective avenue for further research, we intend to delve into the realm of large-scale group decision-making problems in subsequent studies. This will involve leveraging social network methodologies and other innovative approaches to extend the applicability of the findings from this study to larger decision-making groups.
Additionally, another limitation stems from the exclusive consideration of box and polyhedral ambiguity sets. In future research endeavors, we aim to broaden our exploration by incorporating multiple types of ambiguity sets, such as ellipsoid or a combination of box and polyhedral ambiguity sets. This approach will enable us to investigate and understand better the impact of different ambiguity set structures on managing uncertainty.

