

Introduction
What we are facing is a paradox. On one hand, we know the adverse effects of greenhouse gas emissions on ecosystem activities [1]. On the other hand, energy is an important engine for economic development, which affects our basic well-being [2]. It is predicted that global energy demand will grow by more than a quarter by 2040, and correspondingly, CO2 emissions will increase from 205.18 million tons in 1990 to 32.314 billion tons in 2016 due to the increase in fossil fuel consumption [3]. Electricity is an important part of modern energy and plays an important role in economic growth [4-7]. Of course, the acquisition of electricity mostly depends on the transformation of traditional energy (such as fossil fuels). As additional energy, electricity consumption faces the contradiction between economic development and environmental pollution. Fortunately, this is not an irreconcilable contradiction. Recent studies have demonstrated that the application of renewable energy has led to a decrease in CO2 emissions [8-9]. Hydropower and nuclear-related technologies have similar effects as well [10]. Unfortunately, not all countries have enough economic or technological strength to utilize new energy. Therefore, we turn our research perspective to the two groups of countries: the high and low-income countries in the world (economic strength is measured by gross domestic product (GDP)).
Electricity production in the highest-income countries accounts for almost 70% of the world [11]. Developed countries represented by the United States, Canada, and Japan rely on coal energy less than 35% while developing countries represented by China and India rely on coal energy more than 60%. But in South Africa, in contrast, its electricity dependence on coal was as high as 87.73%. He et al. also showed that CO2 emissions in the sub-Saharan region based on fossil fuels were serious [12]. As the lowest-income region in the world, the sub-Saharan region, issues about poverty and economic development have been widely concerned. To achieve economic progress, sub-Saharan Africa has paid a heavy environmental cost. Although they accounted for only 4.8% of the world’s total energy consumption in 2014, they are not one of the regions with the highest emissions. Its economic development is closely related to energy demand, with an annual growth rate of 3.8% from 2000 to 2017 [13]. In 2014, CO2 emissions in sub-Saharan Africa increased significantly, i.e., 822819.03 (kilotons of CO2), 4.94% higher than the previous year [14]. Additionally, most countries in sub-Saharan Africa are facing increasing inequality and a fragile ecological environment [15]. Half of them may not achieve the millennium development goals and poverty reduction targets [16]. For world development and equality, we investigated the relationships between electricity consumption, GDP, and CO2 emissions of the countries with low and high incomes in the world for 35 years.
The rest of this paper is arranged as follows: The second part shows the literature review; the third part shows the data and theoretical methods; the fourth part shows the empirical results of PVAR; and the fifth part is the conclusion of this paper.
Literature Review
The link between energy consumption, economic growth, and carbon emissions has undoubtedly ranked first among the studies common in the empirical energy economics literature [17-20]. This study wants to demonstrate the interaction between electricity consumption, GDP, and CO2 emissions in low and high-income countries. The pairwise correlation variables between the primary studies will be discussed in this section.
Energy Consumption and CO2 Emissions
Numerous previous studies have focused on the long-term relationship between economic growth and energy consumption. Energy consumption relying on burning fossil fuels will lead to greenhouse gas emissions, which lead to climate change and environmental degradation [21]. An increase in energy use and population growth causes an increase in CO2 emissions [22]. For economic development, energy will be consumed rapidly, and it also leads to a large number of greenhouse gas emissions, especially in China [23-24] showing that energy consumption has a positive impact on long-term CO2 emissions. In Nigeria, carbon consumption has a significant negative impact on CO2 emissions [8]. Energy usage intensity can increase CO2 emissions [25]. Asumadu-Sarkodie & Owusu investigated the relationship between carbon dioxide, electricity production, and consumption in Ghana by using time series data from 1971 to 2012 [26]. Evidence from long-term resilience suggests that in the long run, a 1% increase in total energy production from combustible renewable energy and waste will lead to an increase of 307.9 kt in CO2 emissions. In contrast, in the long run, a 1% increase in total energy production from hydropower will reduce 267.3 kt of CO2 emissions.
The main approach to reducing CO2 emissions is to develop renewable energy. Ghana’s nonrenewable energy generation and consumption have increased CO2 emissions, and renewable energy can help mitigate climate change and its impacts [26]. Due to renewable energy and foreign trade in the world, traditional energy has decreased demand in recent decades, and CO2 emissions have obviously increased [27]. Zhang & Zhao believe that investment in R&D and renewable energy plays an important role in reducing CO2 emissions [28]. The development of hydropower, nuclear power, and other renewable energy has a negative impact on CO2 emissions [29-30]. Per capita GDP and oil consumption are positively correlated with CO2 emissions, while natural gas consumption has a negative impact on CO2 [31]. Generally speaking, renewable energy consumption increases energy self-sufficiency, stimulates sustainable economic growth, and reduces CO2 emissions [29-34]). Given the importance of renewable energy in reducing CO2 emissions, policymakers need to deploy more renewable energy for final consumption to achieve long-term climate goals [35].
Energy Consumption and GDP
Most studies focus on the two-way causality between energy consumption and economic growth. Syzdykova et al. summarized the relationship between energy consumption and economic growth in the Commonwealth of Independent States (CIS) for the period of 1992-2018 [36]. According to the findings of the study, there is a two-way causality between energy consumption and economic growth in CIS countries. This shows that the feedback hypothesis is valid in these countries. In Italy, there is a long-term, two-way causal relationship between energy use and GDP, and energy is limited for GDP growth [37]. Using cross-sectional and panel data from ten emerging markets and G7 countries, Soytas & Sari found a two-way causal relationship in Argentina, a causal relationship between GDP and energy consumption in Italy and South Korea, and a causal relationship between energy consumption and GDP in Turkey, France, Germany, and Japan [38].
Morelli & Mele claimed that economic growth and energy consumption exist in a one-way causal relationship [39]. In 47 developing countries from 1970 to 1976, the elasticity of energy consumption to GDP remained stable, which was significantly higher than 1, especially in developing countries [40]. Ang donated that the energy elasticity of high-income developing countries ranged from 1.6 to 1.8, while that of industrial countries declined slightly [41]. Lescaroux showed similar conclusions in different sectors and regions of 101 countries [42]. In the long run, the inverted U-shaped relationship between energy intensity and income has not been supported by all economic sectors. Nillesen et al. indicated that there is no inverted U-shaped relationship in most countries [43]. LLANOS et al. indicated that the range of treatments that produce the best performance, whether it is energy consumption or carbon emission policies, is between -2% and 0.4% [44]. In addition, extreme policies such as significantly reducing or increasing energy consumption will have the worst consequences for economic development [45].
GDP and CO2 Emissions
Following the Environmental Kuznets Curve (EKC) hypothesis, they first proposed this conjecture, i.e., that the positive relationship between environmental pollution and income reverses after the income reaches a certain threshold [46]. Most studies tested the inverted U relationship between economic growth and pollutant emissions. For example, Destek et al. found that an inverted U-shaped is confirmed only for the pre-1973 period in France, Italy, and the USA [47]. Holtz, Eakin, and Selden revealed that the marginal emission tendency of CO2 emissions gradually decreased with the increase in per capita GDP [48]. Some authors [49-51] reported the existence of the EKC hypothesis. Of course, not all results support the EKC hypothesis. Cole et al. found evidence against the EKC hypothesis. Using the ARDL method, many scholars have proven the relationship between economic growth and pollutant emissions in many countries [52]. For example, Massagony & Budiono found that in the long run, CO2 emissions will continue to rise simultaneously with income, implying that the EKC hypothesis is not valid for CO2 emissions in Indonesia [53]. Saboori and Sulaiman found a one-way causal relationship between GDP growth and CO2 emissions [54]. Raihan and Tuspekova revealed the coefficient of economic growth is positive and significant with CO2 emissions, indicating a 1% increase in economic growth is related to a 0.34% rise in CO2 emissions [55]. Saboori and Sulaiman supported the EKC hypothesis in Singapore and Thailand [56]. Jebli et al. found that there is a long-term bidirectional causal relationship between CO2 emissions and economic growth in 25 OECD countries [57]. There is a significant long-term negative correlation between CO2 emissions and GDP, while a short-term positive correlation indicates that the deterioration of environmental sustainability is due to long-term economic growth [58].
However, topics about environmental problems, poverty, and inequality are still rare. Some scholars believe that poverty is the decisive factor leading to environmental pollution, because economic pressure, population pressure, and environmental policies lead to the deterioration of environmental quality [59]. For example, both the low and the high-income are suffering from environmental pollution, but the poor are more affected, and the research on inequality and environmental problems is relatively lacking [60-61]. Baloch et al. attempted to investigate the relationship between income inequality, poverty, and CO2 emissions in 40 sub-Saharan African countries between 2010 and 2016 [61]. The results obtained from the Driscoll Kray regression estimator indicate that the exacerbation of income inequality has led to an increase in CO2 emissions [61].
Materials and Methods
Data
The study covered 35 years of electricity consumption, GDP, and CO2 emissions in 15 countries from 1980 to 2014. Data include high-income countries (Canada, Germany, Australia, Italy, Japan, France, the United States, and the United Kingdom) and low-income countries (Burundi, the Central African Republic, Niger, Gambia, Mozambique, Malawi, and Madagascar). Electricity consumption is available from the International Energy Agency (IEA) (https://www. iea.org/), GDP is provided by the World Bank (website: https://data.worldbank.org/), and CO2 emissions can be obtained from BP’s World Energy Statistical Review (website: http://www.bp.com/). Descriptive statistics are shown in Table 1.
As shown in Table 1, although the per capita GDP of poor and high-income countries varies greatly (73.5 times), the gap between CO2 emissions (93 times) and electricity consumption (82 times) is even greater. In the era of energy-driven economic operation, high-income countries took advantage of resources and technology and achieved more GDP growth at the cost of CO2 emissions, but low-income countries did not.
Model
In the panel vector autoregressive model (PVAR), the independent variable is related to the fixed effect. Therefore, it is necessary to use the forward mean difference method “Helmert process” when using the panel model to eliminate the state fixed effect. By using this method, the orthogonality between the transformed independent variables and the lagged independent variables can be maintained, so that the lag independent variables can use GMM system estimation coefficients more consistently, thus eliminating the forward average value of each individual (i.e., the average value of future observations in each period) and ensuring the orthogonality between the lagged variables and the transformation variables. Furthermore, in this way, the bias in coefficient estimation caused by the correlation between individual effects and regression elements can be avoided [62]. The estimation method and running program refer to Love & Zicchino [63] and their Stata program. The PVAR model has the following advantages: Compared with OLS (Ordinary Least Square), it can estimate the interaction between multiple variables at the same time. Compared with VAR (Vector Auto Regressive), it can deal with panel data and improve the sample capacity. Compared with VAR and OLS, it can control the problems of fixed effects and random effects in panel data. Compared with OLS, it can study the dynamic effects between variables through the impulse response function.
Table 1.
Descriptive statistics, unit root test and criterion for optimal lags.
[i] [1] The unit of lgdp is Million US dollars / million people, the unit of lco2 is a thousand tons / million people, and the unit of lelectricity is billion kilowatts / million people, N is the sample size, mean is the corresponding sample mean, S. D is the corresponding sample variance.[2] Since the average value of variables at the national level is not zero, the drift term is considered and the mean is eliminated to control the influence of cross-section correlation. ADF (PP test results are consistent, due to space constraints, not reported) test results show that the four statistics of variables all reject the null hypothesis of panel unit root, in other words, all variables are stationary. And further PVAR estimation can be carried out.[3] The mark “star” means the minimum for AIC (Akaike Information Criterion), BIC (Bayesian Information Criterion) &HQIC (Quinn Information Criterion) during all lag periods, the lag value corresponding to the minimum can be regarded as the optimal lag time.
Table 2.
PVAR-GMM estimation for low and high-income countries.
Panel Unit Root Test
Before proceeding in advance with the PVAR framework, the first step of the estimation process consists of examining the data properties of all the series in terms of stationarity.
Ronald Fisher first proposed that multiple statistical test evidence should be listed as one statistic; that is, a unit root test was performed on each individual to obtain the statistics of n individuals and their corresponding p values. After that, Choi proposed four methods to synthesize these p values into Fisher statistics [64]. The Fisher ADF test in Table 1 shows that all panels contain unit roots.
Results and Discussion
Selection Optimal Lags
Before carrying out PVAR, we should know the corresponding optimal lags for better estimation. In Table 1, we know that the corresponding panel of poor countries should choose five lag periods. For high-income countries, we prefer to choose three periods of lag.
PVAR-GMM Estimation
As shown in Table 3, the GMM (Generalized Moment Estimation Method) approach is used to estimate the relationship between electricity consumption, GDP, and CO2 emissions. For low-income countries, the electricity consumption of the second lag period has a significant positive impact on CO2 emissions, GDP has a shock attenuation impact on CO2 emissions, and the impact direction is positive and negative alternately. Electricity consumption of two lag periods and CO2 emissions of the third lag period have a significant positive impact on GDP; only CO2 emissions of the first lag period will have a positive impact on electricity consumption.
According to the above simple analysis, it can be seen that the low-income countries in the world can obtain short-term economic returns at the cost of pollution (electricity consumption can promote economic growth in a short time), but they are unable to translate their economic achievements into technological advantages to reduce their reliance on polluting energy (GDP in any period does not have a positive impact on electricity consumption, but CO2 emissions do, which shows that the cost of electricity consumption is high in terms of pollution).
Table 2 also shows that the electricity consumption of the second lag period and CO2 emissions of the first lag period have a significant impact on CO2 emissions in high-income countries; GDP of the first lag period, electricity of the second lag period, and the CO2 emissions of the third lag period have a positive impact on GDP, while electricity consumption of the first lag period, CO2 emissions and GDP of the second lag period have a negative impact on GDP; CO2 emissions and electricity consumption of the first lag period have a positive effect on electricity consumption, while CO2 emissions of the second lag period have a negative effect on electricity consumption.
Table 3.
Granger causality test.
Fig. 1.
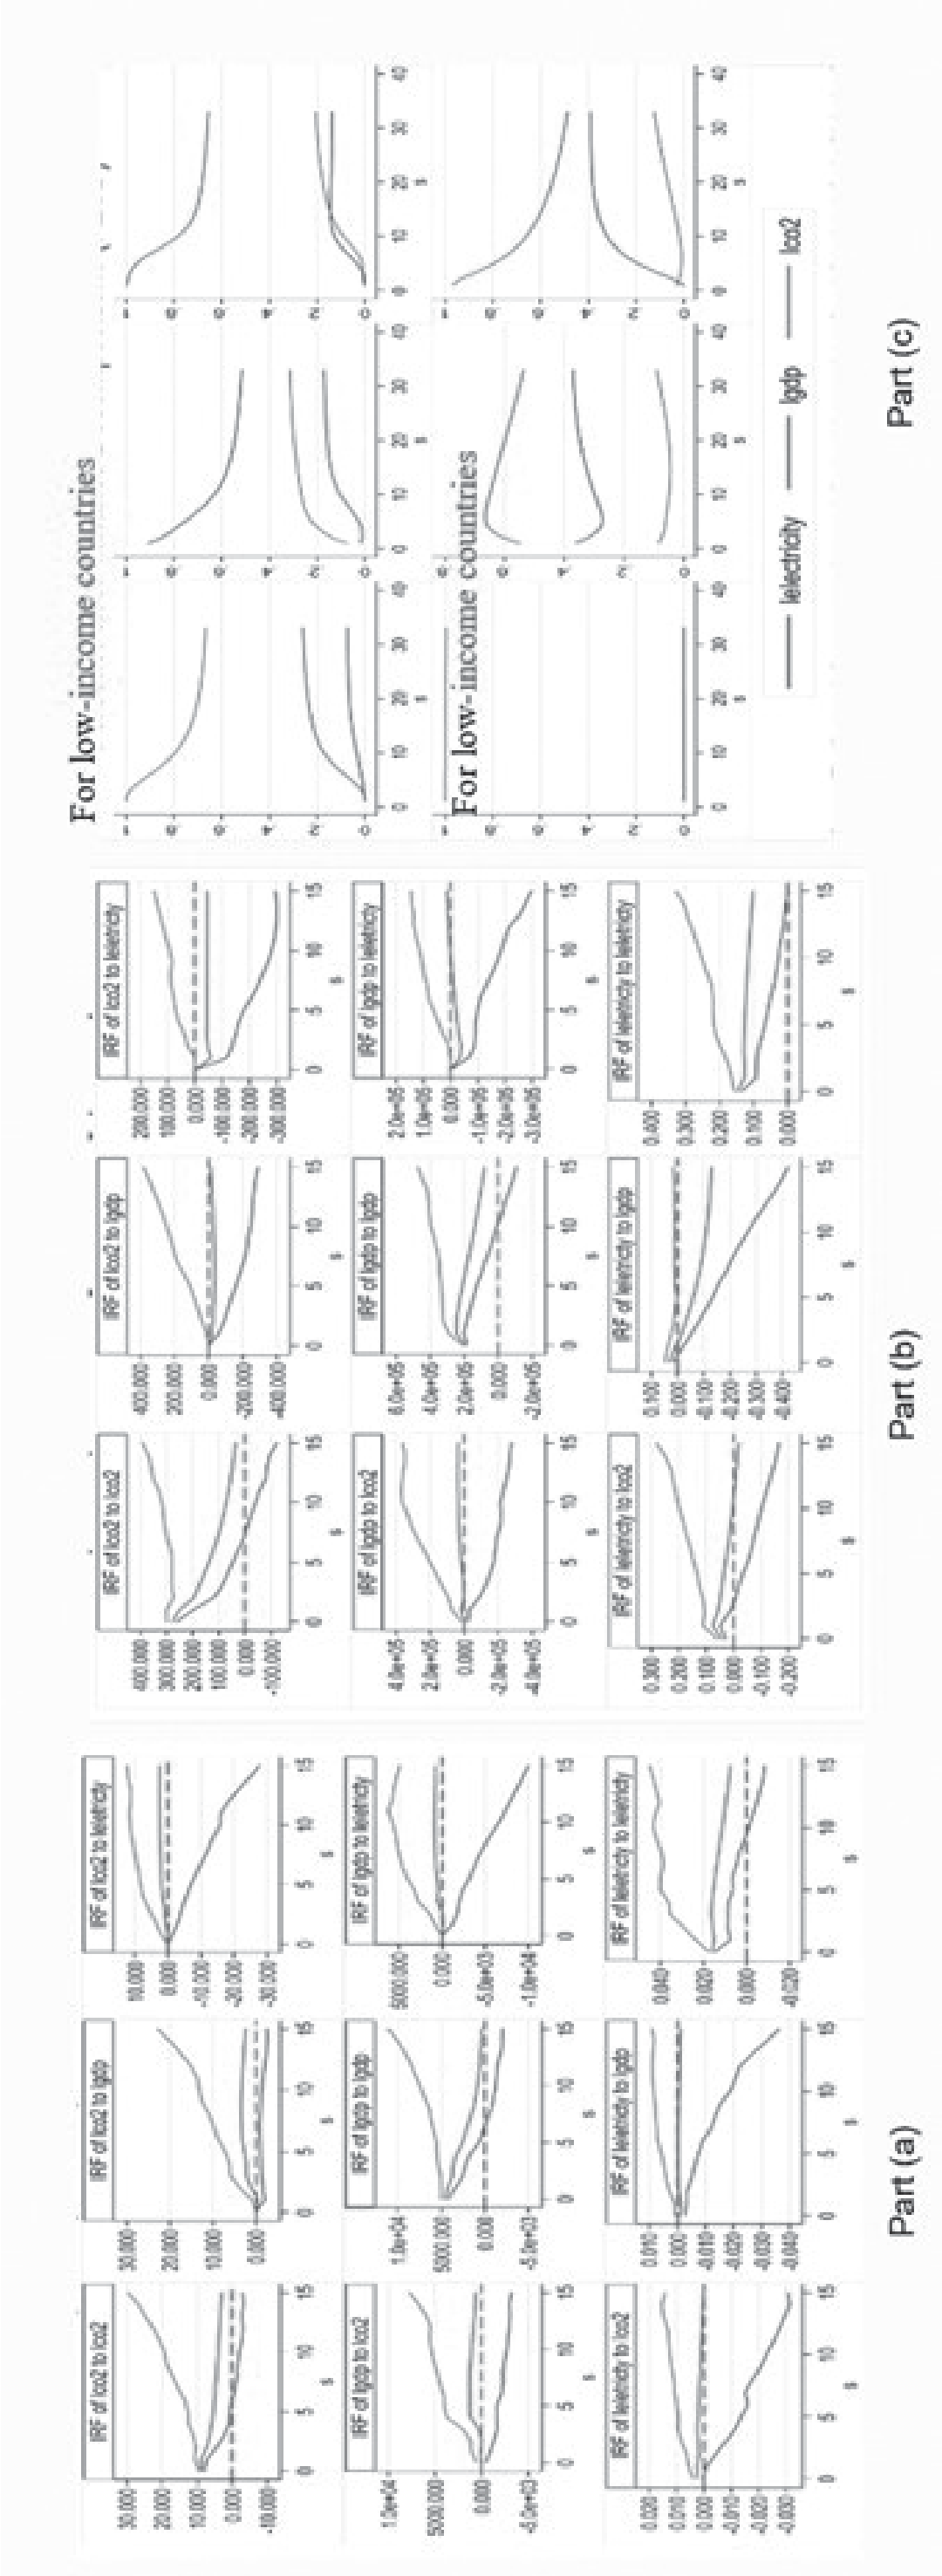
Impulse responses and for low and high-income countries Part (a) is impulse responses for low-income countries, Part (b) is impulse responses for high-income countries, Part (c) id forecast-error variance decomposition (FEVD) for high-and low-income
The main results in Table 2 show that the electricity consumption, CO2, and GDP of the first lag period in rich countries will further strengthen the current results, and the development mode relying on energy and pollution in the past is hindering the current economic development. It is gratifying that the economic development of rich countries has not continuously promoted power consumption and CO2 emissions, but has inhibited power consumption and CO2 emissions instead (though not significantly), which indicates that rich countries have begun to realize the importance of environmental problems and increase the development and application progress of alternative energy, but the effect may not be obvious.
Granger Causality Test
The Granger causality test further strengthens the relationship between CO2, GDP, and electricity in Table 3. For poor and high-income countries, electricity consumption is a single Granger cause of GDP. However, for high-income countries, CO2 emissions and electricity consumption are both Granger causes of domestic economic growth. However, it has not been tested in low-income countries, which indicates that CO2 emissions and electricity consumption may not make a significant difference in low-income countries’ economic growth.
Impulse-Response Functions (IRFs)
This subsection presents and discusses the results of the impulse response functions (IRFs) for low and high-income countries. For low-income countries (Part (a) in Fig. 1), although the positive impact of GDP on CO2 emissions is strengthened after the third period, the impact decreases rapidly. Electricity consumption has a short-term driving effect on CO2 emissions, but it is not obvious in the long term. Both CO2 emissions and GDP emissions have a positive impact on electricity consumption, but this impact is relatively stable. Although CO2 emissions and electricity consumption promote economic development, they are stagnant in the long term.
However, for the high-income countries (Part (b) in Fig. 1), the impact of GDP on CO2 emissions increases with time, but the impact of electricity consumption on CO2 emissions weakens over time. This is shown by the continuous popularization of clean power technology in high-income countries. At the same time, the impact of GDP on electricity consumption increases with time, but the impact of CO2 emissions and electricity consumption on GDP is not very strong for a long time (even for electricity, the impact is negative). The results show that the style of economic growth in high-income countries has undergone a fundamental change, i.e., from resource dependence to the technological revolution.
Variance Decomposition Analysis
Although impulse responses can give details regarding the influence of variations in one variable on other variables, they do not specify the magnitude and degree of these effects. As a result, the variance decomposition technique was performed to determine this. The variance decomposition provides information about the variation in percentages in the dependent series that is attributable not only to their own shocks but also to shocks generated by the other variables.
Part (c) of Fig. 1 shows the results of the variance decomposition obtained from the orthogonalized impulse response coefficient matrices. For low-income countries, the variance decomposition shows that CO2 emissions explain approximately 66.7% of the variations in CO2 emissions, 20.6% of the fluctuations in GDP, and 31.3% of the fluctuations in electricity. While GDP explains approximately 25.9% of the variations in CO2 emissions, 65.4% of the fluctuations in GDP, and 17.2% of the fluctuations in electricity. Besides, electricity explains approximately 7.4% of the variations in CO2 emissions, 13.9% of the fluctuations in GDP, and 51.5% of the fluctuations in electricity. For high-income countries, however, the variance decomposition shows that CO2 emissions explain approximately 99.5% of the variations in CO2 emissions, 12.4% of the fluctuations in GDP, and 9.1% of the fluctuations in electricity. Also, GDP explains approximately 2% of the variations in CO2 emissions, 48.7% of the fluctuations in GDP, and 53.8% of the fluctuations in electricity. Besides, electricity explains approximately 0.3% of the variations in CO2, 38.9% of the fluctuations in GDP, and 37.1% of the fluctuations in electricity consumption.
Conclusions
In summary, this essay tries to capture the nexus of electricity consumption, economic growth, and CO2 emissions in low and high-income countries. Due to technological differences, the cost of environmental governance varies greatly in different countries. High-income countries are economic and technological leaders they can develop clean power sources and further reduce CO2 emissions. In these countries, electricity consumption and CO2 emissions are Granger reasons for economic growth. GDP and CO2 emissions can guide them to explore electricity as a source of energy. Low-income countries (whether in the early stages of industrialization or not) are still highly dependent on traditional energy. It will take a long time to develop electricity technologies and reduce carbon emissions. In these countries, electricity consumption and CO2 emissions are Granger causes of economic growth, while GDP and CO2 emissions are not the Granger causality for electricity exploitation.
Based on the above findings, we propose the following policy recommendations:
First, international assistance. High-income countries should assist low-income countries in terms of economics and core technology. For economic assistance, Aid for Trade measures can be taken to build the capacity of low-income developing countries so that they can seize new market opportunities; for technical assistance, developed countries and international organizations should increase their technical assistance to low-income countries. Examples include joint research, development programs, and technical assistance, as well as the transfer of advanced clean technologies to low-income countries, cooperation between the public and private sectors, and the strengthening of local supply chains through joint ventures to facilitate transfer.
Second, low-income countries need to implement a low-carbon transition in their energy consumption structures. For example, by switching from traditional energy sources (fossil fuels) to cleaner energy sources, increasing the use of natural gas and electricity, and reducing the use of energy sources with high emission targets, such as coal and carbon, governments need to focus on the sustainable development of their economies and how to utilize their existing resources to achieve sustainable development and reduce carbon dioxide emissions. Examples of clean energy include wind, solar, and nuclear.

