

Introduction
The health of the earth is suffering as a result of the negative impacts of air pollution, climate change, water pollution and marine pollution [1]. In 2016 alone, six to seven million people worldwide died prematurely from indoor and outdoor air contamination, according to Global Environment Outlook 6, which was released by the United Nations Environment Programme on March 13, 2019. Carbon emissions are an important part of air pollution, which may be directly related to large-scale climate change [2]. Due to the greenhouse effect, which is caused by massive amounts of CO2 emissions, the average global sea level increased by 0.19 m between 1901 and 2010, and the temperature of the planet’s surface increased, on average, by 0.12ºC per decade from 1951 to 2012 [3]. In March 2019, the International Energy Agency (IEA) reported that global CO2 emissions from energy production rose by 1.7%, reaching a record high of 33.1 billion tons. In particular, China accounted for 24.2% of the world’s CO2 emissions in 2009 [4]. According to the IEA’s statistics, the CO2 concentrations in China increased by 156.7% from 1990 to 2005; In 2006, China exceeded the United States in terms of CO2 pollutants, ranking first in the world; Additionally, China’s CO2 emissions reached 9.24 billion tons in 2013, which is 28.6% of the total global emissions. To remedy this situation, the Chinese government promised to decrease CO2 discharges per unit of GDP by 40%-45% in 2020 from 2015 levels. Although the 2018 annual report on global monitoring of the ecological environment by remote sensing showed that this commitment has been fulfilled three years ahead of schedule, China is still under pressure to reduce carbon emissions as its economy continuously grows and investment further develops. A report from the IEA released on March 2, 2023, stated that in 2022, China’s carbon emissions fell by 23 million tons, but emissions still reached 11.5 billion tons, accounting for 31.25% of the total emissions [5]. To control carbon concentrations, China officially proposed the “double carbon goal” of achieving a carbon peak by 2030 and carbon neutrality by 2060 at the UN General Assembly in 2020. In 2023, the Chinese government announced that the “N+1” policy system of carbon peak and carbon neutrality had been successfully established to promote the realization of the “dual carbon” goal. However, facing the huge economic system and the traditional crude growth, many challenges need to be addressed to achieve China’s “dual-carbon” goal.
To deal with this issue, it is necessary to investigate the links between socio-economic factors and CO2 emissions. The association between economic growth and CO2 concentrations has attracted great concern in prior studies. Recently, some scholars have turned their focus to the linkage between financial development and CO2 discharges, because the interactive range of finance is extensive, and well-functioning financial advancement is helpful for income growth [2, 6]. The existing research has revealed that financial development can either accelerate or inhibit carbon emissions. Some scholars argued that a developed financial market could benefit enterprises by providing them with funding to enlarge their scale of production, which ultimately results in a rise in CO2 pollutants from production. Additionally, financial intermediaries may also encourage consumers to buy energy-intensive household products, which will release more CO2 gas [7]. The negative effect has also been supported by the argument that the improvement of the financial development level will promote economic growth and increase the output of society as a whole, causing more CO2 emissions. Conversely, some scholars emphasized the positive impacts of financial development in their analysis. It is usually believed that financial development has a technical effect, which can help firms enhance their production technology and abate CO2 emissions [8]. Meanwhile, regions with high levels of financial development tend to invest in clean projects, which consequently, will help to curb the release of CO2.
Hitherto, the available findings are still inconclusive, i.e., the results have shown positive, negative, or no influences of financial advancement on CO2 discharges. The possible reasons for the inconsistent results can be attributed to the following aspects. First, most of the existing studies adopt the ratio of deposits to GDP as the indicator of financial development [9, 10, 11], but all the characteristics of financial development cannot be described with only one indicator or limited indicators. Second, the previous literature mainly focused on the direct impact of financial development on CO2 concentrations by adding the measure of financial development as an explanatory variable [6, 7, 10], while the indirect influence of financial performance on CO2 emissions via economic growth has generally been ignored. Recently, several articles have discussed the indirect effects of financial development on carbon emissions. For example, Khan and Ozturk [12] examined the mediating role of economic growth in the connection between finance advancement and carbon emissions; Udeagha and Breitenbach [13] probed the moderating effect of economic performance on the finance-carbon interaction. However, these studies use parametric models with artificial and subjective settings that are prone to incorrectly estimate the indirect impact of financial development on carbon emissions. Third, a great deal of the research was based on the artificial construction of the function relation between financial development and CO2 concentrations, omitting the potential heterogeneity or nonlinearity of variables in the model setting. Xu et al. [14] discussed the nonlinear correlation between financial advancement and carbon releases, but neglected the heterogeneity factors; Although Xie et al. [15] considered the issue of heterogeneity, they only addressed the linear impact of financial performance on carbon discharges.
In response to these problems, this article introduces a partial linear regression methodology to explore the effect of financial development on CO2 emissions in China. The contribution of the present study is fourfold, as follows: (i) The study considers 11 indicators from the Chinese financial market to generate a composite index of financial development, covering the full range of banking, insurance and securities. (ii) The study integrates financial development and economic growth into a framework to explore their conjoint nonlinear effects on CO2 emissions. Particularly, the nonlinear indirect impact of financial performance is highlighted to demonstrate the important moderating role of economic growth between financial expansion and CO2 concentrations. (iii) The study introduces a partial linear additive panel model suggested by Xie and Liu [16] to overcome the incorrect function linkage setting in the full parametric models. The partial linear additive panel model allows the data itself to determine the types of relationships formed between the variables and has a smaller model error, which provides a higher explanation for analyzing the quantitative relationship between variables. (iv) The study performs nonlinear marginal analysis instead of traditional linear marginal analysis and implements spatial analysis to synthetically reveal the effect of financial performance on CO2 emissions from individual, temporal and spatial perspectives.
Literature review
Economic growth is regarded as the principal force behind the uninterrupted growth in global CO2 pollution. Numerous studies have investigated the causal nexus between economic level and carbon emissions based on the environmental Kuznets curve (EKC) hypothesis, which was initially proposed by [17]. The EKC assumption posits that income has an inverted “U-shaped” impact on carbon emissions. This hypothesis was supported by Halicioglu and Ketenci [18] and Jalil and Mahmud [19]. Contrarily, other scholars found that the relationship between carbon concentrations and economic level in most countries revealed an upward or downward trend rather than the inverted “U-shaped” trend [20, 21, 22]. Moreover, Pal and Mitra [23] observed that the influence of income on carbon dioxide was N-shaped and did not confirm the EKC hypothesis. China is viewed as a particularly attractive country in the literature. The relevant research, which has various research purposes and methods, does not provide a consensus on the presence of EKC in China. Some scholars have confirmed the validity of the EKC hypothesis at the national and regional dimensions in China [19, 24], while others have not [23, 25]. These mixed results suggest that the connection between income growth and CO2 discharges needs to be explored further.
In contrast to the forgoing association, the linkage between financial development and CO2 emissions is relatively scarce. With the development of globalization, the financial sector has become an integral part of the entire economic system [26]. There is no doubt that financial advancement also plays a crucial role in environmental performance. Existing studies have revealed that financial development affects carbon emissions through four main mechanisms: scale effect, wealth effect, technology effect and structural effect [15, 10, 27]. The scale effect indicates that financial development expands the use of energy and resources by influencing economic activities, thus increasing carbon emissions. Financial development will reduce capital borrowing costs, expand production scale and consumption demand, and enlarge economic output and energy consumption, increasing CO2 emissions [7, 28]. The wealth effect suggests that the strengthening of financial markets is associated with risk diversification in the economy and may accelerate the process of wealth generation. This means that financial expansion can ease liquidity constraints and increase wealth and resources. Increased wealth tends to stimulate economic growth, which in turn increases energy consumption and contributes to carbon emissions [15]. The technology effect holds that financial development is a key factor in the improvement of energy saving or environmental protection technology, so financial progress can reduce carbon emissions through technological action. Financial advances reduce intermediation costs and improve risk diversification, enabling private and public sector investors to invest in clean energy projects and favoring carbon improvements [26, 27]. Structural effect posits that improved financial performance leads to increased financial flows to green industries, supporting low-carbon technological innovation and accelerating industrial structural upgrading. It is beneficial to curb resource waste and promote the demand for renewable energy, which helps to build a low-carbon energy mix and mitigates CO2 emissions [7, 12].
Recently, some studies began to consider the association between financial development and carbon discharges. Sadorsky [10] argued that financial growth will encourage public enterprises to use energy-saving technologies, and then carbon emissions will decline. However, some evidence shows that financial expansion might have involved in new participants in some dirty industries, enlarged the production scale of enterprises and increased energy consumption, thereby increasing CO2 pollutants [7, 29]. Different from the negative or positive linear impacts, a nonlinear influence of financial development on carbon discharges has been discovered by several scholars, such as Nassani et al. [30] and Shahbaz et al. [31]. Regarding China, the previous literature also presented different results. The study of Jalil and Feridun [32] reported that China’s financial advancement is not at the cost of environmental pollution, but rather leads to a moderate alleviation in carbon contamination. Nevertheless, Zhang [7] stated that financial growth exerts a negative impact on CO2 emissions and contributes to deteriorating the environmental quality in China. Unlike the above scenario, Xiong et al. [33] revealed an inverted U-shaped non-linear linkage between financial performance and carbon discharges; A threshold effect of financial progress on carbon concentrations was confirmed by Tao al. [34]. Overall, the empirical results are ambiguous, i.e., financial development has both positive and negative effects on CO2 pollutants.
The controversial results may be attributed to the mechanism through which the financial performance influences carbon discharges is complex because of the potential indirect impacts of financial development on CO2 concentrations. A significant deficiency of the abovementioned works is that they fail to consider the indirect effect of financial development on carbon emissions. In fact, financial advancement not only directly affects the release of carbon but also indirectly impacts carbon emissions through its role in economic growth [35, 36]. A large number of studies showed that financial performance has an important effect on output level [2, 31], which affects carbon emissions. However, this indirect impact of financial growth on CO2 pollution has been largely ignored in the available literature. Without considering the indirect effect of financial development on carbon emissions, the accuracy of the results will be greatly underestimated, because the direct influence is likely to be dominated by the indirect influence [9]. To explore the influence mechanism of financial development on CO2 emission, an essential task of the current research is to comprehensively examine the causal connection between economic growth, financial development and CO2 emissions, which needs to be realized by applying the latest econometric methods.
Many approaches have been applied to investigate the determinants of CO2 emissions. In general, these methods can be divided into three categories from the model aspects: cross-section, time series, and panel data models. Despite their popularity, cross-sectional and time series models are often criticized for ignoring heterogeneity when adopting data from heterogeneous individuals and periods. Panel data models not only incorporate the heterogeneous effects but also avoid multicollinearity among the variables. In view of these advantages, panel data models have been extensively applied in the field of income growth and financial development concerned with carbon emissions, such as [6, 10, 25]. It is worth noting, nevertheless, that all of the panel models used in these studies are fully parameterized linear structures. Although the fully parametric linear models can immediately display the nexuses between the variables, they still have some shortcomings. On the one hand, the fully parametric linear models can only describe the linear linkages between the variables, ignoring other nonlinear forms. On the other hand, the structures of fully parametric linear models are set artificially; Therefore, it is easy to produce the wrong model setting [24, 37].
The purpose of this study is to present more evidence regarding CO2 contamination and to avoid deviations in policy decision-making by constructing a new measure of financial development based on the premise of full consideration of nonlinearity and heterogeneity. Empirically, the paper constructs a comprehensive financial advancement index rather than a single index to thoroughly quantify the influence mechanism of financial performance on carbon discharges. Different from the existing literature that only focused on the direct impact of financial development, this work simultaneously contains the indirect influence of financial advancement on CO2 emissions through its impact on economic growth, improving the cognition of the channels through which financial behavior indirectly affects the release of carbon. Methodologically, the research recommends a partial linear additive panel model proposed by Xie and Liu [16] to find the linear or nonlinear association between financial development and CO2 emissions. The advantage of this model is that it provides a better tool to explore the uncertain functional relationship between variables. Unlike the fully parametric linear models used by Yin et al. [6] and Zhang [7], the partial linear additive panel model is a data-driven model, which avoids model bias due to the artificial assumption of model structure and can more accurately reflect the relationships among variables. Different from the nonparametric additive model used by Xu and Lin [37], the partial linear additive panel model can better capture the individual and time heterogeneity, thus reducing the endogeneity of the model. In contrast to the generalized additive model in Wang et al. [38], the partial linear additive panel model incorporates multiple control variables to avoid the potential problem of missing variables. Moreover, the partial linear additive panel model extends the semiparametric model used in Wang et al. [39] to allow the simultaneous testing of nonlinear relationships between multiple explanatory variables and the explained variable. In this way, the effect of financial performance on CO2 pollution can be demonstrated more completely, and the involved findings can provide policy suggestions for boosting economic growth and lessening pollutant emissions.
Methodology
Most of the literature has applied the STIRPAT (Stochastic Impacts by Regression on Population, Affluence, and Technology) model as a theoretical framework to discuss the driving factors of pollutant emissions [37], which is defined as
where I means the pollutant emissions; P, A and T signify the levels of the total population, economic development and technological progress, whose coefficients are b, c and d, respectively; a indicates the intercept parameter and ξ is the random error term. With logarithmic linearization, model (1) can be written as the panel data form:
where i = 1, ..., N and t = 1, ..., T indicate the individual and period of observation, respectively; e = lnξ refers to the random error.
In this article, pollutant means CO2 emissions; The level of total population is measured by the total population mid-year; As in [40, 41], the state of economic level is usually represented by GDP per capita. Similar to [8], the number of patents is adopted as the technique proxy because the patent count is held to be a better measure of inventing activities, especially in the field of environment-related technologies. In addition, energy consumption is also considered an important determinant of CO2 emissions and is often incorporated into the model [8, 31]. Then, model (2) turns into
where CO2 represents carbon dioxide emissions; POP, GDP and TEC denote total population, GDP per capita and the number of patents, respectively; EC is the energy consumption whose coefficient is r.
The existing research has confirmed that financial development not only directly affects environmental quality but also indirectly impacts pollutant emissions by affecting economic growth [35, 36]. To describe the influence of financial development on CO2 concentrations, a generalized form of model (3) can be derived by adding the main variable of financial level and the interaction term of financial advancement and income level [42]. To reduce the problem of multicollinearity, we make a centralized transformation for the interaction terms, similar to [38]. Model (3) is extended by redefining the parameters as follows:
where α, βj and φj, j = 1, 2, 3 are unknown parameters; FD stands for financial development.
The purpose of this paper is to explore the direct and indirect associations between financial advancement and CO2 emissions. It should be noted that model (4) can only illustrate the possible linear linkage between them but ignores the existence of other relationships. In fact, the connection between financial level and carbon discharges is complex and uncertain because the factors of social progress vary in different circumstances. The traditional parametric models are restricted to fit unexpected characteristics and complex relationships, which is vulnerable to the risk of model specification bias [37].
To solve this problem, this study applies the partial linear additive panel models [16] to estimate the potential impacts of financial development on the release of CO2. The general form of the partial linear additive panel model is
where Yit denotes the explained variable; Xit is the key explanatory variable; gj(∙) refers to the unknown function to be estimated; ∑Pj=1 g j ( )⋅ represents the nonlinear part of the model (5); Zit is the control variable; βl is the coefficient of Zit,l; ∑lq=1βlZit,l denotes the linear part of the model (5); eit stands for the error term. The partial linear additive panel model has many advantages. First, the partial linear additive panel model can describe not only linear but also non-linear relationships among variables, providing a richer model structure. Second, the model is data-driven, which avoids model errors caused by artificial setups and facilitates more accurate estimates. Third, the partial linear additive panel model can reduce dimensional risk and solve the problem of potential missing variables in the presence of high dimensional variables. Fourth, the model includes the individual and temporal parameters to better capture individual and time heterogeneity. In particular, many of the panel models in use today are special cases of the model specified in the model (5). For example, if g1(∙) = ... = gp(∙) = 0, then model (5) becomes a two-way fully parametric fixed effect panel model; If p = 1, g1(∙) ≠ 0, ∑lq=1βlZit,l ≠ 0 , then model (5) turns into a semi-parametric panel model; If p = 1, g1(∙) ≠ 0, ∑lq=1βlZit,l = 0 , then model (5) is a non-parametric panel model; If ∑lq=1βlZit,l = 0 , then model (5) degenerates into a nonparametric panel additive model.
Given the above merits, this paper applies model (5) to explore the nonlinear relationship between financial development and pollution emissions. Specifically, the nonparametric forms of lnFD including the main and interaction terms introduced into the model (4) to investigate the unknown associations between financial advancement and CO2 concentrations. Moreover, to determine the shape of EKC, the nonparametric form of lnGDP is also included in the model. Furthermore, to consider the heterogeneity of the individual and time, individual and temporal fixed effect parameters are introduced into the model (4). Other variables are incorporated in the model as control variables to avoid the occurrence of missing variables. Therefore, the suggested model can be expressed by
where μi and γi are individual and temporal parameters; gj(∙), j = 1, 2, 3 is an unknown function that needs to be estimated.
It can be observed that the partial linear additive panel model (6) includes both nonparametric and parametric parts to describe the relationship between variables. In contrast to the currently used parametric models, for example, Xie and Sun [40] and Sadorsky [10], the proposed model’s form is not tightly restricted, which avoids the risk of misestimation caused by incorrect model settings. Compared with the nonparametric additive panel models [37], the present model overcomes the defects of these models that omit the influence of heterogeneity, providing better explanations for the unknown functional nexus between the variables. To obtain consistent estimation, Xie and Liu [16] put forward a two-stage method based on global splines and local polynomials to estimate the partial linear additive panel model.
Data Source and Description
As for the data scope of this research, panel data on China’s 30 provinces spanning the period from 2006- 2016 were collected to investigate the causal association between financial development and CO2 emissions. This time span covers a critical period in China’s economic and financial landscape. During this period, China experienced a period of rapid economic growth and profound changes in its financial markets. This timeframe includes the recovery period after the onset of the 2008 global financial crisis and a series of financial policies and reform measures adopted by the Chinese government, such as the QFII and RQFII regimes. Therefore, this time horizon was chosen to better capture the potential impact of financial development on carbon emissions. Additionally, the data for this time range are relatively complete and reliable. To measure the level of financial development more comprehensively, our financial progress index includes 11 sub-indicators. However, the sub-indicators of some regions cannot be obtained after 2016 or the statistical caliber is not uniform. To ensure the data quality and feasibility of the research, the sample period of this paper ended in 2016. The samples used here exclude the Tibet Autonomous Region, the Hong Kong Special Administrative Region, the Macao Special Administrative Region, and Taiwan Province due to incomplete data. The data on CO2 emissions were calculated and collected from [43]. Moreover, the raw data of per capita GDP (GDP), total population (POP), number of patents (TEC), and energy consumption (EC) were gathered from the China Statistical Yearbook.
In terms of financial development, many studies have explored various proxies, such as domestic credits by the banking sector as a share of GDP, domestic credits offered to the private sector as a percentage of GDP, liquid liabilities as a proportion of GDP, or some capital market index [10, 44]. However, all of these measures have been demonstrated to be unsuitable to represent financial development, because they are often too narrow and simplistic to reflect the efficiency and capabilities of different financial systems. Extending the work of [45], this study selects 11 indicators from the three perspectives of banking, insurance, and securities and constructs a synthetic measure of financial development. The selected 11 indicators are as follows:
(2) the number of financial practitioners (per square kilometer); (3) the number of bank branches (per 10,000 population); (4) the number of financial practitioners (per 10,000 population); (5) the number of deposits held by financial institutions (per capita); (6) the volume of loans held by financial institutions (per capita); (7) the ratio of premium income to GDP; (8) the ratio of premium income to population; (9) stock market funds as a percentage of GDP; (10) the percentage of loans with lower interest rates; (11) the amount of financing from non-financial institutions as a share of GDP. All raw data are from the Regional Financial Performance Report and China Financial Yearbook.
Considering the unequal dimensions of different measures, each indicator is first standardized by X(j) = (x(j) – min(j))/(max(j)– min(j)), where x(j) is the actual value of the j-th index, and min(j) and max(j) denote the minimum and maximum values of x(j), respectively. Subsequently, the indicator of financial development is calculated by
where wk is the weight of the k-th measure for k = 1,...,11. Following the coefficient of variation method, the weight wk can be determined by wk =ζk / ∑kK=1ζk , where ζk = σk/ηk, σk and ηk represent the standard deviation and mean value of the k-th measure, respectively. A large FD means a relatively high level of financial development.
The descriptive statistics of all the variables are reported in Table 1. Several facts deserve attention. There is a large gap between the maximum and minimum values of CO2 emissions. The result reveals the remarkable heterogeneity of carbon pollution among regions. Moreover, the value of CO2 concentrations varies from 2927.09 to 181798.03, indicating enormous discrepancies in different periods. The financial development also shows a great difference. The highest and lowest values of financial level are 79.48 and 1.12, with a mean value of 14.59. Furthermore, the rest of the variables also have relatively large ranges. These diverse values strongly suggest the existence of individual and temporal heterogeneity.
Table 1.
Descriptive statistics of variables.
Results and Discussion
Heterogeneity test
Controlling the intercept heterogeneity is an important issue due to the wide variations in terms of economic development, resource endowments and geographical distribution from different individual and time transitions. A heterogeneity test is required because the strong version of the homogeneity hypothesis will mask the individual and temporal characteristics, which could produce misleading and inconsistent results. To accurately evaluate whether the intercept coefficient is heterogeneous, standard F-statistics and LM-statistics [40] are used to examine poolability, as well as individual and time effects, respectively.
Table 2 presents the heterogeneity test results. As revealed in the table, the null hypothesis that the same coefficients apply to each individual is rejected at the 1% significance level based on the F-statistics, and the LM-statistics also remarkably refutes the hypothesis of no significant individual and time effects. This means that individual and time effects would greatly impact the economic variables. It also proves that the establishment of model (6) with heterogeneous effects is reasonable in this paper and that not considering such an impact will produce biased results.
Effects Analysis
The estimations of the nonparametric part of the model (6) are illustrated in Fig. 1. As shown in Fig. 1a), there is a negative linkage between carbon emissions and economic growth, indicating that the concentrations of CO2 will decline with an increase in income level. This conclusion is different from Xu and Lin [37] and Jalil and Mahmud [19], who found an inverse “U-shaped” connection between CO2 discharges and the economic level in China. However, our results are sustained by the study of Zhu et al. [25]. The possible reason for this result is that with the increase in income levels, the government and the public gradually pay more attention to environmental protection, and the technical level of the enterprise will also be significantly improved; Therefore, the ecological environment is improved [40]. The data from the National Bureau of Statistics of China show that from 2006 to 2016, the share of GDP of the secondary industry dropped from 47.6% to 40.1%; In contrast, the share of GDP in the tertiary industry increased from 41.8% to 51.8%. Moreover, the enactment of several environmental production laws, such as the Circular Economy Promotion Law of the People’s Republic of China in 2008, has effectively accelerated the development of green and low-carbon production.
According to Fig. 1b), financial development reveals a “U-shaped” pattern regarding its relationship with CO2 level. This means that the concentrations of CO2 tend to fall at the initial stage of financial advancement, and then increase as Chinese finance develops. This finding is inconsistent with Zaidi et al. [46] and Zhang [7]. The study by Zaidi et al. [46] concluded that financial expansion contributes to curbing carbon emissions because the financial sectors provide financial resources for ecological optimization and to support the use of clean technologies by the producers; However, Zhang [7] stated that financial growth is not beneficial for CO2 emissions in China. Unlike the above conclusions, this research confirms that the effect of financial development on carbon discharges varies depending on the level of development. This dynamic influence can be expounded by considering the scale effect, structure effect and technology effect of financial advancement on CO2 discharges. For a lower level of financial growth, financial expansion can attract more investment in research and development to promote technological progress in the region and can provide convenient financing for new local facilities to guide the upgrading of the industrial and energy structures; Consequently, financial development restrains CO2 emissions through technological and composition effects [47]. With the increase in finance, consumers and enterprises are more likely to obtain wealth and capital, which makes it easier to meet consumers’ demand for large-scale energy-consuming goods and motivates enterprises to mass produce energy-consuming household appliances, such as automobiles, houses, air conditioners, refrigerators, etc. [29, 48]. Hence, the scale effect of financial advancement begins to emerge, which will facilitate the release of CO2 gas. The above results show that pursuing the scale growth of finance cannot cut carbon emissions, as the growth of the financial scale has a catalytic effect on carbon emissions after breaking a certain threshold. For the current policies, enhancing the quality of financial development is key to cutting carbon emissions. It is necessary to promote the green transformation of traditional finance by adding green bonds, green stocks and green loans to change the investment and financing environment. Meanwhile, we need to strengthen the integration of finance and technology to promote industrial upgrading, improve energy efficiency, and achieve the goal of reducing carbon emissions.
Table 2.
Heterogeneity test.
| Test of poolability: F-statistics | Tests for individual and time effects: LM-statistics |
|---|---|
| 12.972*** | 1084.200*** |
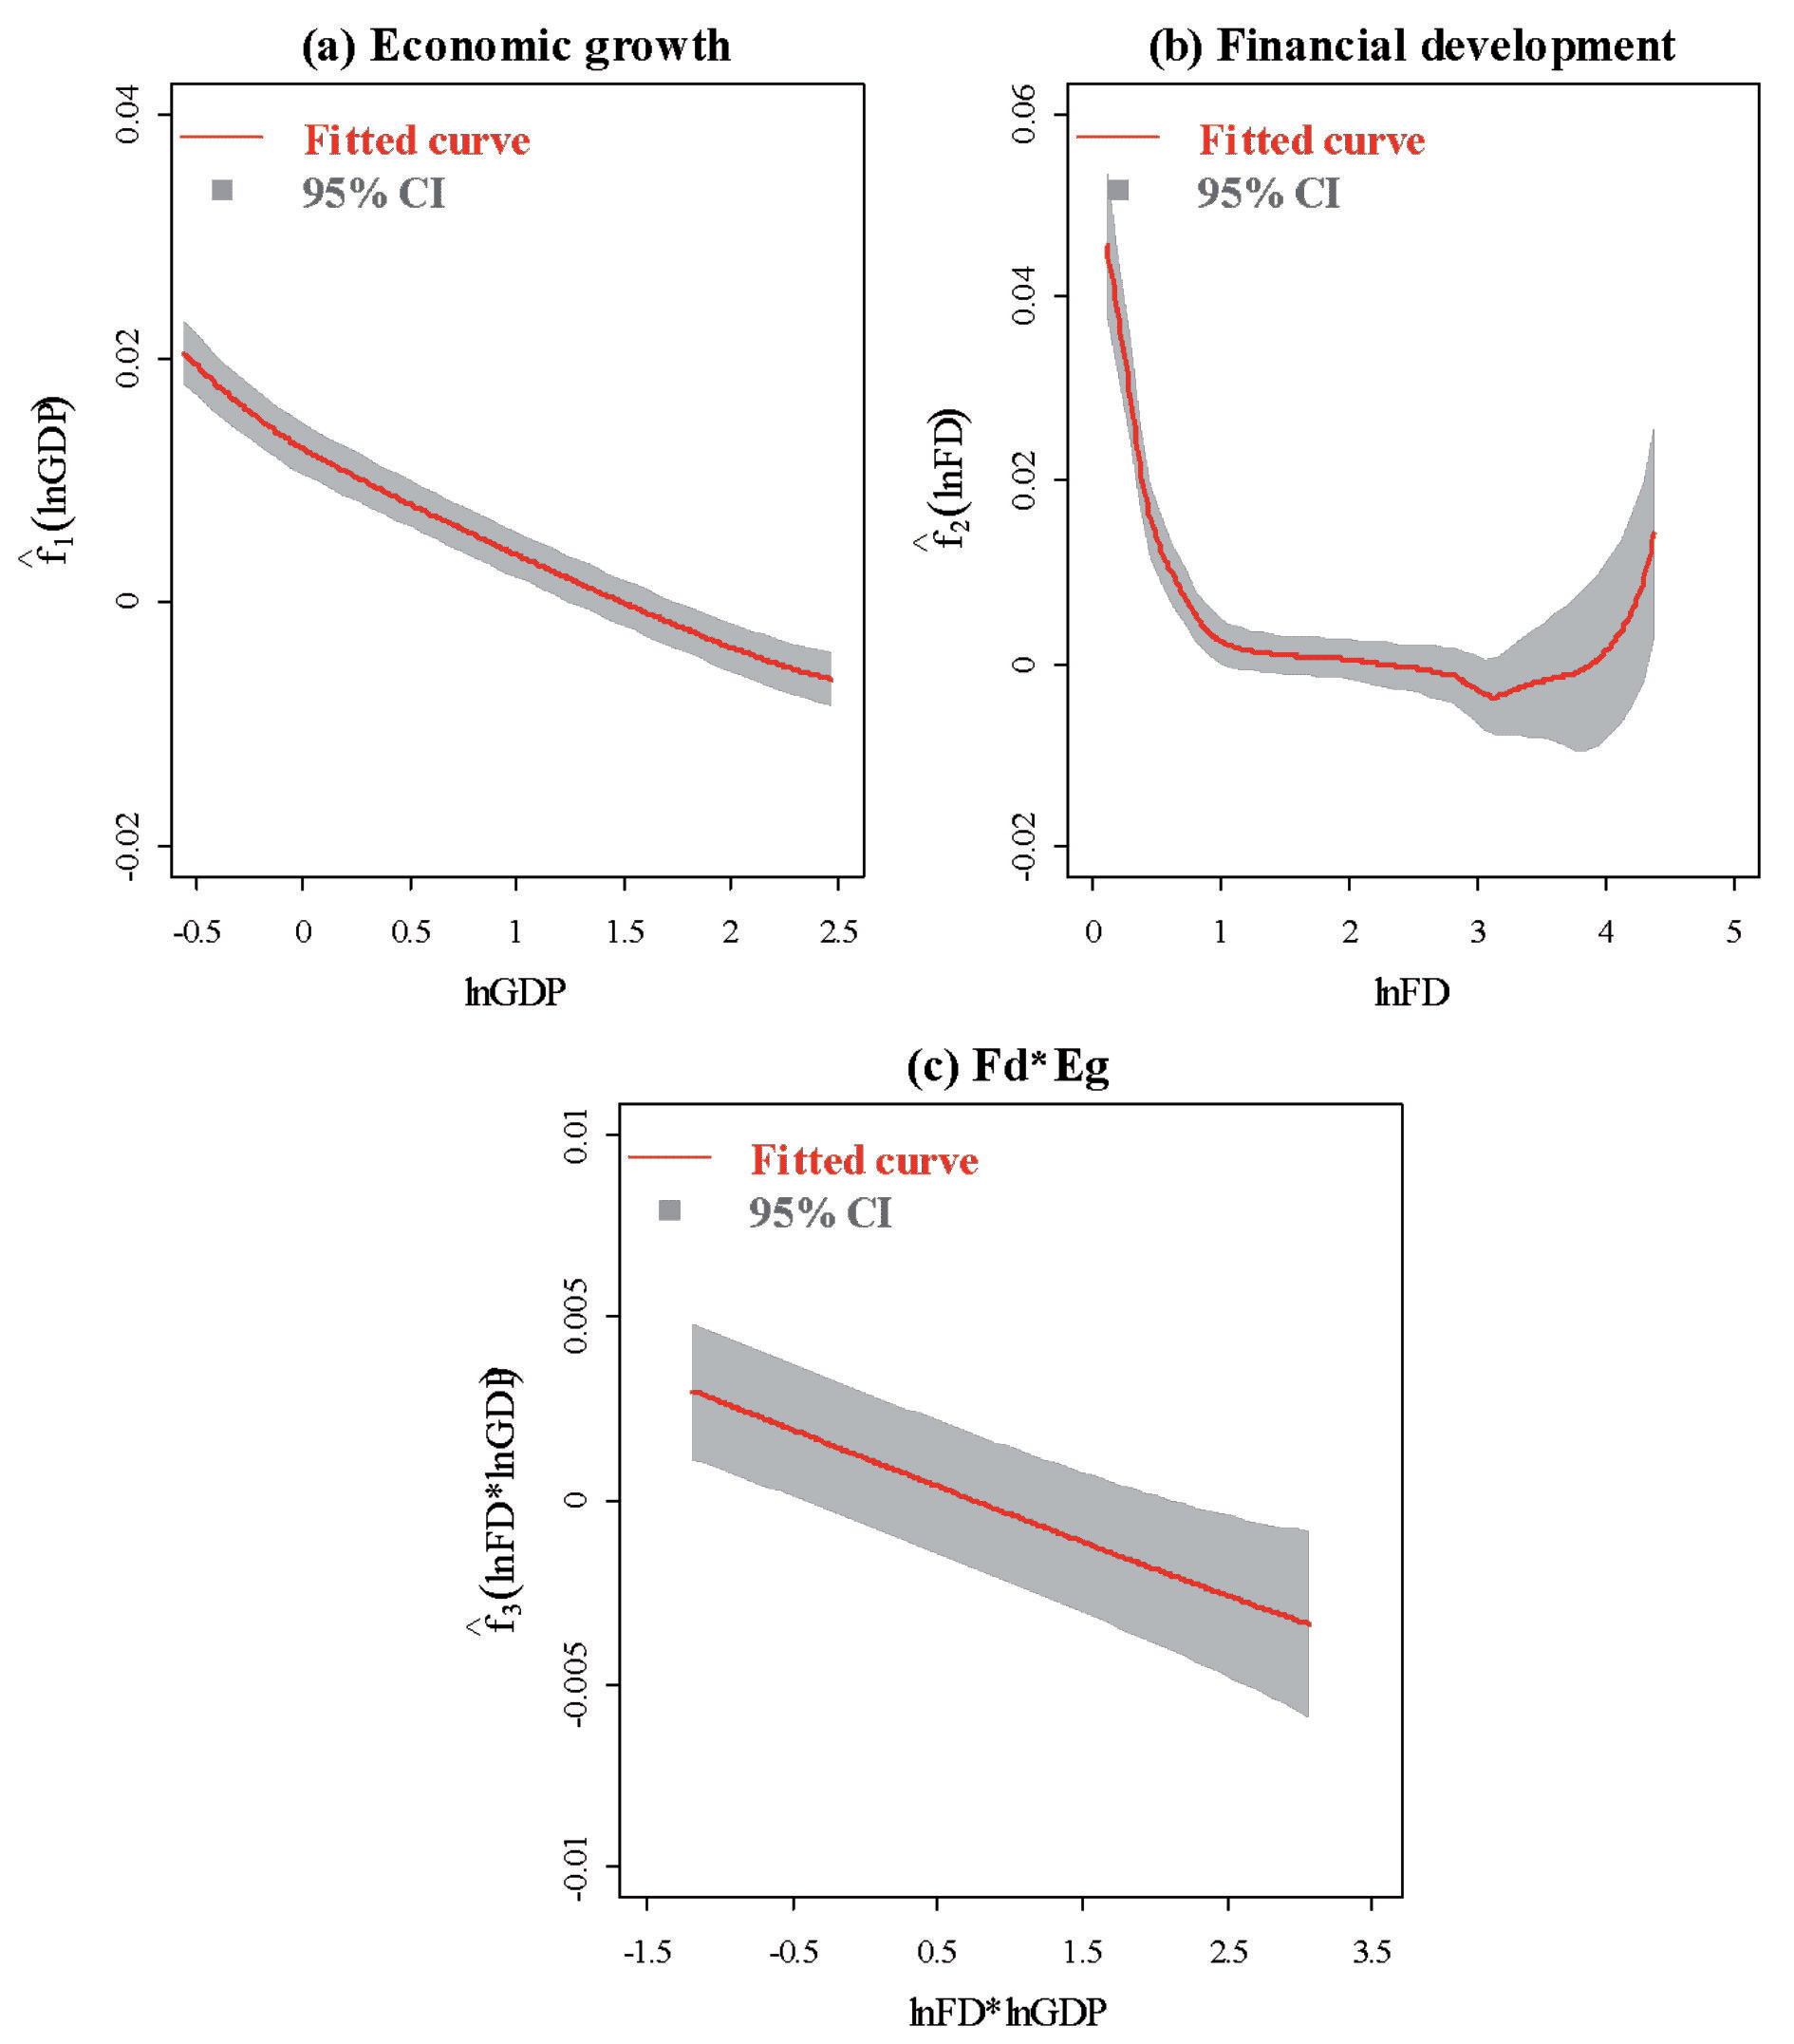
Fig. 1c) demonstrates the effects of the interaction between income level and financial development on CO2 concentrations. As shown in the figure, the discharge of CO2 can be abated when there is an interaction between income growth and financial development. The empirical results can be reinforced by prior studies, which show that the interaction between economic level and financial advancement is negatively related to carbon emissions, as in [42]. This finding provides further evidence that economic growth is less harmful to the environment in some areas with higher financial development levels. Theoretically, when income attains a certain level, its composition and technical influences will surpass the scale influence, and therefore, emissions descend with the growth of the economy [49]. It has been corroborated in the previous research that financial advancement is conducive to output rise through capital accumulation, and through all-round enhancement in productivity. Well-developed financial markets transform the industrial structure of an economy by allocating resources to augment production and to help companies apply more efficient and cleaner technologies, resulting in long-term sustainable income ascent. Therefore, a decline in CO2 emissions occurs as a result of comparative improvements in technologies and energy efficiency when economic growth is driven by financial development. This requires strengthening the services of the financial market for the real economy and reducing the barriers to financial empowerment of economic growth. Financial sectors should provide more sustainable financial advice and guidance, help enterprises formulate and implement low-carbon development strategies, guide the flow of capital to sustainable sectors, and promote the green transformation of the economy [50].
Table 3.
Estimation results of parametric components for whole sample.
| Variables | lnPOP | lnTEC | lnEC |
|---|---|---|---|
| Coefficients | -0.2562*** | -0.0042 | 1.0861*** |
| Std. Error | 0.0334 | 0.0027 | 0.0096 |
The estimations of the parametric part of the model (6) are reported in Table 3. The coefficient of the total population is -0.2562 and is significant at the 1% level. A 1% increase in the total population rate will contribute to decreasing CO2 emissions by 0.2562%. This result contradicts the conclusion reported by Hang and Jiang [51], who found that population growth is a critical driving factor in adding CO2 gas. The contradictory result can be explained by the aging of the population in China. The proportion of the elderly in the total population of China is increasing yearly, while the consumption and investments by the elderly are significantly less than that of the young, which decreases the usage of energy-intensive commodities, such as automobiles and air conditioners, thus reducing carbon emissions.
The technological factor coefficient is -0.0042, suggesting that technological advances will exert a positive effect on carbon emissions; However, such an effect is not statistically significant. This finding is in line with the conclusion of Wang et al. [38] in the case of China. On the one hand, technological progress brought about an increase in productivity, which promoted the development of energy-intensive products, such as automobiles, air conditioners, and refrigerators, bringing about a rise in carbon discharges. On the other hand, the advances in technology, especially in clean technologies, cut the cost of environmental governance and reduced the negative impact of production activities on pollutant emissions, resulting in a decline in carbon emissions [16]. Ultimately, because the negative and positive effects of technological progress offset each other, the contribution of the technological factor to CO2 emissions is insignificant.
The coefficient of energy consumption is highly significant at the 1% level, and its sign is positive, as expected. Specifically, a 1% increase in the rate of energy consumption would cause CO2 concentrations to increase by 1.0861%. Previous studies have shown that there is a bidirectional causal nexus between energy consumption and pollutant discharge in the short and long terms and that more CO2 will be released with high energy consumption [52]. Concerning this issue, our result is in accordance with this argument. As noted by [53], energy is mainly derived from the combustion of fossil fuels, leading to an increase in carbon emissions; Thus, high energy consumption will burn more fossil fuels and generate more CO2 emissions. Until now, China has been a large energy consumer, and the burning of coal is its main source of energy. For example, in 2013, the proportion of coal usage in China’s total energy expenditure was as high as 66%, while oil, natural gas, and non-fossil energy consumption accounted for only 18.4%, 5.8%, and 9.8%, respectively. It is clear that high energy consumption brings about more CO2 emissions.
Marginal Analysis
The traditional linear marginal analysis can only quantify the average effects between the variables for the entire observation. Obviously, this will hide some important or specific information and does not demonstrate the characteristics of each individual and stage, which can cause imprecise influence inference to occur. To offset the shortcomings of linear marginal analysis, this article estimates the elasticity of FD on CO2 emissions by conducting a nonlinear marginal analysis for the partial linear additive panel model. In light of model (6), the elasticity formula of FD corresponding to CO2 is
where g'2(∙) and g'3(∙) denote the gradient of g2(∙) and g3(∙), respectively.
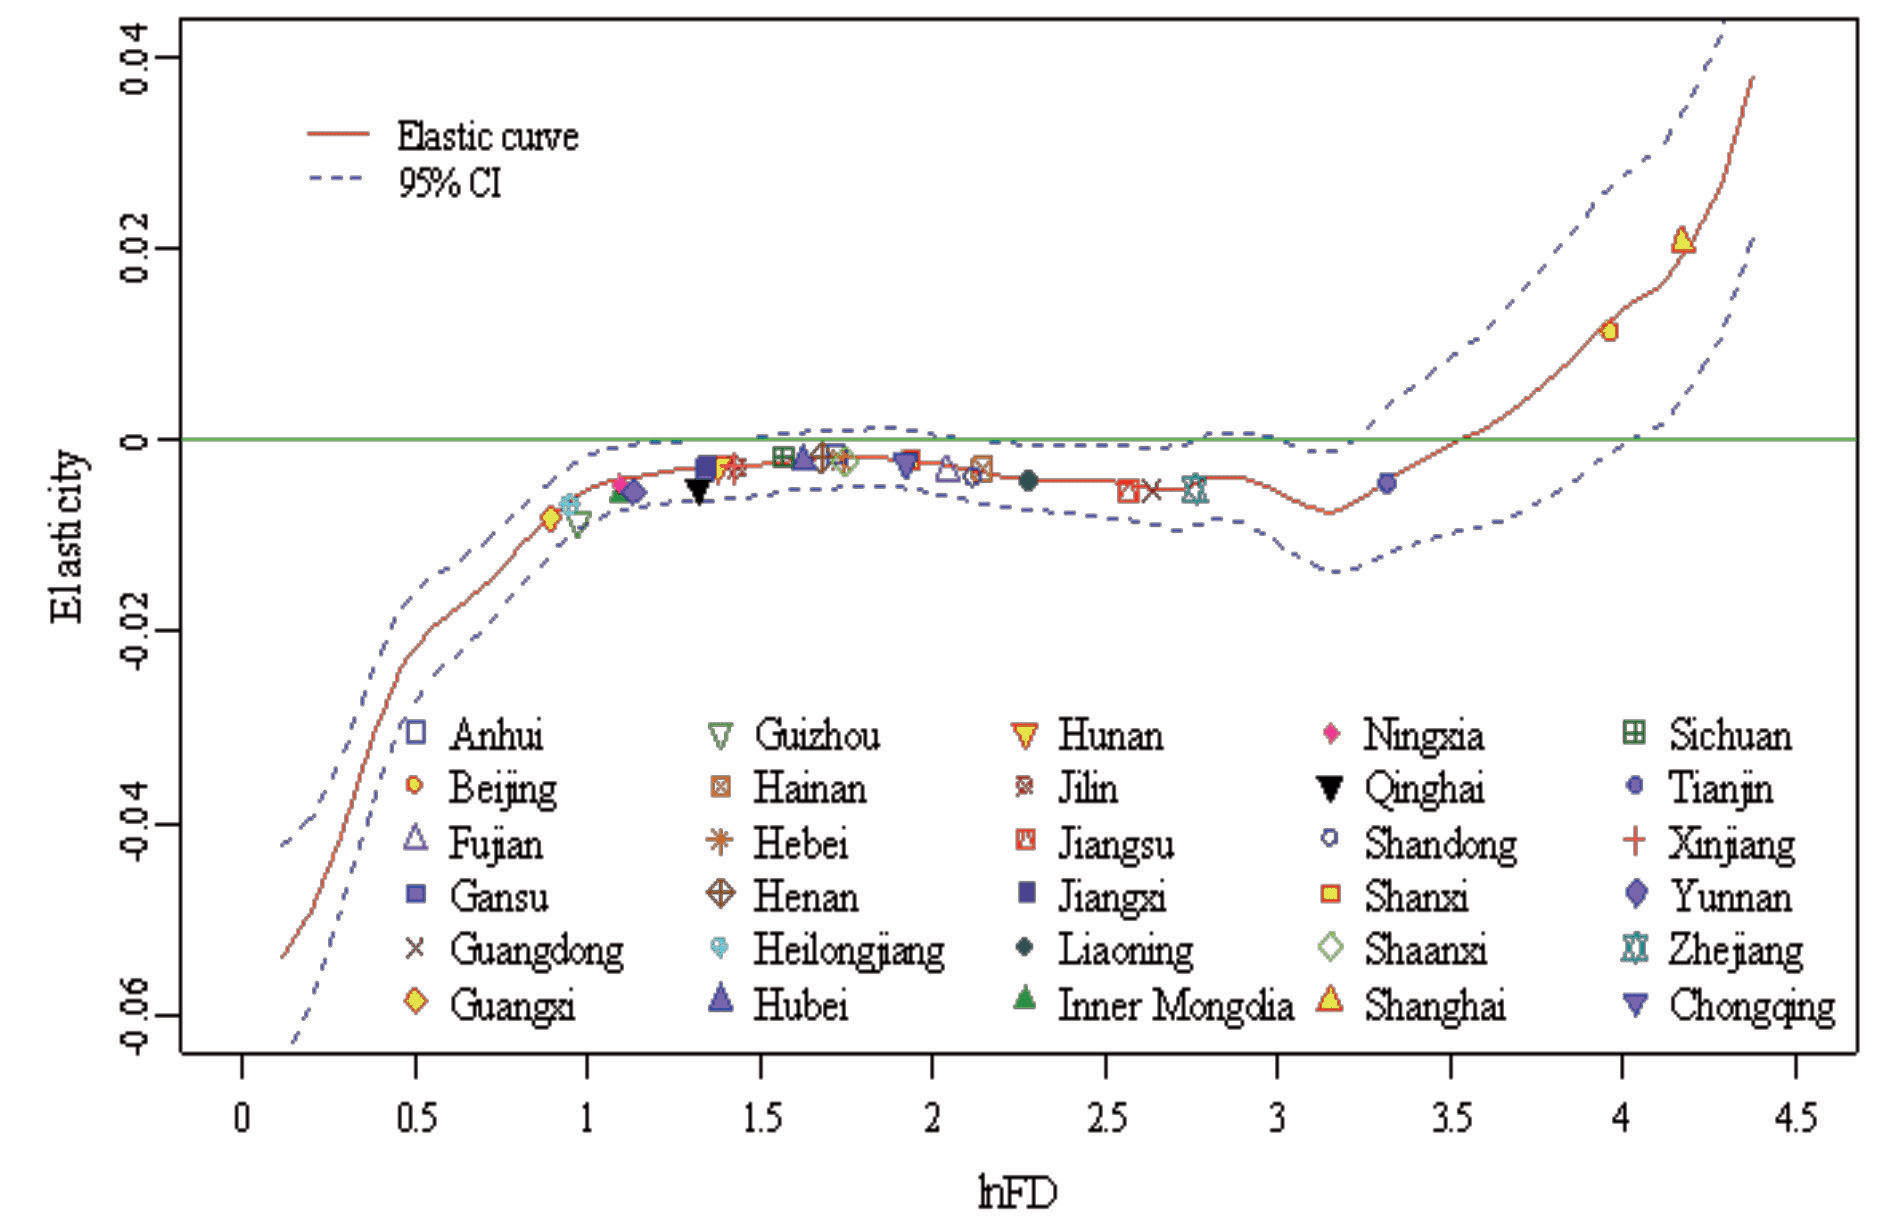
Fig. 2 presents the elasticity of each financial level in relation to carbon emissions. As shown in the figure, the elastic curve rises gradually with the increase of financial development and changes from negative to positive when lnFD equals approximately 3.5. The results suggest that CO2 emissions tend to decrease during the initial stages of financial advancement and then start to increase as the financial level continues to improve. One of the advantages of the partial linear additive panel model is that the individual influences are easy to analyze. According to Eq. (8), the elasticity of FD for each province can be computed by Ei = T −1∑Tt=1Eit and is also depicted in Fig. 2. The findings show that the elasticities vary significantly among all provinces and range from -0.01 to 0.03, indicating that there is evident heterogeneity in the various provinces involving the impact of FD on CO2 emissions. Except for Beijing and Shanghai, all the other provinces have negative elasticity, suggesting that financial development is conducive to the reduction of CO2 pollution. Consequently, China should actively promote financial development, which will benefit the environment. The development of a low-carbon economy needs a large amount of financial support [54]. Financial markets should promote the innovation of green financial products, develop and design more diversified financing tools, and guide investment in the construction and maintenance of green technology facilities to avoid the problem of insufficient financial supply in the field of carbon emission reduction. For Beijing and Shanghai, financial capital and services should be moderately directed towards environmentally friendly industries to avoid low-quality expansion of the traditional financial sector.
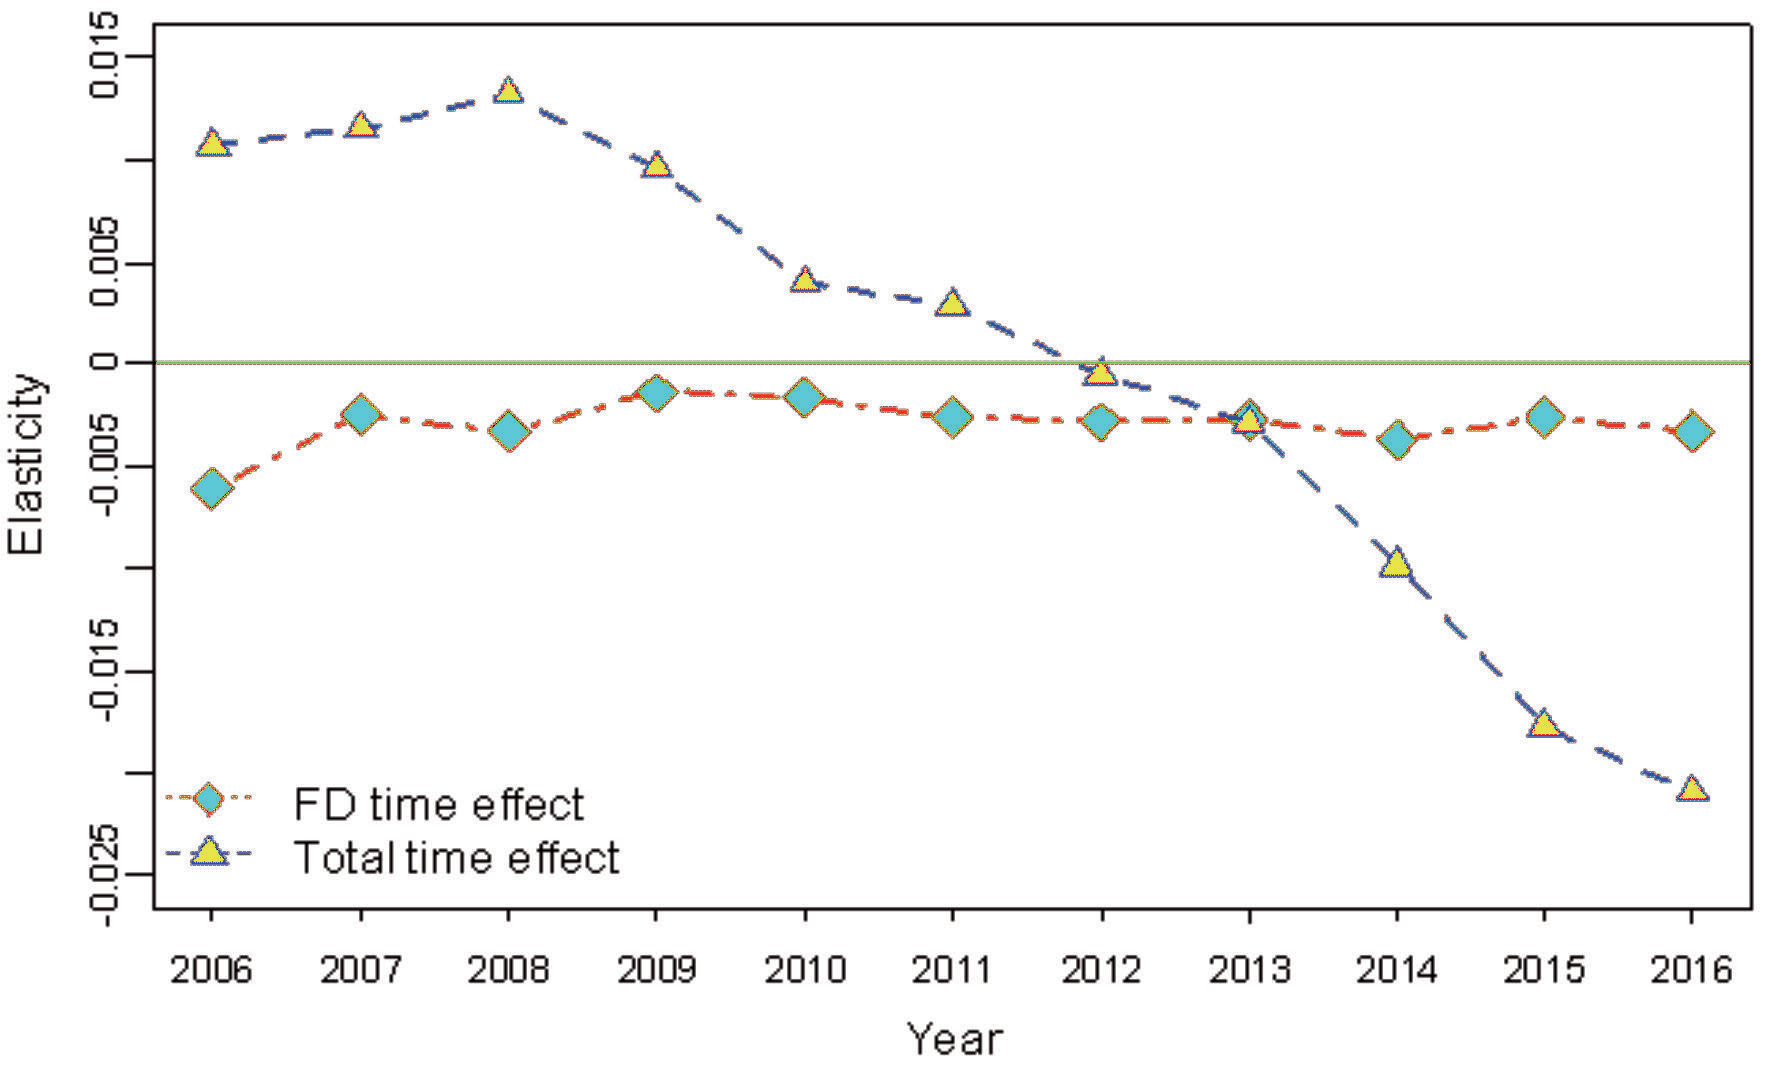
Another useful side of the partial linear additive panel model is that it allows us to explore the influence of temporal transitions. In the study of Wang et al. [39], the total time effect can be viewed as carbon emissions changing with different stages of the industrial optimization process. As demonstrated in Fig. 3, the total time effects reveal an inverted “U-shaped” style and switch from positive to negative. Since 2009, there has been a long-term downward trend in the total time effect. This result indicates that industrial structure upgrading and technical processes could help the reduction of CO2 discharges. The financial crisis of 2008 brought down many backward and energy-intensive enterprises and led them to place greater emphasis on high-tech and clean-tech production, which immensely pushed forward the structural and technical advancement of the Chinese industry. In 2012, the total time effect changed from positive to negative, demonstrating that industrial escalation and technical amelioration have increasingly helped to reduce emissions due to the promulgation of the 12th five-year plan for national environmental protection by the government of China in 2010. To identify the contribution of financial development to the total time effect, we calculate the time effect values of FD through Eq. (8), that is, En = N −1∑iN=1Eit . The time effect values of FD are also depicted in Fig. 3. It can be observed that the time effect values of FD are below zero and fluctuate around -0.005, suggesting that financial development plays a positive role in the total time effect. Consequently, it seems that developed finance is a good representative of modernization, and the pollutant emissions will be ameliorated with the advancement of finance.
Spatial Analysis
Considering the vast territory of China, there is heterogeneity among regions in terms of the economic development level, industrial structure characteristics, resource endowment, cultural customs, and environmental regulations. There are also large gaps in the levels of financial development in different spatial regions. These differences will affect the production decisions of enterprises, consumer preferences and so on, which indirectly influence CO2 emissions. Therefore, the spatial heterogeneity may have a significant impact on the association between financial performance and CO2 concentrations. To survey the influence of this spatial heterogeneity, we divide the whole sample into the northern and southern panels based on the Huai River policy in China [24] and analyze the linkage between financial growth and CO2 discharges from the spatial perspective.
In the northern region, the estimation of the nonparametric parts of the model (6) is depicted in Fig. 4. Similar to the case of the whole country, economic growth in the north is negatively correlated with CO2 emissions. In the initial stage, financial expansion is negatively related to the release of carbon; However, this influence is becoming increasingly smaller with the changing financial size; Finally, the curve demonstrating the financial development’s influence on CO2 emissions slopes upward at the end of the graph. Overall, the linkage between financial performance and CO2 concentrations is “U-shaped”, which is similar to the national situation. The influence of the interaction term on CO2 emissions reveals an inverted “U-shaped” model, which is different from the result in the whole country. Table 4 reports the estimation of the linear part of the model in the northern region. As observed from the table, the significance and symbols of the coefficients of total population, technology level and energy consumption are consistent with the national case. The elasticities of total population and energy consumption are -0.4373 and 1.1341, which are greater than those of the whole country. In contrast to the whole nation, the elasticity of the technology level is smaller (-0.0001).
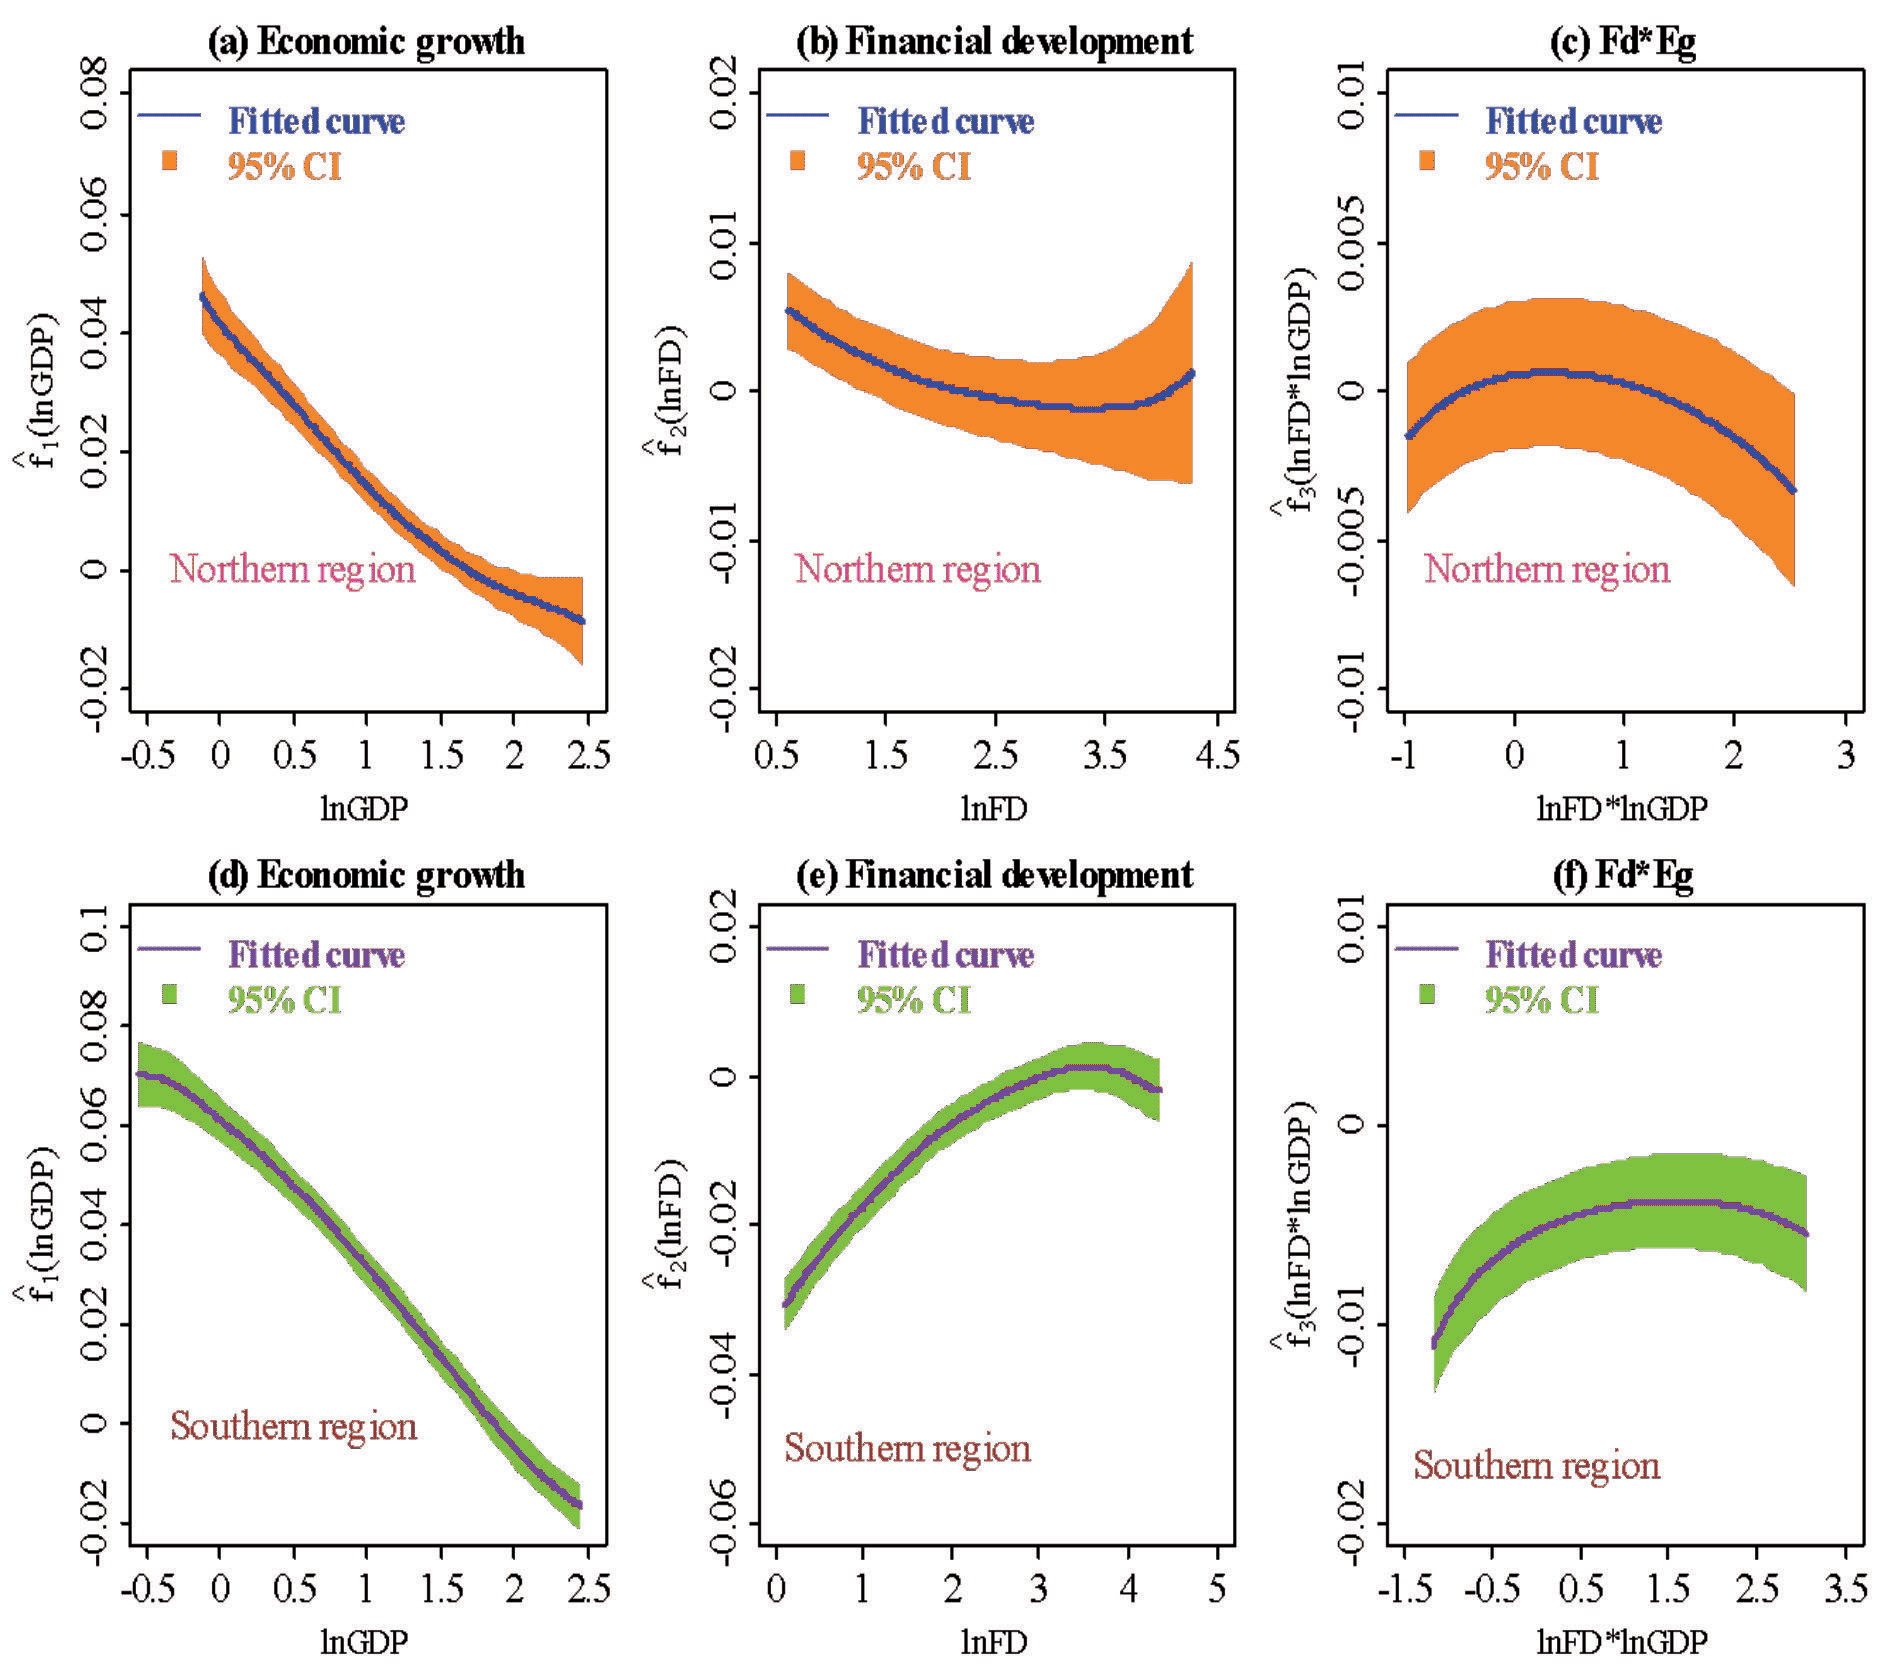
Table 4.
Estimation results of parametric components for region observation.
| Region | lnPOP | lnTEC | lnEC |
|---|---|---|---|
| North | -0.4373*** (0.0417) | -0.0001 (0.0041) | 1.1341*** (0.0121) |
| South | -0.0465 (0.0555) | 0.0211*** (0.0035) | 1.0283*** (0.0142) |
With respect to the southern region result, the estimation of the nonparametric parts of the model (6) is also presented in Fig. 4. The effect of economic growth reveals a negative linear style concerned with CO2 concentrations in the south. The result aligns with that of the northern region and the whole country. Financial development is initially positively correlated with carbon emissions; However, such a relationship begins to transition from positive to negative in the later stages. This indicates an inverted “U-shaped” nexus between financial advancement and CO2 emissions, which is inconsistent with the northern and national cases. For the southern region, the estimation of the linear parts of the model is also reported in Table 4. The coefficient of the total population is -0.0465, while it is statistically insignificant. This result is contrary to the northern and national findings that the population has a significant impact on the reduction of CO2 concentrations. Unlike the north and the entire country cases, the influence coefficient of the technology factor in the south is positive and significant (0.0211). The coefficient of energy consumption is 1.0283 and consists of the results of the northern and national areas, meaning that energy consumption plays a completely negative role in abating CO2 discharges.
Based on the above analysis, this paper finds that spatial heterogeneity has an important impact on the linkage between financial performance and CO2 concentrations: financial development in the north causes a rise in carbon emissions, whereas the southern region is just the opposite. The reasons for the discrepant effect of financial growth on CO2 emissions in different spaces may be related to the features of the local industrial structures. The industrial layout of China has the spatial characteristics of being heavy in the north and light in the south. The north area is rich in coal, oil, iron ore, and other mineral resources, so its industrial structure is dominated by mining, metallurgy, machinery manufacturing, and other heavy industries. This indicates that financial enlargement will promote the development of heavy industries in the local region, accelerating the consumption of coal and oil, and leading to a rise in CO2 discharges. In the south, it has plenty of high-end industrial raw materials, such as rare metals, precious metals and non-ferrous metals, but lacks coal, oil and other basic industrial raw materials, and the light industry is relatively developed. Therefore, the advancement of finance will encourage the development of light industries, which contributes to the decline of CO2 emissions. In the northern region, the financial sector should increase its support for technological innovation in heavy industry, and promote the transformation and upgrading of heavily polluting enterprises by issuing diversified green financial products, thereby indirectly reducing industrial carbon emissions. In addition, fintech interventions in the industrial sector should be extended to foster the digitalization of the industrial sector and enhance the low-carbon output capacity of industrial entities. For the southern region, there is a need to increase financial support for light industry, attract more financial resources and build a seamless connection with the northern financial markets.
Robustness test
To verify the robustness of the results presented in this paper, the parametric panel models are applied to regress the sample data with the same variables. The finding of the partial linear additive panel model has shown that lnGDP displayed a linear mode with a downward slope, lnFD presented a “U-shaped” style, and lnFD*lnGDP also presented a linear pattern with a downward slope in relation to lnCO2. This means that both lnGDP and lnFD*lnGDP exert a linear linkage with lnCO2, while lnFD has a nonlinear connection with lnCO2. Therefore, concerning such linear and nonlinear associations among lnGDP, lnFD and lnFD*lnGDP, the study adopts the parametric fixed-effects panel model involving a linear polynomial of lnGDP, a quadratic polynomial of lnFD and a linear polynomial of lnFD*lnGDP to investigate the linear and nonlinear relationships between them. Considering the individual and temporal heterogeneity, the parametric fixed-effects panel model is
where βj, j = 1, ..., 4 is an unknown parameter.
For the sake of comparison, the parametric pooled panel model and random-effects panel model are also employed to examine these linear and nonlinear relationships. The estimation results are reported in Table 5. It can be observed from the table that all three models present very similar regression results on economic growth and financial performance. The negative coefficient of lnGDP with high significance indicates an inverse linear association between the income level and CO2 discharges; The positive coefficients of (lnFD)2 along with the negative coefficients of lnFD exhibit a “U-shaped” connection between financial advancement and CO2 concentrations at a high significant level; The interaction term lnGDP*lnFD has a negative coefficient, revealing that financial development is negatively related to CO2 emissions through economic growth. All the results obtained by the parametric panel models are consistent with the conclusion of the partial linear additive panel model, which verifies the linear and nonlinear linkages among economic growth, financial advancement, and CO2 discharges.
For further comparison, the study employs the F-statistics and Hausman statistics to make an optimal selection among the pooled panel model, fixed-effects panel model, and random-effects panel model, as shown in Table 5. The null and alternative hypotheses of the F-statistics are the pooled panel model and the fixed-effects panel model, respectively. It follows from the table that the fixed-effects panel model dominates the pooled panel model due to the large F-statistics of 70.803. Concerning the Hausman statistics, the null hypothesis is the random-effects panel model against the alternative hypothesis of the fixed-effects panel model. As reported in the table, the fixed-effects panel model outperforms the random-effects panel model since the Hausman statistics generate a large value of 35.956. Combining the F-statistics and Hausman statistics, one can conclude that the fixed-effects panel model is better than the pooled and random-effects panel models. As illustrated, the estimation results of the fixed-effects panel model and the partial linear additive panel model are almost unanimous, with only a small discrepancy in the significance of the estimated parameters. However, this subtle difference will not affect the conclusion of the model. Moreover, the selection of the fixed-effects panel model supports the heterogeneity assumption in the partial linear additive panel model, therefore confirming that CO2 pollution is closely correlated with provincial and temporal influences. This means that if the individual and time heterogeneity is ignored, it will lead to a false model estimation.
Table 5.
Estimation results of linear parametric panel models.
Conclusions
Applying panel data for 30 Chinese provinces during the 2006-2016 period, the article introduces a partial linear additive panel model to investigate the direct and indirect impacts of financial development on CO2 emissions. With the help of nonlinear marginal analysis and spatial analysis, the nonlinear and heterogeneous impacts of financial development are discussed to provide new evidence for the evaluation of the relationship between financial performance and CO2 concentrations. Moreover, the empirical results are robust, which is shown by the usage of different methods.
The direct effect of financial development on CO2 discharges displays a “U-shaped” pattern, indicating that financial advancement is not always environmentally friendly. In the low stage of financial expansion, financial development will contribute to decreasing the discharge of CO2, but when the finance is developed to a certain point, CO2 emissions will increase. In contrast, the indirect impact of financial advancement on CO2 discharges is positive, confirming that an advanced financial market will benefit to moderate the effect of economic growth on CO2 discharges. The results of the nonlinear marginal analysis show that the influences of financial development in different provinces exhibit significant diversity, ranging from [-0.01, 0.03]; However, the influence of financial advancement in different periods has a little discrepancy, fluctuating around -0.005. The spatial analysis results reveal that the direct influence of financial development in the northern region displays a “U-shaped” style, which is consistent with the national case, but an inverse “U-shaped” type occurs in the southern area; Different from the entire country, the indirect effects of financial development display an inverted “U-shaped” mode both in the north and south.
In the light of these conclusions, some policy recommendations are suggested.
The results reveal that the direct effect of financial development on CO2 emissions reveals a “U-shaped” mode, meaning that the current model in boosting financial expansion is not entirely environmentally sustainable, as carbon emissions will increase when the financial scale reaches a certain level of accumulation. Thus, the government should pay attention to the role of finance in promoting clean and low-carbon development and appropriately guide financial capital and services to the environmental industries. It is necessary to standardize and improve the multi-level green financial market, which mainly includes regulating and heightening the allocation of financial resources, such as green funds, green bonds, green insurance and the carbon trading market to meet the demands of investment and capital in green development. Bank loans should favor clean and low-emission enterprises, especially to encourage and support the development of resource-saving and environment-friendly projects. Furthermore, financial development should be moderate because a proper scale of finance can help in the reduction of carbon emissions. In this regard, the relevant supervision departments need to strengthen their control over the M2 supply and cash growth to decrease the unfavorable influence of financial advancement on CO2 emissions.
The findings show that the indirect effect of financial development on CO2 concentrations is negative, indicating that a developed financial market contributes to reducing carbon emissions through the medium of economic growth. As a policy implication, the financial input should be increased for technical import and R&D as soon as possible to benefit the reduction of energy consumption and the improvement of production efficiency. Because there is a large gap in the economic output level and resource endowment conditions among the provinces in China, the influences of financial development on carbon emissions are not the same. Therefore, differentiated financial development strategies should be formulated and arranged in line with the local conditions, while promoting regional income growth. Meanwhile, the central bank should adjust the financial credit policy of enterprises and optimize the allocation mechanism of financial resources. In this respect, cleaner firms should be given more financial support, while polluters should face higher taxes, lower capital allocations and even shutdowns.

