

Introduction
The climate crisis, characterized by high risk, globality, and long-term impacts, is a key issue that the global community is currently trying to address [1]. The main cause of this problem lies in the combustion of large amounts of oil, natural gas, and other energy sources during the course of industrial development, which produces carbon dioxide. The report “CO2 Emissions in 2023” released by the International Energy Agency indicates that global energy-related carbon dioxide emissions reached a historic high in 2023, totaling 37.4 billion tons, making urgent action to reduce emissions imperative. As the basic units of the industrial system, enterprises are the micro-entities that consume fossil fuels and bear the responsibility for carbon emission reduction. Promoting the low-carbon transition of enterprises is of significant importance for achieving the “carbon neutrality” or “zero-carbon” goals proposed by nearly 150 countries globally.
Corporate carbon emission reduction actions are influenced by many factors, including external events such as environmental regulation [2], extreme weather, digital economic development [3], carbon constraint targets [4], and ESG rating events [5]. They are also affected by many internal factors, such as managerial climate attention [6], executive green cognition, earnings pressure [7], and board gender diversity [8]. However, from the perspective of resource-based theory, the success of a company’s low-carbon transformation depends on capital. Thus, many scholars have noticed the impact of traditional finance on corporate carbon emission reduction. Studies holding the positive view argue that financial development can promote green innovation and carbon emission reduction by alleviating financing constraints [9]. In contrast, studies holding negative and non-linear views argue that excessive financial support might lead firms to expand their production and have adverse effects on corporate low-carbon transitions in the absence of reasonable resource allocation [10].
With the spread and application of digital technology in the financial industry, DF, which boasts advantages such as inclusive financing, informatized investment management, and high service efficiency, not only strengthens the inherent functions of traditional finance by attracting long-tail customers and reducing service costs but also utilizes big data technology for credit management and risk prediction to guide funds into target industries, providing a potential solution to the limitations of traditional financial services. Then, can DF effectively curb CCE? What are the mechanisms? Clarifying these issues will provide a clear and feasible path for enterprises to achieve their carbon emission reduction goals.
Scholars have widely discussed the green effects of DF in existing research. They have confirmed that DF could produce positive effects in areas such as the green economy, environmental governance [11], green total factor productivity [12], and energy transition [13]. Meanwhile, many scholars have explored the relationship between DF and carbon emissions. Bu et al. [14] and Song et al. [15] empirically found that DF could reduce regional carbon emissions and intensity. Sun et al. [16] and Zhou and Wang [17] discovered that DF could improve regional carbon productivity and performance, with green, energy, and production technologies innovation playing important path effects. In addition, many other experts focused on mechanisms for DF to reduce regional carbon emissions. They found that industrial upgrading, energy structure optimization [18], and resource allocation optimization [19] are reliable pathways, while environmental regulation [20], financial regulation, and expansion of higher education [21] are important moderating factors. At the household level, some research found that DF would have a negative impact on residential carbon emission reduction, and factors such as residents’ consumption and income would affect this effect. However, at the micro level, research on DF primarily focused on corporate green investment and innovation [22], with little direct involvement in CCE [23], and related analyses remain at a relatively superficial level.
Overall, existing research has extensively investigated the impact of DF on carbon emissions and noted the critical pathway of green innovation, providing a valuable reference for this study. However, there are still some research gaps. Firstly, existing research mostly focuses on the regional level, with a lack of depth and systematic analysis at the micro level. Secondly, the research emphasis has not directly focused on low-carbon technology innovation, which plays a core role in reducing carbon emissions. A detailed analysis of low-carbon technology innovation pathways and precise recommendations for strengthening these pathways need to be further investigated. To this end, this study selects China, which ranks among the top in both carbon emissions and the development level of DF, as the research area. Based on data samples of Chinese A-share listed companies from 2011 to 2021, this study adopts fixed-effect, spatial Durbin, mediating effect, and moderating effect models to systematically explore the actual effects of DF on CCE and the path effects of low-carbon technology innovation.
The potential contributions of this study are as follows. First, this study incorporates DF, low-carbon technology innovation, and CCE into the research framework, enriching relevant theoretical research. Second, this study examines the actual impact of DF on CCE and explores the differential impacts of DF from the perspectives of industry heterogeneity and corporate executive green cognition heterogeneity, helping to expand the scope in which DF operates. Third, this study employs keyword filtering technology to identify low-carbon patents and provides a detailed analysis of how the low-carbon technology innovation path affects the relationship between DF and CCE from the perspectives of the quantity, quality, difficulty, and type of low-carbon technology innovation, conducive to revealing the impact mechanisms of DF. Fourth, from the perspectives of government hard constraints and market soft regulations, this study explores the moderating effects of carbon regulations and corporate ESG rating events on the low-carbon technology innovation path, helping to provide feasible suggestions for strengthening the low-carbon innovation path of DF and maximizing the carbon reduction impact.
The remainder of this paper is organized as follows. Section 2 formulates the theoretical analysis and research hypotheses. Section 3 describes the research design. Section 4 presents the empirical results and provides discussions of the findings. The conclusions and policy implications are provided in Section 5.
Theoretical Analysis and Hypotheses
Digital Finance and Corporate Carbon Emissions
Digital finance refers to the new generation of financial products that combine advanced information technology with traditional finance [24]. Financial institutions can apply digital technology to provide social members with payment, credit, investment, insurance, and other convenient financial services [25]. It removes the temporal and spatial constraints of traditional services [26] and significantly optimizes business processes. Thereby, it can directly reduce the carbon emissions resulting from travel or the use of paper materials during the financing process for enterprises [27].
As a financial innovation, DF can also address a key issue affecting corporate low-carbon transitions, which is funding support. Compared to traditional business models, DF does not require fixed physical locations or a large amount of asset collateral, reducing agency fees and interest charges and thereby saving on financing costs for enterprises [28]. DF also has inclusive properties, enabling it to attract more long-tail customers and benefit more funding seekers, thereby continuously expanding the pool of available funds. Moreover, DF can promote firms’ high-quality development by correcting scale, attribute, and industry mismatches [29]. Thus, DF will provide more potential financial support for corporate low-carbon activities [30]. However, one concern is whether the availability of more abundant funding might trigger a “production increase effect” similar to that seen with traditional finance, potentially leading to increased CCE. Obviously, the “digital” capabilities of DF can leverage big data platforms and cloud computing technology to integrate and analyze massive amounts of data [31], avoiding the flow of funds into high-energy-consuming and high-emission production activities. It helps green businesses and projects obtain timely funding, which is beneficial for corporate low-carbon transitions [32].
Moreover, DF can also promote corporate carbon emission reduction by empowering green finance [33]. On the one hand, a well-developed information network could clearly disclose corporate environmental and carbon information, enhancing the operational efficiency of the green finance market [34]. On the other hand, green finance activities such as carbon finance and green lending can leverage DF platforms to broaden funding channels and facilitate investment decisions, thereby promoting the circulation of green funds and supporting corporate low-carbon activities. What’s more, the digital infrastructure that underpins the development of digital finance not only enables businesses to utilize big data technology for energy consumption calculations to control carbon emissions more precisely but also allows consumers to participate further in environmental management, enhancing public awareness of low-carbon living [35, 36]. Thus, this study proposes the following hypothesis.
Hypothesis 1. DF has a suppressive effect on CCE.
DF is not limited by physical facilities and enables financial services to transcend geographical boundaries, benefiting clients in surrounding areas [36]. Meanwhile, the rapid development of local DF can generate a demonstration effect, triggering autonomous learning in neighboring regions. It can also support the development of DF in nearby cities through information exchange, the mobility of high-end talent, and the spillover of digital technologies, thereby reducing carbon emissions of surrounding enterprises [37]. Additionally, the improvement of local enterprises’ low-carbon performance will pressure surrounding governments to place greater emphasis on corporate carbon emission management and introduce relevant policies [38, 39]. Therefore, hypothesis 2 can be formulated.
Hypothesis 2. DF can simultaneously reduce enterprises’ carbon emissions in both local and surrounding cities.
Path Effects of Low-carbon Technology Innovation
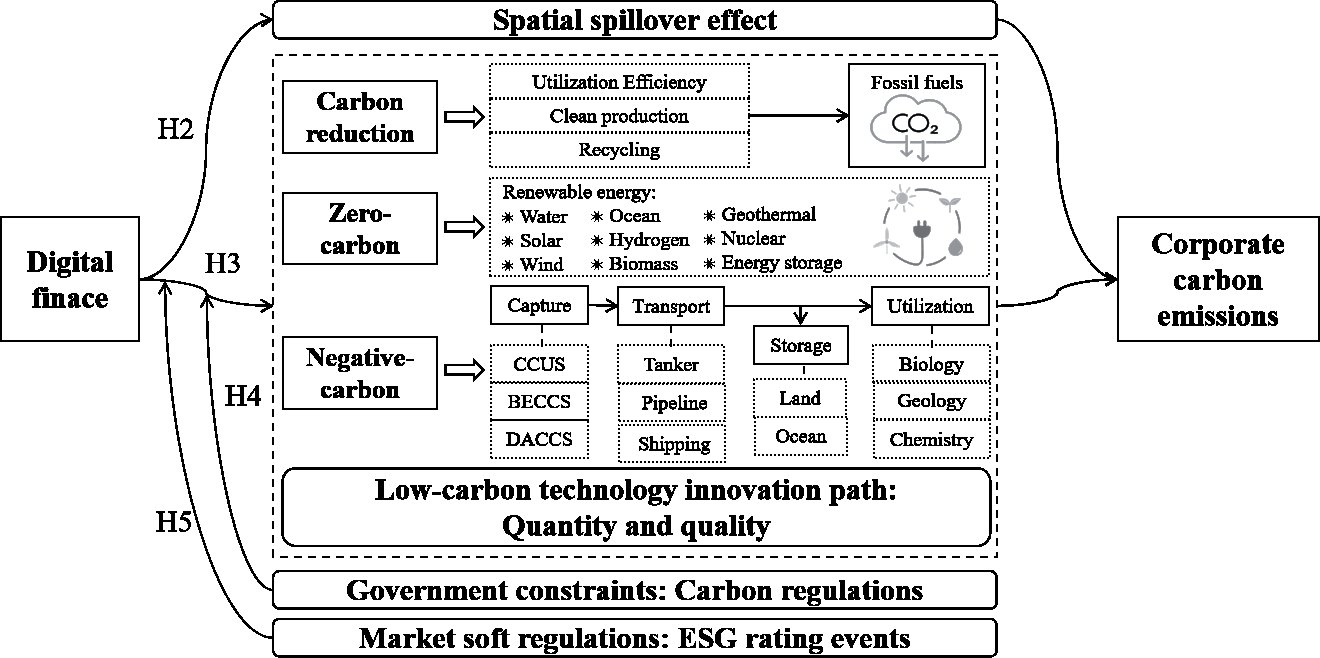
Low-carbon technologies are the core technologies closely related to corporate carbon emission reduction. According to their mechanisms, low-carbon technologies can be categorized into three types: carbon reduction, zero-carbon, and negative-carbon technologies. Carbon-reduction technologies, including the low-carbon utilization, clean development, and recycling of fossil fuels, belong to the category of carbon technologies with the widest application. Zero-carbon technologies refer to renewable clean energy technologies, including the development of new hydroelectric, solar, marine, wind, and nuclear energy technologies for zero-carbon power generation, as well as the development of zero-carbon hydrogen production and energy storage technologies. Negative-carbon technologies refer to the capture, transport, storage, and utilization of carbon dioxide, aiming to control carbon emissions at the final stage [40]. The carbon-removal effects of the latter two types of technologies are more significant, necessitating that enterprises possess strong innovation capabilities and bear higher risks of failure. Currently, research and development achievements for these technologies are relatively weak.
Overall, three types of carbon technologies all belong to green innovation, with a focus on improving environmental benefits. Compared to conventional innovations, they have greater difficulty and risk, requiring greater external financing support [41]. In traditional finance, high risk means higher financing constraints. However, DF adopts a more flexible evaluation approach, considering a diverse range of information, including corporate governance, operations, transactions, and credit, rather than limiting the assessment to company financial reports [42]. It means that DF is less likely to reject funding requests for low-carbon innovation solely because of its high uncertainty. Additionally, ample funding sources enable DF to allow more firms to access financing and fully stimulate its enthusiasm for low-carbon innovation. DF can also follow the Schumpeterian innovation mechanism, increasing the likelihood of firms engaging in low-carbon technology innovation through the cost-saving effects on financing [43].
As for innovation quality, DF can utilize an intelligent information platform to review and screen green projects before financing [44], guiding funds more precisely toward high-quality innovation activities. It can also avoid redundant support for similar innovation projects, preventing unnecessary resource waste. After the investment, the DF platform can also perform real-time monitoring of the flow of green funds, preventing enterprises from using financing funds for fake low-carbon innovations, identifying anomalies in innovation activities, eliminating potential “rent-seeking” behaviors [45], and promoting the improvement of corporate low-carbon technology quality. Consequently, the hypotheses are proposed as follows.
Hypothesis 3a. DF can reduce CCE by increasing low-carbon technology innovation quantity.
Hypothesis 3b. DF can reduce CCE by improving low-carbon technology innovation quality.
Moderating Effects of Carbon Regulations and Corporate ESG Rating Events
Low-carbon technologies have externalities in both knowledge and environmental aspects. For enterprises pursuing economic benefits, it is difficult to have sufficient motivation for low-carbon technology innovation in the absence of external pressure. Therefore, corporate low-carbon technology innovation requires the guidance of carbon regulations. Carbon regulations refer to policy measures adopted by the government to compel or incentivize market entities to undergo low-carbon transitions, such as enacting relevant laws and regulations, strengthening administrative law enforcement, levying emission fees, and establishing carbon trading markets [46]. From the perspective of funding supply, under the guidance of low-carbon policies, DF will appropriately shift its investment focus towards green and low-carbon projects, which is beneficial for improving both the quantity and quality of corporate low-carbon technologies. Second, most measures of carbon regulations are mandatory, aimed at constraining CCE through the setting of emission standards. To meet compliance standards, enterprises would proactively incorporate low-carbon innovation into corporate strategies [47]. According to the Porter Hypothesis, carbon regulations can trigger an innovation offset effect. Enterprises would proactively increase the quantity and quality of low-carbon innovation, hoping to gain excess profits or achieve compliance goals through technological upgrades. In addition to mandatory measures, carbon regulations also employ market-based approaches such as low-carbon subsidies and carbon trading mechanisms to internalize the dual externalities of low-carbon innovation. These approaches could stimulate corporate motivation for low-carbon innovation and improve innovation quality through tangible economic benefits. Thus, it can be inferred that under reasonable carbon regulations, the low-carbon innovation effect of DF can be further strengthened. Relevant hypotheses are proposed as follows.
Hypothesis 4a. Government carbon regulations can positively moderate the low-carbon technology innovation quantity path of DF.
Hypothesis 4b. Government carbon regulations can positively moderate the low-carbon technology innovation quality path of DF.
Corporate ESG ratings refer to the evaluation of companies by third-party institutions in the areas of environmental, social, and governance performance. With the national focus and support on carbon neutrality actions, the green attributes of enterprises have become a crucial basis for investors’ decision-making. ESG ratings can disclose diverse green information, such as energy consumption, environmental protection, and social responsibility. On the one hand, ESG information provides financial institutions with a benchmark for assessing investment risks and predicting expected returns, directly impacting a company’s external financing. On the other hand, ESG ratings can convey green signals to corporate stakeholders and consumers, influencing the shaping of corporate image and the expansion of corporate market share [48]. Thus, according to the market pressure theory, when faced with ESG rating events, enterprises will be more proactive in utilizing the advantages brought by DF to develop green technologies and avoid the loss of resources that comes from low ESG scores [49]. However, unlike mandatory government carbon regulations, corporate ESG ratings can only influence low-carbon innovation through market mechanisms. Facing softer market supervision, enterprises may easily engage in speculative behavior. Since the ESG rating is an annual indicator with a shorter evaluation cycle, enterprises may prefer innovation models with obvious promotion effects and low R&D costs and focus on the quantity growth of low-carbon technologies while neglecting the improvement of quality [50]. Thus, the hypotheses are proposed as follows.
Hypothesis 5a. Corporate ESG rating events can positively moderate the low-carbon technology innovation quantity path of DF.
Hypothesis 5b. Corporate ESG rating events cannot moderate the low-carbon technology innovation quality path of DF.
Fig. 1 shows the theoretical framework and hypotheses development of this study.
Material and Methods
Data Sources
This study takes Chinese A-share listed companies from 2011 to 2021 as the research sample and processes the enterprise data as follows to ensure the reliability of the sample: (1) Exclude listed companies in the financial and real estate industries; (2) Exclude listed companies which are treated specially (ST, *ST or PT); (3) Exclude companies that have been delisted during the sample period; (4) Exclude company samples with severe data deficiencies. The digital finance index data is collected from the Institute of Digital Finance at Peking University. Other data sources include the CSMAR database, company annual reports, corporate social responsibility reports, corporate environmental reports, and the incoPat database.
Model Specification
To explore the impact of DF on CCE and test Hypothesis 1, a baseline econometric model is formulated as follows:
where i, j, r and t denote firm, city, industry, and year, respectively. CCEijrt denotes the carbon emissions of firm i in city j in year t. DFjt represents the digital financial inclusion index of the city j in year t. Controlijrt refers to a set of control variables. μt and νr refer to year and industry fixed effects (FE), respectively, and εijrt is a randomized disturbance term. The coefficient α1 is the core focus of this study, as it reflects the effect of DF on CCE.
Variables
Explained Variable
Corporate carbon emissions (CCE). This study adopts the natural logarithm of total carbon emissions to measure the explained variable. The total carbon emissions of firms include emissions resulting from the combustion and fugitive sources, production processes, wastewater treatment, land use changes, and incineration of solid waste. These data can be obtained from the annual reports, social responsibility reports, and environmental reports disclosed by the enterprises. For enterprises that do not directly disclose their annual carbon emissions, we calculate the combustion and fugitive emissions primarily based on the “Guidelines for Corporate Greenhouse Gas Emissions Accounting and Reporting” issued by the National Development and Reform Commission.
Explanatory Variable
Digital Finance (DF). This study employs the city-level digital financial inclusion index constructed by the Institute of Digital Finance at Peking University as a proxy variable for the core explanatory variable [51]. Specifically, the index can be divided into three dimensions: breadth of coverage (DFC), depth of usage (DFU), and degree of digitalization (DFD). The breadth of coverage indicator indicates the penetration of digital payment accounts; the depth of usage indicator assesses the actual use of digital financial services such as payments, credit, insurance, and investments; the degree of digitalization indicator evaluates the convenience, cost-effectiveness, and creditworthiness of digital financial services.
Table 1.
Baseline regression results.
Control Variables
Considering that certain characteristics of firms may influence the empirical results, this research controls the following variables based on existing literature [19, 23]: (1) Firm age (Age), measured by the logarithm of the number of years since the company was founded;
(2) Firm size (Size), measured by the logarithm of total assets; (3) Asset-liability ratio (Lev), expressed as the ratio of gross liabilities to total assets; (4) Return on total assets (Roa), expressed as the ratio of net margin to the average balance of total assets; (5) Firm growth (Growth), measured by the increase rate of business revenue; (6) Tobin’s Q value (TQ), measured by the ratio of market value to the replacement cost of total assets;
(7) The proportion of independent directors (Indep), measured by the ratio of independent directors to the total number of board members; (8) The shareholding ratio of the top ten shareholders (OC), measured by the ratio of the number of shares held by the top 10 shareholders to the total shares; (9) Cash flow ratio (Cash), measured by the ratio of net cash flows from operating activities to total assets; (10) Equity check and balance degree (Balance), expressed as the ratio of the aggregate shareholding of the second to tenth largest shareholders to that of the first largest shareholder.
Results and Discussion
Benchmark Results
The baseline regression results of equation (1) are shown in Table 1, which presents the impact of DF on CCE. The results in column (1) show that, after adding control variables and fixed effects into the regression model, the estimated coefficient of DF is -0.1424, which is statistically significant at the 1% level, indicating that DF can effectively reduce CCE and Hypothesis 1 is confirmed. This study further explores the impact of three digital financial dimension indices on CCE, with the results shown in columns (2) to (4). The results indicate that breadth of coverage (DFC), depth of usage (DFU), and degree of digitalization (DFD) can all reduce CCE. Specifically, the estimated coefficients of DFC, DFU and DFD are -0.1227, -0.0753, and -0.1227, respectively, indicating that the micro-level carbon reduction effects of breadth of coverage and depth of usage are superior to those of degree of digitalization. A possible explanation is that an increase in the breadth of DF coverage may attract more customer funds to provide resource support for corporate carbon reduction efforts [17]. An increase in the degree of digitalization can more effectively simplify the procedures for handling corporate financial affairs, which can enhance residents’ willingness to use digital financial services and directly reduce carbon emissions associated with financial transactions.
Endogeneity and Robustness Checks
Instrumental Variables (IV) Method
Considering factors such as omitted variables and bidirectional causality may lead to endogeneity issues, we refer to existing research [20] and select the first lag of the digital inclusive finance index and city internet penetration rate as instrumental variables, and conduct endogeneity tests based on two-stage least squares (2SLS) method, with the results presented in columns (1) to (4) of Table 2. The Kleibergen-Paap rk LM Value passes the significance test, and the Kleibergen-Paap rk Wald F Value is 102.51, which exceeds the critical value of 16.38, indicating that the instrumental variables selected in this study do not suffer from identification problems or weak instrument issues. According to the results in columns (2) and (4), the impact of DF on CCE still remains significantly negative when the instrumental variables are taken into account.
Table 2.
Results of the IV method and the system GMM method.
Table 3.
Other robustness check results.
System Generalized Method of Moments (GMM) Method
To further address endogeneity issues and consider the dynamic effects of CCE, this study incorporates the lagged one-period CCE into the model and applies the system GMM model for effect estimation. The results in column (5) of Table 2 show that the coefficient of DF remains significantly negative at the 1% level, confirming the reliability of the research findings in this study.
Other Robustness Tests
(1) Replacing the dependent variable. Replace the corporate carbon emission indicator with the corporate carbon intensity (CEI) indicator for regression analysis. The corporate carbon intensity indicator is calculated by dividing the company’s carbon dioxide emissions by its main business revenue. (2) Replacing the estimation model. In this section, we first add the city-fixed effect to the model to avoid interference from some city-specific economic factors and then replace the industry-fixed effect with an individual-fixed effect. (3) Winsorizing. Perform a 1% bilateral winsorizing on the independent variable, dependent variable, and all control variables. Columns (1)-(4) of Table 3 show the results of the above tests, and the sign and significance of the coefficients of DF remain unchanged, further confirming the robustness of the results.
Heterogeneity Analysis
Industry Heterogeneity
Due to the different nature of production activities across industries, firms in different sectors exhibit variations in their resource requirements, energy demands, and waste emissions, which may affect the manifestation of DF’s micro-level carbon reduction effects. Manufacturing enterprises primarily engage in the production of industrial and consumer goods, consuming a large amount of fossil fuels and facing higher pressure from government-imposed emission reduction targets. Hence, this study categorizes the sample into manufacturing and non-manufacturing enterprises according to the “National Economic Industry Classification” published by the National Bureau of Statistics in China for heterogeneity analysis. The regression results are shown in columns (1) and (2) of Table 4. The data show that DF can significantly reduce carbon emissions in manufacturing enterprises, with the coefficient of DF being -0.1540, which is significantly negative at the 1% level. In non-manufacturing enterprises, however, the coefficient of DF is not significant, indicating that DF does not yet affect the carbon emissions of non-manufacturing enterprises. A possible reason is that manufacturing enterprises want to avoid being fined for excessive carbon emissions. They are more proactive in seizing the green financing opportunities brought about by the thriving development of DF and utilizing these funds for the research and application of low-carbon technologies to reinforce the carbon reduction effects of DF [52].
Heterogeneity Analysis of Executive Green Cognition
According to strategic cognition theory, the occurrence of corporate low-carbon behaviors is not only driven by external environmental pressures but also closely related to executive cognition of resources and the environment. Therefore, this study divides the sample into high green cognition and low green cognition groups based on the median of executive green cognition. The acquisition of the executive green cognition indicator is based on text analysis methods, which process word frequency data of twenty environmental-related terms such as environmental protection, energy conservation, emissions reduction, and low carbon that appear in corporate annual reports. As seen from columns (3) and (4) in Table 4, the carbon reduction effect of DF is more pronounced for firms with higher executive green cognition. This may be due to the fact that firms with higher executive green cognition tend to take on environmental responsibilities more proactively and utilize the resources provided by DF for green and low-carbon transformations.
Table 4.
Heterogeneity analysis results.
Spatial Spillover Effect Analysis
To further explore whether DF has spatial spillover effects on the carbon emissions of enterprises in neighboring cities and test Hypothesis 2, this section establishes a spatial econometric model. It should be noted that the data required for this model must be regional data. Therefore, in this section, the relevant enterprise-level data will be averaged by the city to which each enterprise belongs, serving as the corresponding enterprise data for that city. After conducting Moran’s I index, LM, LR, Hausman, and Wald tests, the spatial Durbin model was chosen to test the spatial spillover effects of DF [53], with the specific model specification as follows:
where j and k denote city j and city k, respectively. CCEjt denotes the carbon emissions of firms in the city j in year t. The meanings of DFjt, Controljt and εjt are consistent with those in Equation (1). Wjk represents the spatial weight matrix, which is expressed by the economic, geographic nested matrix calculated based on the geographic latitude, longitude, and GDP of cities. μt and σj refer to year and city fixed effects.
Since the regression coefficients in spatial econometric models can only roughly indicate the relationships between variables, this study uses the partial differentiation method to decompose the spatial effects, with the results presented in Table 5. From the results of direct and indirect effects, the coefficients of DF are both significantly negative, indicating that not only does the development of local DF have a restraining effect on CCE, but the development of DF in neighboring cities also suppresses carbon emissions from enterprises in the local city. It suggests that the micro-level carbon reduction effect of DF exhibits clear spatial spillover characteristics, confirming Hypothesis 2.
Table 5.
Spatial effect decomposition results.
| Variables | Direct effect | Indirect effect | Total effect |
|---|---|---|---|
| DF | -0.1591*** (0.0372) | -0.1980** (0.1015) | -0.3571*** (0.1071) |
| Controls | YES | YES | YES |
| Year FE | YES | YES | YES |
| City FE | YES | YES | YES |
| N | 2475 | 2475 | 2475 |
Table 6.
Path analysis results for the quantity and quality of low-carbon technology innovation.
Path Analysis of Low-carbon Technology Innovation
In the baseline regression, DF has been proven to reduce CCE effectively; however, the underlying mechanisms remain unclear and require further exploration. Therefore, this section, based on the previous theoretical analysis, explores the intrinsic impact pathways through which DF affects CCE from the perspective of low-carbon technology innovation.
To examine the specific mode of action for the pathway of low-carbon technology innovation and test Hypotheses 3a and 3b, this study sets up the following mechanism analysis model referring to Preacher and Kelley [54].
where Mijrt represents the path variable, the meanings of the other variables are consistent with those in Equation (1). The coefficients c1 and d2 are the focus of this section. If the coefficient c1 is significantly positive, it indicates that DF can facilitate the path variable. If the coefficient d2 is significantly negative, it suggests that the path variable can suppress CCE.
This paper selects the quantity and quality of low-carbon technology innovation as two key pathway variables. In terms of the quantity indicator (LCPT), this study, based on the “Patent Classification System for Green and Low-carbon Technologies” established by the National Intellectual Property Administration, uses international patent classification (IPC) numbers for matching, as well as keyword filtering of patent titles and abstracts, to screen and calculate the annual number of low-carbon patent applications of each company from the incoPat database. The quality of low-carbon technology innovation (PIR) is expressed as the ratio of the number of enterprise low-carbon invention patents to the total number of low-carbon patents [55].
The results of the path analysis are shown in Table 6. From the results in columns (1) and (3), the coefficients of DF are significantly positive at the 1% level, indicating that DF can simultaneously enhance the quantity and quality of corporate low-carbon technology innovation. Meanwhile, columns (2) and (4) show that the coefficients of LCPT and PIR are -0.1389 and -0.1383 significantly at the 1% level, respectively, indicating that improvements in the quantity and quality of low-carbon technology innovation can effectively suppress CCE; thus, Hypotheses 3a and 3b are confirmed.
Furthermore, this study provides an in-depth interpretation of the low-carbon innovation mechanism from the perspectives of technical difficulty and technology category. From the perspective of technical difficulty, we are following the research of Lian et al. [56], categorizing low-carbon technology innovation into substantive and strategic innovation. Substantive innovation (LCPI) is expressed by the logarithm of low-carbon invention patent quantity, while strategic innovation (LCPU) is expressed by the logarithm of low-carbon utility model patent quantity. The results in columns (1) and (2) of Table 7 demonstrate that DF can effectively stimulate substantive innovation but not play a significant role in strategic innovation. A possible reason is that DF, as a combination of digital technology and financial services, can more accurately assess corporate credit and select high-quality, low-carbon innovation projects, thereby avoiding funding being directed toward strategic innovation projects.
From the perspective of technology category, this study categorizes low-carbon technologies based on their carbon reduction mechanisms into three categories: carbon reduction (RCP), zero-carbon (ZCP), and negative-carbon technologies (NCP). We use the logarithm of the corresponding patent quantities to measure the low-carbon technology innovation intensity of each category. The identification of three types of patents is based on the “Patent Classification System for Green and Low-carbon Technologies” issued by the National Intellectual Property Administration. The results in columns (3)-(5) of Table 7 indicate that DF can stimulate corporate carbon reduction technology innovation, but it has not yet had a positive impact on zero-carbon and negative-carbon technology innovation. The occurrence of this phenomenon may be related to the relatively weak foundation of zero-carbon and negative-carbon technology research in China. Enterprises are more willing to use the resources brought by DF for lower-risk carbon reduction technology research and development to achieve the goal of low-carbon transition.
Table 7.
The impact of DF on substantive and strategic low-carbon innovation.
Moderating Factors Exploration of Low-carbon Innovation Path
In the theoretical analysis section, this study proposes that government carbon regulation and corporate ESG rating events may have moderation effects on the low-carbon innovation pathway of DF. To verify Hypotheses 4a, 4b, 5a, and 5b, this section establishes the following moderation effect model for testing [57]:
where Fijrt represents the moderation variable, the meanings of the other variables are consistent with those in Equation (1). The coefficients e1 and e3 are the focus of this section. If coefficients e1 and e3 are both significant, and their signs are consistent, indicating that Fijrt can exert a positive moderating effect; if their signs are opposite, it suggests that Fijrt exerts a negative moderating effect.
Government Carbon Regulation
This study follows the approach of Chen et al. [58] and uses the frequency of terms related to “low-carbon” in local government reports to measure government carbon regulation (LCGR). The interaction term between LCGR and DF is included in the model to test the moderation effect of government carbon regulation on corporate low-carbon innovation, with the results shown in columns (1) and (2) of Table 8. Observing the coefficients of the interaction term, we find that government carbon regulation can positively moderate the impact of DF on the quantity and quality of corporate low-carbon innovation, confirming Hypotheses 4a and 4b. In summary, the “punishment rules” or “market benefit mechanisms” established during the implementation of government regulations can effectively encourage firms to utilize DF for high-quality technological innovation. This leads to tangible carbon reduction outcomes that help firms avoid administrative penalties or generate benefits from the carbon market.
Corporate ESG Rating Events
Corporate ESG ratings can affect investors’ perception of the corporate image and investment decisions. Under the pressure of ESG rating events, companies are more likely to actively engage in green innovation activities to gain market trust. Thus, referring to Tan and Zhu [59], the ESG rating event variable (ESGR) is assigned to 0 or 1 according to whether SynTao Green Finance published the company’s ESG rating index in that year. The results of the moderation effect based on equation (5) are shown in columns (3) and (4) of Table 8. In column (3), the coefficient of ESGR×DF is 0.2842 and is significantly positive at the 1% level, indicating that ESG rating events positively moderate the pathway of low-carbon technology innovation quantity; thus, Hypothesis 5a is confirmed. In column (4), however, the coefficient of ESGR×DF does not pass the significance test, suggesting that ESG rating events cannot effectively moderate the pathway of low-carbon technology innovation quality; thus, Hypothesis 5b is confirmed.
Table 8.
Moderating factors analysis results of low-carbon innovation path.
Conclusions
With the innovation and integration of digital technologies in the financial field, the increasingly diverse digital financial products provide more possibilities and viable paths for enterprises to achieve low-carbon transitions. This study focuses on A-share listed companies in China from 2011 to 2021 and employs fixed-effect, spatial Durbin, mediating effect, and moderating effect models to investigate the actual impact, spatial effects, and mechanisms of DF on CCE.
The main research findings are as follows. (1) DF can significantly suppress CCE. This conclusion remains robust after a series of endogeneity treatments and robustness checks. (2) For the three dimensions of DF, breadth of coverage, depth of usage, and degree of digitalization can all effectively reduce CCE, while the impact of the depth of usage dimension is weaker compared to the other two dimensions. (3) DF can exert a spatial spillover effect to suppress CCE in neighboring cities. (4) Low-carbon technology innovation is an important pathway through which DF reduces CCE, specifically by simultaneously increasing the quantity and quality of low-carbon patents to promote corporate low-carbon transitions. (5) Based on the research about the difficulty and types of low-carbon technologies, we find that DF effectively stimulates companies to pursue substantive innovation rather than strategic innovation, promoting carbon reduction technology innovation over zero-carbon or negative-carbon technologies. (6) From the perspective of government hard constraints and market soft regulations, government carbon regulations can positively moderate the low-carbon innovation quantity and quality pathways of DF. In contrast, corporate ESG rating events can only positively moderate the quantity path rather than the quality path.
Based on the aforementioned research conclusions, this study proposes the following policy recommendations. (1) Continue to intensify the construction of digital infrastructure, enhance communication and cooperation among regions, and jointly accelerate the completion of the digital financial product system. The development of DF should not only focus on expanding coverage but also emphasize enhancing the depth of usage, vigorously developing digital green credit services, and innovating carbon finance products to provide low-cost, high-efficiency financial support for corporate low-carbon transitions. (2) Flexibly utilize the intelligent decision-making functions of DF. On the one hand, build quality evaluation and risk control models for low-carbon projects to guide funds more precisely toward high-quality low-carbon innovation projects. On the other hand, set investment preferences to guide funds toward zero-carbon and negative technologies with better carbon benefits and stronger disruptive potential to enhance China’s international competitiveness. (3) Reasonably enhance the government’s low-carbon regulatory standards to provide a great green institutional environment for strengthening the micro-level carbon emission reduction effects of DF. On the one hand, the government needs to strengthen imperative regulations and increase penalties for high-carbon behaviors, using higher non-compliance costs to drive enterprises to actively leverage DF for low-carbon innovation. On the other hand, the government can further improve market-based regulations such as carbon emissions trading and carbon taxes, using market mechanisms to guide digital financial resources toward low-carbon and environmentally friendly enterprises, thereby injecting momentum into achieving the quantity and quality improvements in low-carbon technologies.
(4) Actively leverage the role of corporate ESG ratings in moderating the low-carbon innovation pathways of DF. On the one hand, accelerate the establishment of standardized ESG rating mechanisms and unified evaluation criteria, pressuring enterprises to fulfill their environmental and social responsibilities. On the other hand, refine the details of ESG evaluations, fully exploring indicators that can scientifically assess the true level and long-term value of enterprises.
This study has several limitations. First, due to data availability issues, the research subjects are limited to listed companies. However, the inclusive nature of DF may have more beneficial impacts on small and medium-sized enterprises (SMEs) facing stronger financing constraints, significantly improving their access to financing. Therefore, future research could attempt to build a dataset for SMEs to further study and compare the differences in carbon emission reduction effects caused by DF across different types of enterprises. Second, although China’s carbon emission activities and DF development are highly representative, research based on samples from multiple global economies still holds significant practical value and can provide more information about the green effect of DF. Third, this study used a relatively general method to measure the intensity of carbon regulations. Future research could attempt to categorize and measure carbon regulations, delving deeper into how different types of carbon regulations affect the low-carbon innovation path of DF, which would help in providing more precise recommendations for government decision-making.

