

Introduction
Worldwide warming has become a worldwide concern that affects human life and sustainable development [1]. Among these, greenhouse gas emissions caused by human activities are the primary cause of present-day global warming [2]. The global nature of the climate change problem has drawn the attention of all countries worldwide, and in recent years, it has been through the United Nations Framework Convention on Climate Change (UNFCCC), the Paris Agreement, and other channels to jointly discuss action programs to address global climate change. Countries combat climate change by reducing fossil fuel consumption [3], developing wind and solar energy [4], and advancing scientific innovation [5]. The aim is to cut carbon emissions, enhance environmental performance, and protect the planet.
The Chinese government, as the world’s largest developing country, has implemented measures to improve environmental performance, emphasizing the integration of economic growth with ecological conservation. In 2021, China’s energy consumption, according to the BP Statistical Yearbook of World Energy 2022, comprised 26.5% of global consumption, ranking first worldwide. However, this high energy consumption and pollution have led to environmental issues, including resource scarcity, pollution, and overcapacity [6,7]. This economic approach impedes environmental performance and fosters unsustainable growth. Consequently, a primary concern for researchers is minimizing carbon emissions and enhancing environmental performance [8,9].
Recognizing finance as the cornerstone of economic growth, the Chinese government prioritizes leveraging financial tools for carbon emission reduction and fostering net-zero economic growth [10]. However, traditional finance in China encounters challenges, including weak transmission mechanisms, insufficient development, and low resource allocation efficiency, impeding businesses’ adoption of green technology [11]. Additionally, the profit-oriented focus of financial institutions and the ecological unawareness of local officials pursuing economic growth hinder China’s path to sustainable economic development [12,13]. Digital finance, amalgamating financial services and technology, offers decentralized and disintermediated features that enhance the financial system’s reach. It addresses credit constraints in small and medium-sized enterprises (SMEs), resolves financial challenges in equipment upgrades and technological advancements, expands financial product offerings, effectively mitigates financial exclusion, and exhibits a potent opportunistic function [14]. Considering these aspects, it is worth exploring whether China can enhance its environmental performance through a robust promotion of digital finance.
The regional economy and digital finance development are closely linked. Digital finance may foster regional economic growth, establishing a foundation for its own expansion. Existing literature suggests that digital finance enhances environmental performance and reduces carbon emissions [15,16]. However, these analyses overlook intercity spatio-temporal heterogeneity, focusing solely on linear relationships between explanatory and interpreted variables. There is ample scope to explore the impact of digital finance on environmental performance. To examine the nonlinear connection, this article introduces a partial linear functional coefficient (PLFC).
This study employs science and technology innovations to investigate the functional mechanism linking digital finance to environmental performance [17,18]. Digital finance facilitates funding for startups and creative ventures, allowing innovators to secure resources through mechanisms like crowdsourcing, venture capital, and digital currencies. The industry accumulates valuable data for analyzing market trends, consumer demands, and risk management. Innovators in science and technology leverage this data to refine their products and services to meet market demands. Practices such as smart investments, online financing, and digital banking contribute to building the digital economy, reducing energy consumption, and enhancing environmental performance. Simultaneously, the development of digital finance constitutes a novel financial business model, inherently a financial innovation [19]. Emerging economic sectors like rural e-commerce and the sharing economy depend on digital technology, indicating that digital finance’s evolution drives the development of new economic sectors and enhances overall economic performance. In this context, the paper focuses on assessing the impact of digital finance on environmental performance under heterogeneous conditions, utilizing prefecture-level panel data from 2011 to 2019. The goal is to offer decision-making insights for advancing digital finance development in China and achieving the ‘double carbon’ goal.
The following are the differences between this work and the current literature: (i) This paper employs a partial linear functional-coefficient (PLFC) model, which relaxes the linearity assumptions previously imposed on the form of the function, reducing the risk of model misspecification and biased estimation, and investigates the effect of heterogeneity in regional science and technology innovations, providing new evidence for the nonlinear relationship between digital finance and environmental performance. (ii) This research is based on prefecture and municipal-level data, which can elucidate the link between digital finance and environmental performance on a more nuanced geographical scale than province-level data. (iii) In order to examine the link between the variables, this article integrates digital finance, science and technology innovation, and environmental performance into a single research system, concentrating on the moderating role of science and technology innovation.
The remaining portions of the essay are structured as follows: The review of previous writing is in the second part. The methods and statistics are presented in the third part. The empirical analysis and findings are in Part IV. The policy proposals and findings are in Part V.
Literature Review
DF and EP
The factors affecting environmental performance are studied by scholars through an analysis of the literature, with a particular focus on technological advancement [20], industrial structure [21], urbanization [22], energy transition [23], carbon trading market [24], environmental regulation. Undoubtedly, a lot of academic research has been done on the intensity of carbon emissions, but very little of it has examined the impact of digital finance on carbon intensity. The question of whether digital finance may become yet another crucial element in lowering carbon intensity can be researched, given the quick expansion of the industry.
In theory, digital finance can have a direct and indirect influence on environmental performance. In terms of direct effects, digital finance has the potential to decarbonize financial services by leveraging digital technology, artificial intelligence, cloud computing, and other technical tools to enhance conventional inclusive finance [25]. For financial institutions, digital finance creates a platform for financial product suppliers and demanders through online services, resolves the time and space constraints of traditional financial offline services, and increases the rate of financial capital circulation. This reduces energy consumption in the process of financial services and aids in the realization of the ‘greening’ and ‘decarbonization ‘ of financial services [26]. Digital finance disrupts the old business model by constructing mobile payment systems like Alipay, WeChat, and JD Finance, which can cut energy usage and hence carbon emissions [27,28]. Hypothesis 1: Digital finance has a direct positive impact on environmental performance.
In terms of indirect effects, digital finance can affect environmental performance indirectly through processes such as technical innovation and industrial structure upgrading. Finance, according to Schumpeter’s theory of innovation, plays an important role in promoting innovation, and innovative activities face financing constraints due to high risk and sunk costs, particularly in the long-tail market, which is dominated by demand groups of small and medium-sized private enterprises [29]. The popular market located at the head of the normal curve will be surpassed by the tail non-popular market placed at the two ends of the normal curve due to the cumulative market size, according to the long-tail market hypothesis. The traditional financial service model frequently ignores the financial requirements of companies in the long-tail of the industry in favor of catering to a select group of high-end clients [30]. The ‘law of two or eight’ financial service boundaries are broken by digital finance, which shifts the service border from high-end to long-tail market participants and relies on digital technology to provide a more diverse variety of financial goods and services. Digital financial institutions that rely on trading platforms have successfully addressed the issue of information asymmetry in the financial services industry, encouraged resource sharing, sped up the flow of innovative capital, encouraged enterprise technological innovation, and decreased carbon emissions. For instance, [31] think that the digital features of digital finance may support technical innovation, which in turn can enhance the efficiency of carbon emission reduction and eventually improve environmental performance. A similar research finding was reached by [32] as well. The study discovered that digital finance may foster technical advancement. Digital finance also functions as a helpful regulator of technological innovation and environmental control. Hypothesis 2a: Digital finance has a non-linear impact on environmental performance. Impacts
Df, STI, And EP
Modern civilization depends greatly on technical advancement and digital finance, and the two together have a significant influence on environmental performance. Innovation in science and technology may be financed through digital finance. Start-ups and technical innovation projects may be more readily funded through the financial technology platform, increasing the development and promotion of environmental protection technologies [33]. The use of blockchain technology can improve environmental monitoring and management by increasing the transparency and trustworthiness of data [34]. By tracking the production and use of sustainable energy, for instance, blockchain can guarantee that the energy’s source is identifiable and transparent. The economy has advanced along with the degree of scientific and technical innovation. Early in the development of science and technology, carbon dioxide emissions might rise because of a lack of innovation capacity and a slow uptake of eco-friendly products. More and more clean items will replace high-carbon products as innovation capacities advance and technologies become more advanced [35]. Consequently, carbon emissions will steadily decline until they reach zero, which leads to net zero economic growth.
Environmental fields have greatly benefited from scientific and technical advancement. Resource waste and environmental harm are anticipated to decrease because of green technology and sustainable innovation [36]. First of all, new instruments for managing and monitoring the environment have been made possible by advances in science and technology. Environmental monitoring has become more precise and real-time thanks to the deployment of sensor technology, big data analysis, cloud computing, and other technologies, assisting in the early detection and resolution of environmental problems [37]. Secondly, [38] points out that the growth of clean energy has been aided by the ongoing invention of renewable energy technology. The decreasing cost of solar and wind energy technologies has increased the competitiveness of alternative energy sources and decreased reliance on fossil fuels. Additionally, technological advancements in the areas of urban planning and intelligent transportation can enhance the urban environment by reducing air pollution and traffic congestion [39,40]. However, there are certain difficulties with technical advancement as well. For instance, e-waste recycling and treatment remain major worldwide issues that technological innovation must address in order to minimize environmental damage.
Hypothesis 2b: STI has a significant impact on digital finance and environmental performance.
Data and Models
Data
Explained variable: environmental performance. The intensity of carbon dioxide emissions is the substitute variable for environmental performance in this research. The following are the causes: First, the Chinese government’s efforts to save energy and reduce emissions include a focus on reducing CO2 and lowering carbon intensity. These are key indicators of improved environmental performance. Second, the primary subject of academic study is CO2, a pollution indicator that the world community pays close attention to and which poses a major danger to human life and sustainable economic growth.
Explanatory variable: digital finance. The digital finance index is used in this article to quantify digital finance. The database of Peking University’s Digital Finance Research Center serves as the data source. The depth of usage, the extent of digitalization, and the breadth of digital finance coverage are all factors in the digital finance index. The depth of use of digital finance primarily measures the application of the payment business, monetary fund business, credit business, insurance business, investment business, and credit business. The degree of financial digitization primarily examines the cost and convenience of using financial services. The breadth of digital financial coverage refers to electronic accounts such as Internet payment accounts. The vast data on trading accounts collected by Ant Financial is the foundation of the digital financial index, which has high dependability.
The degree of economic development (lngdp), population size (lnpop), industrial structure (lnpro), and gross industrial product (lnind) are chosen as the control variables in this study. GDP per capita, the total population of the city at the end of the year, the industrial structure (measured by the ratio of secondary industry to total industry), and the gross industrial product (measured by the actual gross urban product) are all used to determine the level of economic development.
Descriptive Statistics of the Data
This article’s study data is based on Chinese urban panel data from 2011 to 2019. The research used data from the China Yearbook of Urban Statistics, the China Yearbook of Environmental Statistics, and the China Yearbook of Science and Technology Statistics. Table 1 displays the descriptive statistical analysis of all variables. To mitigate the impact of outlier values, the article logarithms all variables while also lowering the quantiles of continuous variables below 1% and above 99%.
Modeling
The benchmark regression model is as follows:
In Eq. (1), lncdit denotes the environmental performance of city i in period t, lndfit denotes the degree of digital financial development of city i in period t, controlit denotes a series of control variables, γi denotes the individual control effect, δt denotes the time control effect, and εit denotes the random error term.
This paper suggests using the degree of scientific and technological innovation as threshold variables to further analyze the heterogeneity analysis of digital finance on environmental performance on the basis of Eq.(1). According to research conducted by [41] Zhang & Liu (2022), technical advancement has accelerated the growth and breadth of the usage of digital finance and improved the influence of this technology on environmental performance.
Mit refers to the two adjustment variables of scientific and technical innovation in Eq. (2). lndfit and Mit are the interaction terms of digital finance and regulatory variables in Eq. (3). If it is negative, it suggests that scientific and technical innovation can enhance environmental performance through digital finance. This article’s virtual variable is represented by Eq. (4). It is 1 if it is more than or equal to the mean; otherwise it is 0.
Models (1) through (4) investigate the linear effect of digital finance on environmental performance. The influence of digital finance on environmental performance may have nonlinear impacts. There are disparities in the amount of scientific and technical innovation at each city’s development level, which may result in different regression parameters and marginal increases for various cities. Therefore, since the linear function model cannot account for this effect link, a nonlinear model must be used. The PLFC model successfully simulates nonlinear interactions and spatial and temporal variability.
Eq. (5) covers the linear impact of control factors on environmental performance in one half, and the nonparametric impact of digital finance on environmental performance in the other.
Empirical Analysis
The article first performed the unit root test and the VIF test. The VIF test on these variables portray a mean value of 3.73, which is less than 10, showing that there is no multiple collinearity between the variables. The unit root test in Table 2, utilizing the Fisher technique, supports plausible results. Initial hypotheses concerning variable relationships are consistently disproven, indicating frequent horizontal alignment of the variables.
Table 1.
Descriptive Statistics.
Table 2.
Panel unit root test.
| Variable | Fisher | |
|---|---|---|
| Inverse chi-squared | P-value | |
| lndf | 1.07e+04*** | 0.000 |
| lninn | 1328.4694*** | 0.000 |
| lnpgdp | 1073.7176*** | 0.000 |
| lnpop | 721.4415*** | 0.000 |
| lnpro | 190.8520 *** | 0.000 |
| lnind | 3275.2186*** | 0.000 |
Benchmark Regression
The benchmark regression results are displayed in Table 3. The influence of digital finance on environmental performance is firstly examined in this research using a linear model based on equation (1). The findings in Column 1 of Table 3 demonstrate that digital finance has a negative effect coefficient on environmental performance, which is significant at the level of 1% and suggests that it can greatly enhance environmental performance. To be more precise, one is to offer green financial goods and services. Different green financial products and services, including green loans, green bonds, financing for renewable energy sources, and financing for environmental protection projects, can be introduced by digital financial institutions. The consumption of these goods and services lessens reliance on fossil fuels and lowers greenhouse gas emissions through funding sustainable development initiatives like solar, wind, and clean water treatment. The usage of digital financial technologies is the second. The fast advancement of digital technology has increased the efficiency and breadth of financial services. Digital payment and online banking, for example, can lessen the demand for paper bills, lowering the environmental load. Data analysis may be used by digital financial institutions to evaluate borrowers’ social and environmental hazards.This can assist them in avoiding lending to high-risk businesses or sectors, lowering the likelihood of environmental and social issues. Additionally, it aids financial organizations in reducing waste and more efficiently allocating cash. The foregoing analysis allows for the verification of hypothesis 1.
Moderating Effect of DF and EP
The second area of analysis is to determine whether the STI level has an influence on how well digital finance performs in terms of the environment. Table 4 shows the outcomes of the empirical study by including the amount of STI in equations (2) through (4), respectively. The findings of Model 1’s regression analysis after including the STI variable reveal that the coefficient of digital finance is negative and significant at the 10% level, which still suggests that it can significantly enhance environmental performance. Once more, hypothesis one is confirmed.
The regression results for the interaction of digital finance and science and technology innovation shown in model (2) show that the coefficient of the interaction term is negative and significant at the 10% level, indicating that digital finance can reduce carbon intensity through science and technology innovation, which can improve environmental performance. The digital form of digital finance offers financial products and services to science and technology-based businesses, which leads to scientific and technological innovation in businesses such as wind energy, solar energy, and other new energy industries, reduces fossil energy consumption, and ultimately improves environmental performance.
Table 3.
Fixed effect estimation results in the benchmark regression model.
Table 4.
Estimation results of models with heterogeneous effects.
Model (3) depicts the influence of digital finance on environmental performance at various STI levels. The coefficient of lndf*DI is shown to be considerably negative, implying that digital finance in places with higher than average levels of STI can improve environmental performance more. The higher the level of STI, the more advanced the economic development mode, the less reliance on conventional resources, the greater the digital economy, and the higher STI leads to improved environmental performance.
According to the findings of the aforementioned empirical investigation, the level of scientific and technical innovation is a significant moderating factor that influences the performance of digital finance and the environment. To further emphasize the crucial role of scientific and technical innovation in digital finance and improve environmental performance, the government should raise R&D spending and implement appropriate regulations for innovation in science and technology. It is proven that 2a is true.
PLFC Model
Changes in the quality, efficiency, and dynamism of economic development need the use of STI. STI may increase industrial efficiency, reduce resource consumption, and improve environmental performance in the context of the dual-carbon aim. However, the impact of the pandemic, as well as variances in economic growth among cities, have resulted in significant differences in the degree of science, technology, and innovation.
As a result, under the effects of various urban STI levels, the impact of digital finance on environmental performance is not the same. This research employs the partial linear function model (PLFC) to examine the heterogeneity and nonlinear influence of digital finance on environmental performance in order to better investigate the nonlinear impact of digital finance on environmental performance.
The estimation results of the nonparametric part g(Mit) are presented in the first section of the empirical regression results, and the linear regression results in the control variables are presented in the second section. The empirical results demonstrate that the significance and sign of the linear part of the regression results in Table 5 are similar to those of the conventional linear analysis in Table 3. In addition, the nonparametric functions in Fig. 2 provide something different from the traditional linear benchmark model.
The effect of the city’s STI level on digital finance and environmental performance is shown in Fig.1. The curve is quite flat and covers the value of zero when lnsti 14, indicating that it is not important in that period. It has two components. When lnsti > 14, digital finance has a marginal effect that is bigger than zero, indicating that higher levels of STI will encourage the improvement of environmental performance through digital finance. 2b’s prediction is confirmed.
The examination of actual evidence demonstrates that when STI is low, the influence of digital money on environmental performance is reduced. This inhibiting impact is increasingly diminished as the level of science and technology innovation rises. Digital finance has a major improving influence on environmental performance when the level of science and technology innovation is high. This could be so for a few reasons. First, STI can increase resource utilization efficiency. STI may improve the way things are made, which includes using resources more effectively, cutting down on waste, lowering energy use, and reducing emissions. Higher productivity can also cut down on resource use. STI can also support industrial technology. STI in the energy industry encourages the creation of technology for efficient energy generation, energy storage, and renewable energy. These innovations assist in lowering greenhouse gas emissions, improving air and water quality, and reducing reliance on fossil fuels. STI also works to advance a circular economy. Third, pollution is managed and controlled through advances in science and technology. More effective pollution control technologies and environmental monitoring techniques are made possible by scientific and technical advancements. This helps safeguard ecosystems and public health by reducing the harmful effects of emissions on the atmosphere, water bodies, and soil. In addition, high-tech, inventive cultures typically make more investments in knowledge and education. This may increase public awareness of environmental problems and encourage greener behavior.
Comparative Analysis of Geographic Locations of Different Cities Under the PLFC Model
The article chooses cities in the three northeastern provinces and eastern coastal cities (aside from coastal cities in the northeastern region) for comparison in order to further analyze the similarities and differences in the level of science and technology innovation in different regions of China. China’s heavy industry base is in the three northeastern provinces, and the heavy industry growth model has seriously harmed the urban environment. In contrast to the eastern coastal cities, the growth of digital banking has been modest and is currently confronting the challenge of industrial green transformation.
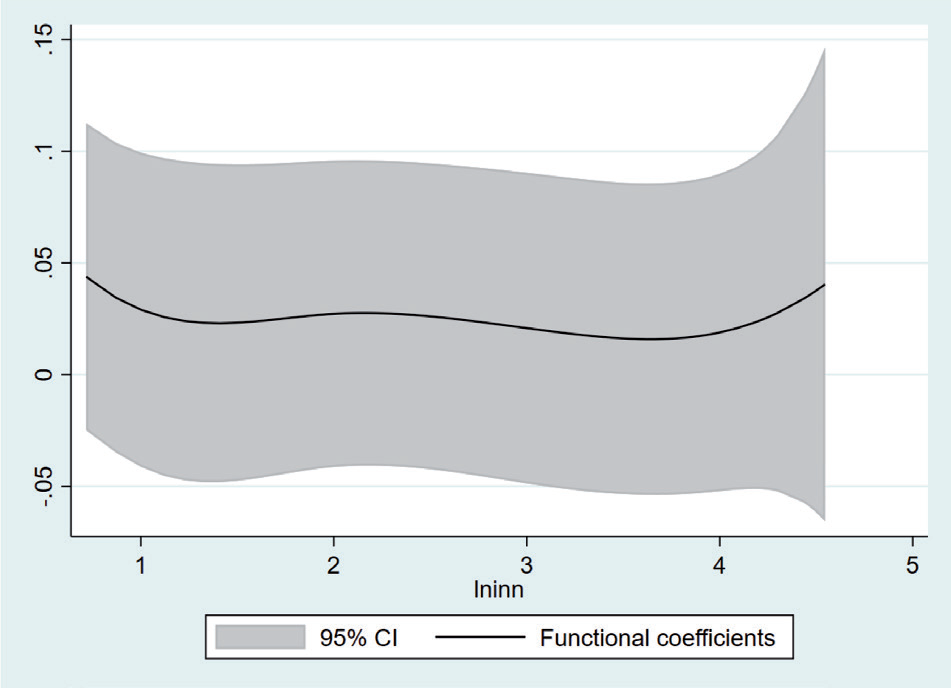
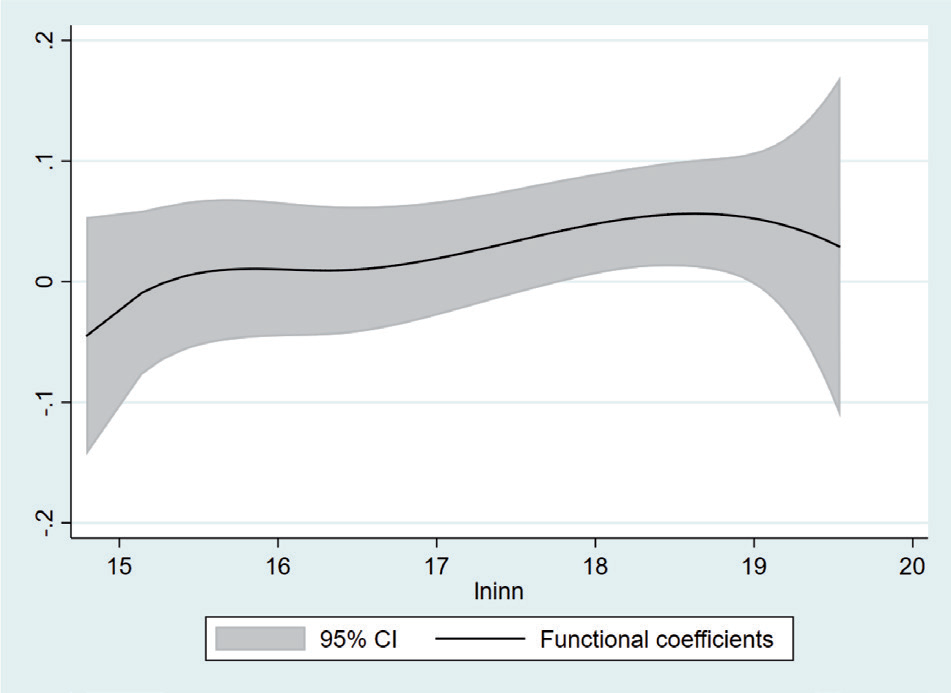
Fig.2 shows how the performance of digital finance and the environment in the three northeastern provinces is affected by the level of scientific and technological innovation. The chart shows that there is no correlation between the degree of science and technology innovation and digital finance’s ability to improve environmental performance. When compared to the influence of eastern coastal cities in Fig.3, this outcome is quite different.
Robust Tests of the PLFC Model
Table 6 displays the regression results, which show that digital finance has a significant impact on the improvement of environmental performance only when the level of science and technology is at a higher threshold. This is done in order to further verify the robustness of the PLFC model. The findings of the aforementioned robustness test are identical to those of the benchmark empirical regression test. As a consequence, we draw the conclusion that the PLFC model’s estimation results pass the robustness test. This further emphasizes that the growth of digital finance, which may be more beneficial in improving environmental performance, should enhance the degree of science and technology innovation.
Fig. 1.
Non-linear partial estimated results using the PLFC model Note: The curve in the figure shows the estimated function coefficient, and the shaded gray region expresses the 95% confidence interval.
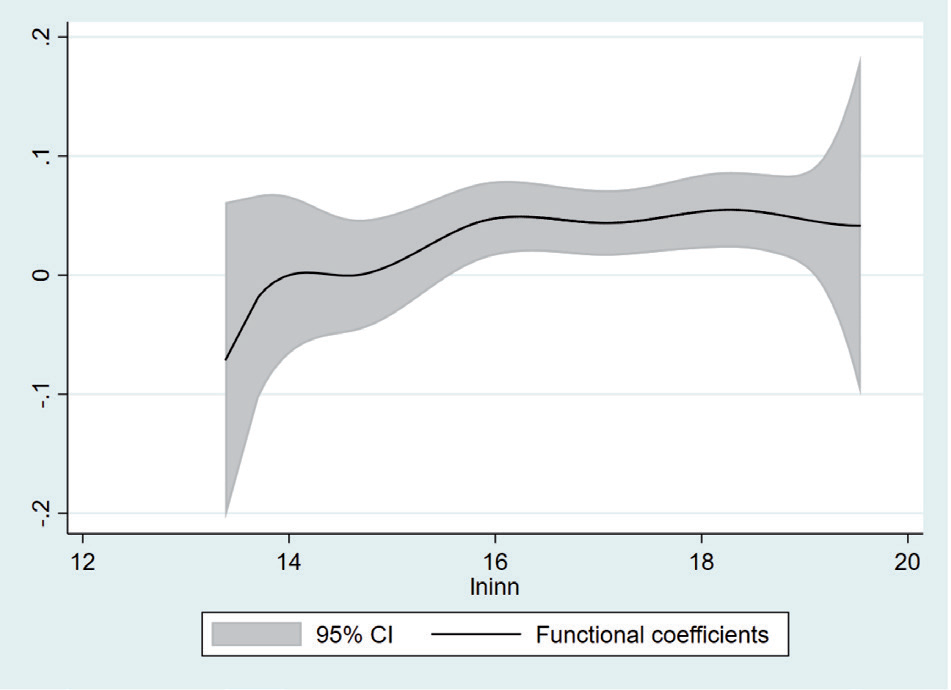
Fig. 2.
Non-linear partial estimated results using the PLFC model in cities of three northeastern provinces. Note: The curve in the figure shows the estimated function coefficient, and the shaded gray region expresses the 95% confidence interval.
Conclusion and Policy Recommendations
Sustainable urban development includes a key component called improving environmental performance. In order to do this, this research empirically examines the potential impact of digital finance on urban environmental performance using panel data from Chinese cities from 2011 to 2019 using fixed effects and partial linear function models (PLFC). It also looks at how the performance of urban environments and digital finance are related, as well as how much innovation there has been in science and technology. The spatio-temporal heterogeneity of cities in relation to their various geographic locations is also examined in this research.
The following are the paper’s conclusions: (i) Improving environmental performance requires the use of digital finance. It demonstrates that the ability of digital finance to minimize urban carbon intensity increases with the perfection of its development. (ii) Both linear and nonlinear analytic models demonstrate that the amount of scientific and technological innovation affects how well urban environments are performed through digital finance. Particularly, the more pronounced this moderating influence is, the higher the degree of science and technology innovation must rise to. (iii) Analysis of regional heterogeneity reveals the moderating effect of STI level. The influence of digital money on environmental effects is stronger in the coastal region than it is in the Northeast.
Based on the above findings, this paper makes the following policy recommendations:
(i) Create a sustainable program for the growth of digital finance. To foster digital finance development, especially products aiding environmental protection, the government should implement a sustainable program. Digital finance significantly enhances cities’ environmental performance. The policy aims to reduce carbon emissions, enhance environmental sustainability, and involve stakeholders like financial institutions
and tech firms. Implementing precise legislation and regulatory frameworks ensures the long-term viability and transparency of digital financial products. Compelling financial institutions and tech firms to disclose environmental performance data, including carbon emission reductions and sustainable investments, is crucial. Regulators may establish environmental performance requirements to assess digital financial products’ impact. Governments can support long-term technical progress in digital finance through incentives like tax breaks, R&D financing, and intellectual property protection. This encourages the continuous exploration of new digital financial instruments, promoting environmental benefits such as carbon emission reduction and increased resource efficiency. (ii) Creating a legal framework for STI and digital financial collaboration. Creating a legal framework for collaboration between STI and digital finance is crucial. The link between digital finance and urban environmental performance is influenced by STI levels. To enhance urban environmental performance and sustainability, the government should enact legislative measures optimizing the synergy between STI and digital finance. Improving STI infrastructure is vital; government funding can support the development of facilities like research centers, incubators, and technological hubs. These spaces can facilitate collaboration among startups, digital financial institutions, and technology enterprises, fostering innovative growth. Additionally, establishing technology transfer hubs enables the swift application of scientific innovations to digital finance. The government can support science and technology companies in translating research findings into digital financial products and services by creating technology transfer centers, promoting the widespread adoption of cutting-edge technology in digital banking. (iii) Develop regulations that are specific to the region. Diverse perspectives on the relationship between digital money and urban environmental performance may arise within the same region, necessitating tailored legislative approaches by the government to meet the unique demands of each area effectively. Conducting a comprehensive assessment of regional variation, including considerations of local economic conditions, environmental issues, and technical infrastructure, provides a foundation for understanding the specific requirements of different regions. To address these diverse needs, governments can formulate region-specific laws for digital finance and environmental sustainability, focusing on areas such as green financing, energy efficiency, and sustainable mobility. Implementing development plans for each region can further stimulate the growth of digital finance while enhancing environmental performance. Coordination of policies, facilitated through national-level structures, is crucial to align digital finance and science, technology, and innovation (STI) policies with regional environmental objectives, ensuring policy consistency and preventing unnecessary conflicts.

