

Introduction
The Communist Party of China’s 20th National Congress report states that promoting the greening and low-carbon development of economic and social progress is a key link in achieving high-quality development. The Fifth Plenary Session of the 18th Central Committee further clarified that “green innovation” is an essential driving force for the sustainable development of China’s economy. In recent years, global issues such as climate warming, declining biodiversity, and energy depletion have threatened the entire ecosystem [1, 2]. The fast expansion of China’s economy has come at the expense of resource consumption and environmental damage. The extensive development model has caused severe damage to the ecological environment, leading to significant economic losses and health costs [3]. Against this backdrop, China has proposed steadily improving the GIE of cities, accelerating the transition to green development modes, and striving to achieve a win-win situation where economic and social development and ecological and environmental protection are coordinated [4]. GIE, which considers the ratio of output to input of green innovation activities after accounting for environmental pollution, is an emerging indicator system reflecting the contribution of unit innovation input to output [5]. It is crucial for promoting economic growth, reducing ecological damage, and facilitating the transition to a green economy [6, 7]. However, green innovation is a long-term, high-return investment, and its vast funding needs for projects cannot be sustained solely by internal R&D investment [8, 9].
Additionally, due to the imperfections in China’s financial system, including uneven financial regulatory levels, underdeveloped financial markets, structural imbalances in supply and demand, and other deep-seated issues [10], the traditional financial sector supply is relatively lacking, facing financial constraints. In addition, information asymmetry exists between financial institutions and green innovation entities, resulting in many green innovation entities lacking resources [11]. The limitations mentioned above hamper green innovation development and GIE enhancement. With the swift advancement of digital technology and the transformation and upgrading of the financial industry in recent years, digital finance, which meets the requirements of the digital intelligent era, has emerged [12]. Digital finance is a new form of finance enhanced by digital technology, characterized by efficiency, convenience, inclusiveness, innovation, personalization, security, and regulatory compliance [12]. It not only meets people’s daily financial needs but also provides more convenient and rapid financial services, addressing a series of challenges faced by green innovation development and providing new momentum for high-quality economic development [13]. It offers foundational support and significant backing for enhancing urban GIE.
Digital finance leverages digital technology to empower traditional finance, guide capital flows, improve resource allocation, and accelerate the industrial structure’s transformation and upgrading toward green and low-carbon practices [14-16]. It significantly solves problems like information asymmetry in traditional finance, ensuring that all parties in financial transactions can make decisions based on accurate and timely data, enhancing the transparency and reliability of the financing process, improving financing efficiency, and enabling more effective alignment between capital supply and demand [17]. It eases the financing constraints of various green innovation entities [18], providing ample funds and higher-level financial services for enterprises to carry out green innovation activities and enhance urban GIE. However, the imbalance of digital finance remains significant among cities in China, and regions with advanced digital financial development not only have the ability to enhance their local GIE but also leverage their first-mover advantage to attract green innovation elements from surrounding relatively less advanced areas and draw in customer service resources from other regions [19]. This leads to a gradual outflow of funds, talent, technology, and other resources from neighboring cities, thereby impacting the GIE of surrounding regions and generating spatial spillover effects. Therefore, this study pays close attention to the spatial effect of digital finance on GIE and tries to explain the mechanism from a spatial spillover perspective.
The subsequent content of this paper is as follows: The second part is a literature review, which organizes and summarizes relevant existing literature and outlines the contributions of this study. The third part is the theoretical analysis and research hypotheses, describing the impact mechanism of digital finance on GIE and proposing theoretical hypotheses in this context. The fourth part is the research design, analyzing the results of GIE, constructing empirical models, and introducing the selection of variables and data sources. The fifth part is the empirical study, presenting and analyzing the baseline regression results, spatial effect decomposition, and the analysis of moderating effects and heterogeneity, as well as conducting robustness tests. The sixth part is the conclusion and policy recommendations, summarizing the culminations of this paper and proposing corresponding measures.
Literature Review
A review of previous literature found that existing studies often start from the perspective of financial support for GIE. For instance, Yin (2020) conducted an empirical analysis of the noteworthy stimulating effect of digital banking on GIE using Chinese province panel data [20]. Tian et al. (2022) found that digital finance can enhance the overall efficiency of green finance in China [21]. He et al. (2022) discovered in their study on the impact of digital finance on provincial GIE that both the depth of use and the level of digitalization support the enhancement of green development efficiency [22]. Cao et al. (2021) consider that digital finance enhances energy environmental performance and fosters green technological innovation [23]. Scholars like Jalil et al. (2011), Fang et al. (2020), and Meng et al. (2022) also conclude that financial support plays a positive role in the development process of GIE [24-26].
Some scholars focus on the spatial effects of digital finance in supporting GIE. For example, Li et al. (2024) pointed out that digital finance has adverse spatial spillover effects on the surrounding areas, hindering the growth of GIE [27]. Zhang et al. (2023) used provincial panel data to build a spatial econometric model. They empirically analyzed the spatial spillover effects and nonlinear characteristics of the digital economy on GIE, indicating a significant positive correlation between digital finance development and GIE [28]. Chen et al. (2023) believe digital finance positively impacts local green innovation qualitatively and quantitatively [29]. Despite the fact that developing digital finance in surrounding cities harms local GIE, Ji et al. (2023) and Cheng et al. (2023) also found that the digital economy has spatial effects on GIE [30, 31].
Additionally, scholars have studied the mechanisms through which digital finance supports GIE. Firstly, digital finance, using big data and other digital technologies, is likely to gather valuable information for innovative small and micro enterprises quickly and accurately. It can reduce financing costs, address information imbalances, and optimize the allocation of resources to improve corporate GIE. For example, Li et al. (2023) identify a mechanism where “development of digital finance→alleviation of capital misallocation→enhances green innovation levels [32]”. Kong et al. (2022) found that digital finance improves information disclosure and promotes corporate GIE [33]. Rao et al. (2022) and Norden et al. (2014) point out that digital finance can address the shortcomings of traditional financial information asymmetry, accurately match capital flows, and improve resource allocation [14, 34]. Feng et al. (2022) and Jiang et al. (2022) agree that digital finance can overcome issues such as “credit mismatches” in traditional finance, thus promoting the improvement of GIE [35, 36]. Another perspective suggests that, with its inclusivity advantages, digital finance can expand financing channels for small and medium-sized innovative enterprises, easing financing limitations and promoting corporate GIE. For example, Lu et al. (2024) believe digital finance can reduce financing restrictions and significantly enhance corporate GIE [37]. Kshetri (2016) and Huang et al. (2018) found that digital finance broadens financial service channels, expands the accessibility and scope of financial services, and effectively reduces the cost burden of corporate green innovation [38, 39]. Yang et al. (2020) assert that the growth of digital finance provides relief from the financial constraints of small and micro enterprises, aiding in their sustainable progression [40]. Liu et al. (2022) and Fan et al. (2022) believe that digital finance removes financing constraints and reduces financing costs, thus increasing corporate R&D investment to meet green innovation needs [41, 42]. Furthermore, scholars like Corrado et al. (2017), Chang et al. (2022), and Guo et al. (2023) also believe that digital finance can promote urban GIE by eliminating outdated production capacities, optimizing industrial structures, and improving resource allocation efficiency [19, 43, 44].
In summary, the current research primarily focuses on analyzing the impact of digital finance on green innovation or local GIE. Only a few studies address the spatial effects of digital finance on GIE, and these studies are generally concentrated at the enterprise or provincial levels. Based on this, the potential contributions of this article are threefold: First, the study employs a panel dataset encompassing 271 prefecture-level cities across the decade from 2011 to 2021, enhancing the analysis of the effects of digital finance on GIE from a spatial correlation perspective, further clarifying the transmission mechanisms and spatial spillover effects between the two. Second, while existing literature often explores threshold effects or mediating effects between the two factors, only some scholars have analyzed the moderating effects of digital finance. This paper incorporates an interaction term between digital finance and the level of human capital into the model for empirical study. Third, it uses more accurate and in-depth expected output measurement indicators and a more reasonable SBM model to measure GIE for empirical analysis.
Theoretical Analysis and Research Hypothesis
The sustainable development theory emphasizes that economic growth should be harmonized with environmental protection, and technological innovation serves as the core driver for achieving sustainable development. Leveraging digital technology’s advantages, digital finance provides broader, more inclusive, efficient, low-cost, and accurate support [45], creating new opportunities for enterprises engaged in green technological innovation and serving as a crucial pathway to enhancing urban GIE.
The pathways created by engaging in digital finance can manifest in several ways: Firstly, digital finance can provide ample funding for enterprises’ green innovations. Digital finance can transcend time and geographical limitations by utilizing various digital and intelligent tools, reaching a broader service group [19], significantly expanding the scope of traditional financial services, supplying small and medium-sized businesses with extensive finance options, alleviating financing restrictions, and enriching financing methods. Secondly, digital finance can reduce the cost of financial services. Currently, commercial banks play the most significant role in China’s green finance system, but they often operate on a high-cost, low-return model. Through digital financial platforms, affordable financial services such as credit, financing, credit reporting, and insurance can be provided for green innovation activities. These platforms can efficiently mine and collect customers’ credit data using social networks, search engines, and extensive data, simplifying processes and shortening time frames, decreasing the costs of customer acquisition and risk assessment for financial institutions, and improving the efficiency of capital supply and demand matching [22], thus more effectively enhancing GIE.
Thirdly, the asymmetric information theory reveals that the imbalance of information in economic activities arises from knowledge gaps among participants. This phenomenon disrupts market functions, potentially leading to resource misallocation and weakened market efficiency. Specifically, due to limited or inaccurate knowledge of firms’ product demand, commercial banks, insurance companies, and other financial institutions may fail to accurately and promptly reflect market demand through data-driven insights. As a result, the disadvantaged party in the transaction faces significant difficulties. The issue of information asymmetry has become one of the key barriers to improving green innovation efficiency.
Due to the limited or inaccurate understanding of enterprises’ product demands by commercial banks, insurance, and other financial institutions, and their inability to timely and accurately display market demand through data, information asymmetry becomes a significant barrier to enhancing GIE. Digital finance can use digital technologies to accurately identify various information, high-efficiency, and high-return investment projects, reducing adverse selection by enterprises and decreasing the likelihood of moral hazards. Then, it effectively solves information asymmetry issues, enhances the match between market demand and enterprises, and empowers the improvement of GIE. Fourthly, digital finance can promote the transformation and upgrading of industrial structures [46]. Upgrading the industrial structure is a vital pathway through which digital finance influences the green transformation of industries [47]. With strong resource allocation capabilities, digital finance can guide capital toward industries with high production efficiency, low pollution, and low emissions, phasing out outdated industries with high energy consumption and pollution, optimizing and upgrading the industrial structure, and improving GIE (Fig. 1).
Therefore, digital finance can enhance the momentum for green innovation, support enterprises in conducting green innovation activities, and promote the enhancement of urban GIE. Based on the analysis above, this paper proposes hypothesis 1.
Hypothesis 1: Digital finance can significantly enhance local GIE.
In the spatial dimension, cities exhibit spatial correlations in production and development, benefiting from China’s vast market and complete industrial system. This advantage allows various production factors to transcend geographical boundaries and flow across regions, with more frequent movement occurring between geographically proximate cities [48]. Digital finance, integrated with emerging technologies such as blockchain, the Internet of Things, and artificial intelligence, utilizes its high-level financial services and large-scale data capabilities to attract the aggregation of numerous production factors. This aggregation facilitates the efficient utilization of various resources [47], attracting more advanced equipment, foreign investment, and high-quality talent for enterprise technological innovation, promoting the marketization of green innovation, and further enhancing urban GIE.
However, due to the high technical thresholds of digital finance and its dependence on skilled talent and well-developed infrastructure, the development level of digital finance varies among cities with different economic development levels. Cities with geographical competitive advantages often have higher levels of financial service development. These regions possess significantly more funds, talent, technology resources, comprehensive infrastructure, and correspondingly higher levels of digital financial development. They can use their local conditions and first-mover advantages to attract green innovation factors from surrounding cities and absorb customer resources from other regions, leading to the aggregation of high-tech industries and thus enhancing the local level of green innovation [13]. In contrast, cities with relatively lagging financial services cannot leverage late-mover advantages, leading to a loss of production factors and financial resources, weakened support for green innovation, and consequently suppressing the enhancement of GIE in surrounding areas [45]. Moreover, the development of digital finance might also intensify competition for resources between cities, making it difficult to form an effective innovation atmosphere and ecosystem, thus negatively impacting the development of green innovation in the local area for surrounding regions (Fig. 1).
Therefore, digital finance not only impacts the GIE of the local area but also affects the GIE of surrounding cities through mechanisms such as factor mobility and upstream and downstream industry linkages, generating spatial spillover effects [12]. Based on this, this paper proposes hypothesis 2.
Hypothesis 2: Digital finance suppresses the GIE of adjacent areas.
The level of human capital directly reflects an area’s or organization’s ability to absorb and monetize knowledge and technology, making it a key influencing factor in transforming financial support into technological support and promoting the improvement of GIE [49]. For digital finance relying on high-tech large-scale data, only high-end technical talents can translate it into reality, enhancing urban GIE.
On the one hand, the endogenous growth theory emphasizes that human capital is a key factor in driving long-term economic growth and technological progress. Human capital can provide ample resources, such as funds and technical talents, for green innovation activities. The enhancement of the human capital level can accelerate the aggregation of various production factors, facilitating urban industrial structure adjustment and promoting industrial optimization and upgrading [44]. On the other hand, the knowledge spillover and innovation diffusion theory suggests that the diffusion and spillover of innovation depend on a region’s knowledge level and technological capability. Accumulating human capital improves the local technological innovation research environment. High-quality talents often possess more robust information processing abilities, innovative abilities, and risk tolerance and are more willing to experiment with and use digital financial products and promote the popularization and deepening of financial services through learning, acceptance, and absorption of skills and knowledge. The factors above promote the rapid adoption of advanced technologies domestically and internationally. It encourages ongoing internal innovation within companies, facilitates the execution of high-level scientific research projects, and establishes a specialized research system, which, in turn, drives the development of high-tech enterprises and promotes green innovation through the knowledge spillover effect. Furthermore, the aggregation of high-level human capital will also enhance the efficiency of local natural resource development and utilization through technological and management innovation [50], reducing production costs, creating a favorable atmosphere for urban development, attracting more businesses to participate in the process of technological innovation, and further promoting the improvement of GIE in this region.
Fig. 1.
Mechanism of the impact of digital finance on urban GIE from a spatial spillover perspective.
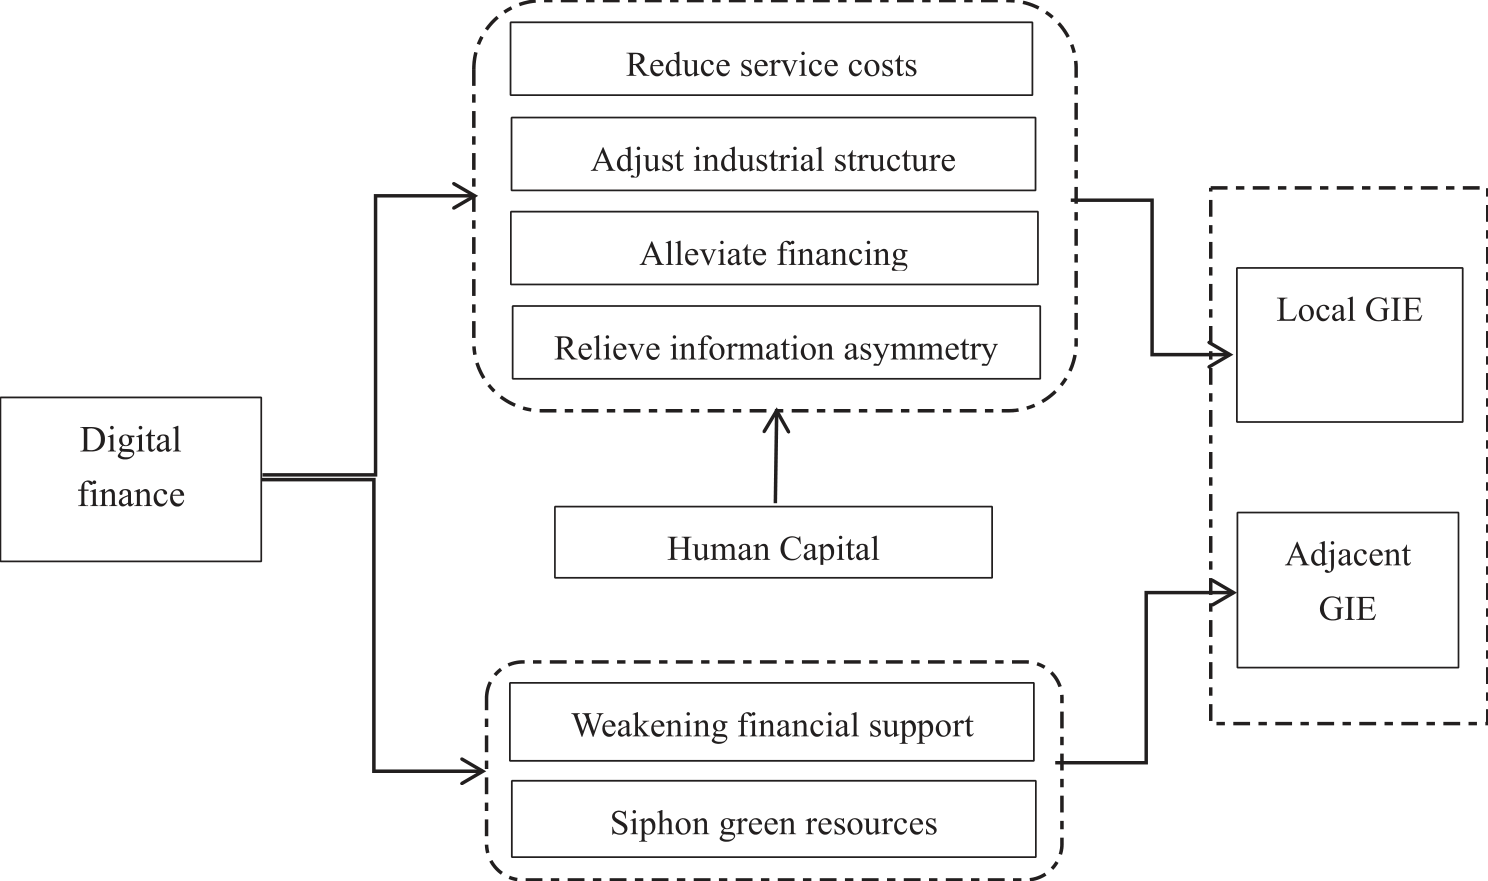
However, there exists spatial correlation among neighboring regions, and the application of digital financial inclusion also has certain thresholds. Developed regions, leveraging their strong economic strength and locational advantages, can attract various financial institutions and substantial foreign investment while drawing a large influx of high-quality talent. This results in a concentration of human capital. Additionally, these regions, benefiting from a highly skilled workforce, are able to absorb more external capital and technology, forming a mutually reinforcing positive cycle between talent and financial resources. Consequently, digital financial inclusion plays a significant role in enhancing regional green innovation efficiency in these areas. In contrast, some relatively underdeveloped surrounding regions, despite receiving certain technical and financial support through government assistance policies, experience a significant outflow of research talent to more developed areas. This migration drains essential elements of green innovation and high-tech industries from these less developed regions, leading to setbacks such as outdated innovation thinking, insufficient learning capabilities, and a lack of resources. These issues ultimately result in inefficient utilization of research funds and hinder the improvement of regional green innovation efficiency (Fig. 1). Based on this, the following hypothesis is proposed:
Hypothesis 3: The level of human capital positively influences the impact of digital finance on GIE.
Materials and Methods
Description of Variables
Explanatory Variable
The Internet Finance Research Center of Peking University compiled the “Peking University Digital Finance Index (2011-2021)” to better assess its development level. This index comprehensively measures the development of digital finance and is widely used in current digital and internet finance research. The index uses a logarithmic utility function to normalize 33 specific technical indicators, where values range from 0 to 100, with higher values indicating more resilient regional digital finance. Furthermore, weights are determined through a combination of subjective and objective weighting. This paper uses the overall index of digital finance at the city level as a proxy variable for developing digital finance, referencing Zhong et al. (2022) and using the breadth of digital finance coverage to replace the core explanatory variable for robustness checks [51].
Explained Variable
This paper uses the SBM model to calculate GIE values. The selection of GIE indicators refers to the relevant studies by Li et al. (2019), Yu et al. (2022), and Dong et al. (2021), which include input indicators, expected output indicators, and non-expected output indicators [52-54]. The input indicators include (i) labor input, measured by the total number of employees engaged in scientific and technological activities, and (ii) capital input, measured by the total expenditure on science and technology by the government. The output indicators include (i) expected output, measured by the number of green patent grants, and (ii) non-expected output, which includes industrial sulfur dioxide emissions, industrial wastewater discharges, and industrial particulate emissions of each city, measured using the entropy method to derive the city environmental pollution index.
Unlike traditional models, the SBM model considers the gap between actual input or output and target input-output, allowing for a more detailed, in-depth, and accurate analysis of GIE values. Due to the limited space, the calculation methods and steps of the SBM model are detailed in the articles of Zhao (2022) and Xu et al. (2023) [55, 56].
Moderating Variable
The development of green technological innovation depends on professional talents. High-quality talents are indispensable for enterprises to carry out green innovation. Increased cognitive ability means labor can improve resource utilization rates, help enterprises obtain cutting-edge technological information, and integrate professional knowledge into the company’s production activities, driving continuous innovation in green products and processes. On the other hand, talent agglomeration can also attract many green innovation elements to the local area, promoting the progress of enterprise green innovation. Thus, the level of human capital directly affects the efficiency of urban green innovation. This study follows the approach of Chen and Li (2022), using the ratio of college students to the total population to represent the level of human capital [57].
Control Variables
Referring to the research by Liao et al. (2023) and Fan et al. (2017), this study selects economic development level, financial support, industrial structure, technological innovation, and intensity of environmental regulation as control variables to account for other factors affecting GIE [58-60].
(1) Economic development level: The economic development level is a core driving force that continuously attracts surrounding talents, capital, technology, and other green innovation elements, representing the potential for a region’s economic development and a primary macro indicator affecting the enhancement of urban GIE. Higher economic development means more funds are invested in green innovation activities, and economically affluent citizens gradually raise their awareness of environmental protection, thereby stimulating corporate social responsibility and enhancing green technology research and development, which affects urban GIE. The per capita GDP of the prefecture-level city measures this.
(2) Financial support: Financial institutions with more funds support green innovation projects, which can develop new technologies, purchase advanced equipment, and expand production scales, thereby promoting green innovation activities. National policies providing favorable loan conditions and rates can reduce the financing costs for financial institutions, making it easier for them to obtain the necessary funds. As a result, this helps to stimulate innovation and enhance GIE. Here, the ratio of deposit balance to loan balance represents the strength of financial support.
(3) Industrial structure: Industrial structure is a considerable factor affecting the growth of green innovation force. With economic development and technological advancement, the industrial structure is gradually transitioning from low-added-value, high-pollution traditional industries to high-added-value, low-pollution green industries. This transition helps reduce resource consumption and environmental pollution, improving resource utilization efficiency and promoting the enhancement of GIE. Generally, the tertiary industry generates less pollution than the secondary industry, and the higher its output value proportion, the more favorable it is for enhancing GIE. Hence, it is measured by the value-added ratio of the secondary industry to the tertiary industry.
(4) Intensity of environmental regulation: Environmental regulation becomes an indispensable driving force for economic transformation and development. It encourages enterprises to change their original production methods.
(5) Technological Innovation: Technological innovation is the core driver for enhancing GIE. By developing new technologies, processes, and materials, technological innovation can reduce resource consumption and environmental pollution during production, thus improving production efficiency and product quality. As technology continuously advances, traditional industries increasingly face issues such as resource depletion and environmental pressures, while green industries emerge as new growth areas. Technological innovation drives the enhancement of GIE across the entire economic system by promoting the optimization and upgrading of industrial structures, accelerating the transformation of traditional industries, and fostering the development of green industries. In this paper, the number of university students enrolled is used as an indicator, represented by the logarithm of the figure.
Table 1 summarizes the definitions and measurement methods of the variables used in this paper.
Data Source
This study selects 271 cities in China from 2011 to 2021 as research subjects (omitting localities with substantial data omissions and municipalities that are directly under the control of the central government), using digital finance as an example to examine its mechanism on GIE. The leading data source is the “Peking University Digital Finance Index (2011- 2021)”, along with the “China Regional Innovation and Entrepreneurship Index” and the Big Data Research Center of Peking University, to construct an urban innovation capability index system centered on “digital inclusiveness”. Other data is derived from the National Bureau of Statistics of China and its official website. Statistical yearbooks and bulletins from various provinces and regions were used, or linear interpolation methods were employed to supplement the data, ensuring completeness. Additionally, with 2011 as the base year, major economic indicators were normalized, and some variables were log-transformed to minimize heteroscedasticity among variables. The sample selection covers different geographical areas and levels of economic development to ensure the universality of the research results.
Table 1.
Variable descriptions and measurement methods.
Table 2 shows descriptive statistics of the variables. From 2011 to 2021, we can see that the average value of GIE in China was 0.0146, indicating that the overall GIE is low, with the maximum and minimum values differing by 0.22, showing a significant disparity in GIE among cities. After log transformation, the average value of digital finance was 1.8514, with the maximum and minimum values being 3.2034 and 0.3538, respectively. Regarding the human capital level, the average value for the sample cities was 1.6524, with the maximum and minimum values being 9.2898 and 0.1217, respectively. For the control variables, the standard deviation of each was within 11.
Econometric Models
Benchmark Regression Model
To examine the spatial effects of digital finance on GIE, this paper incorporates the Spatial econometric model [61]. The basic form and the indicators selected to construct the expression of the impact of digital finance on GIE are as follows in Equation (1):
In the equation, effit represents GIE, and DFIit represents digital finance. α is the constant term, ρ, β and λ are the regression coefficients. W is the spatial weight matrix, X represents control variables, θ is the random disturbance term, i denotes the prefecture-level city i, and t denotes the year.
Moderating Effect Model
The level of human capital often represents more potent information processing and innovation capabilities. In the context of digital finance, more highly skilled talents are better able to understand and utilize financial tools, thereby more effectively transforming financial resources into the driving force for green innovation. These talents help promote research and development, and the application of green technologies, enhancing GIE. Based on the analysis above, digital finance effectively promotes GIE. Does this effect vary with the level of human capital? A presentation of how the idea of human capital affects GIE follows in Equation (2):
Table 2.
Variable descriptive statistics.
In the Equation, effit represents GIE, DFit represents digital finance, and DFI×Hum represents the interaction between digital finance and the level of human capital. α is the constant term, ρ, x and r represent regression coefficients. W denotes the spatial weight matrix, X represents control variables, θ represents the random disturbance term, i denotes prefecture-level city i, and t denotes the year.
Results and Discussion
Efficiency Analysis
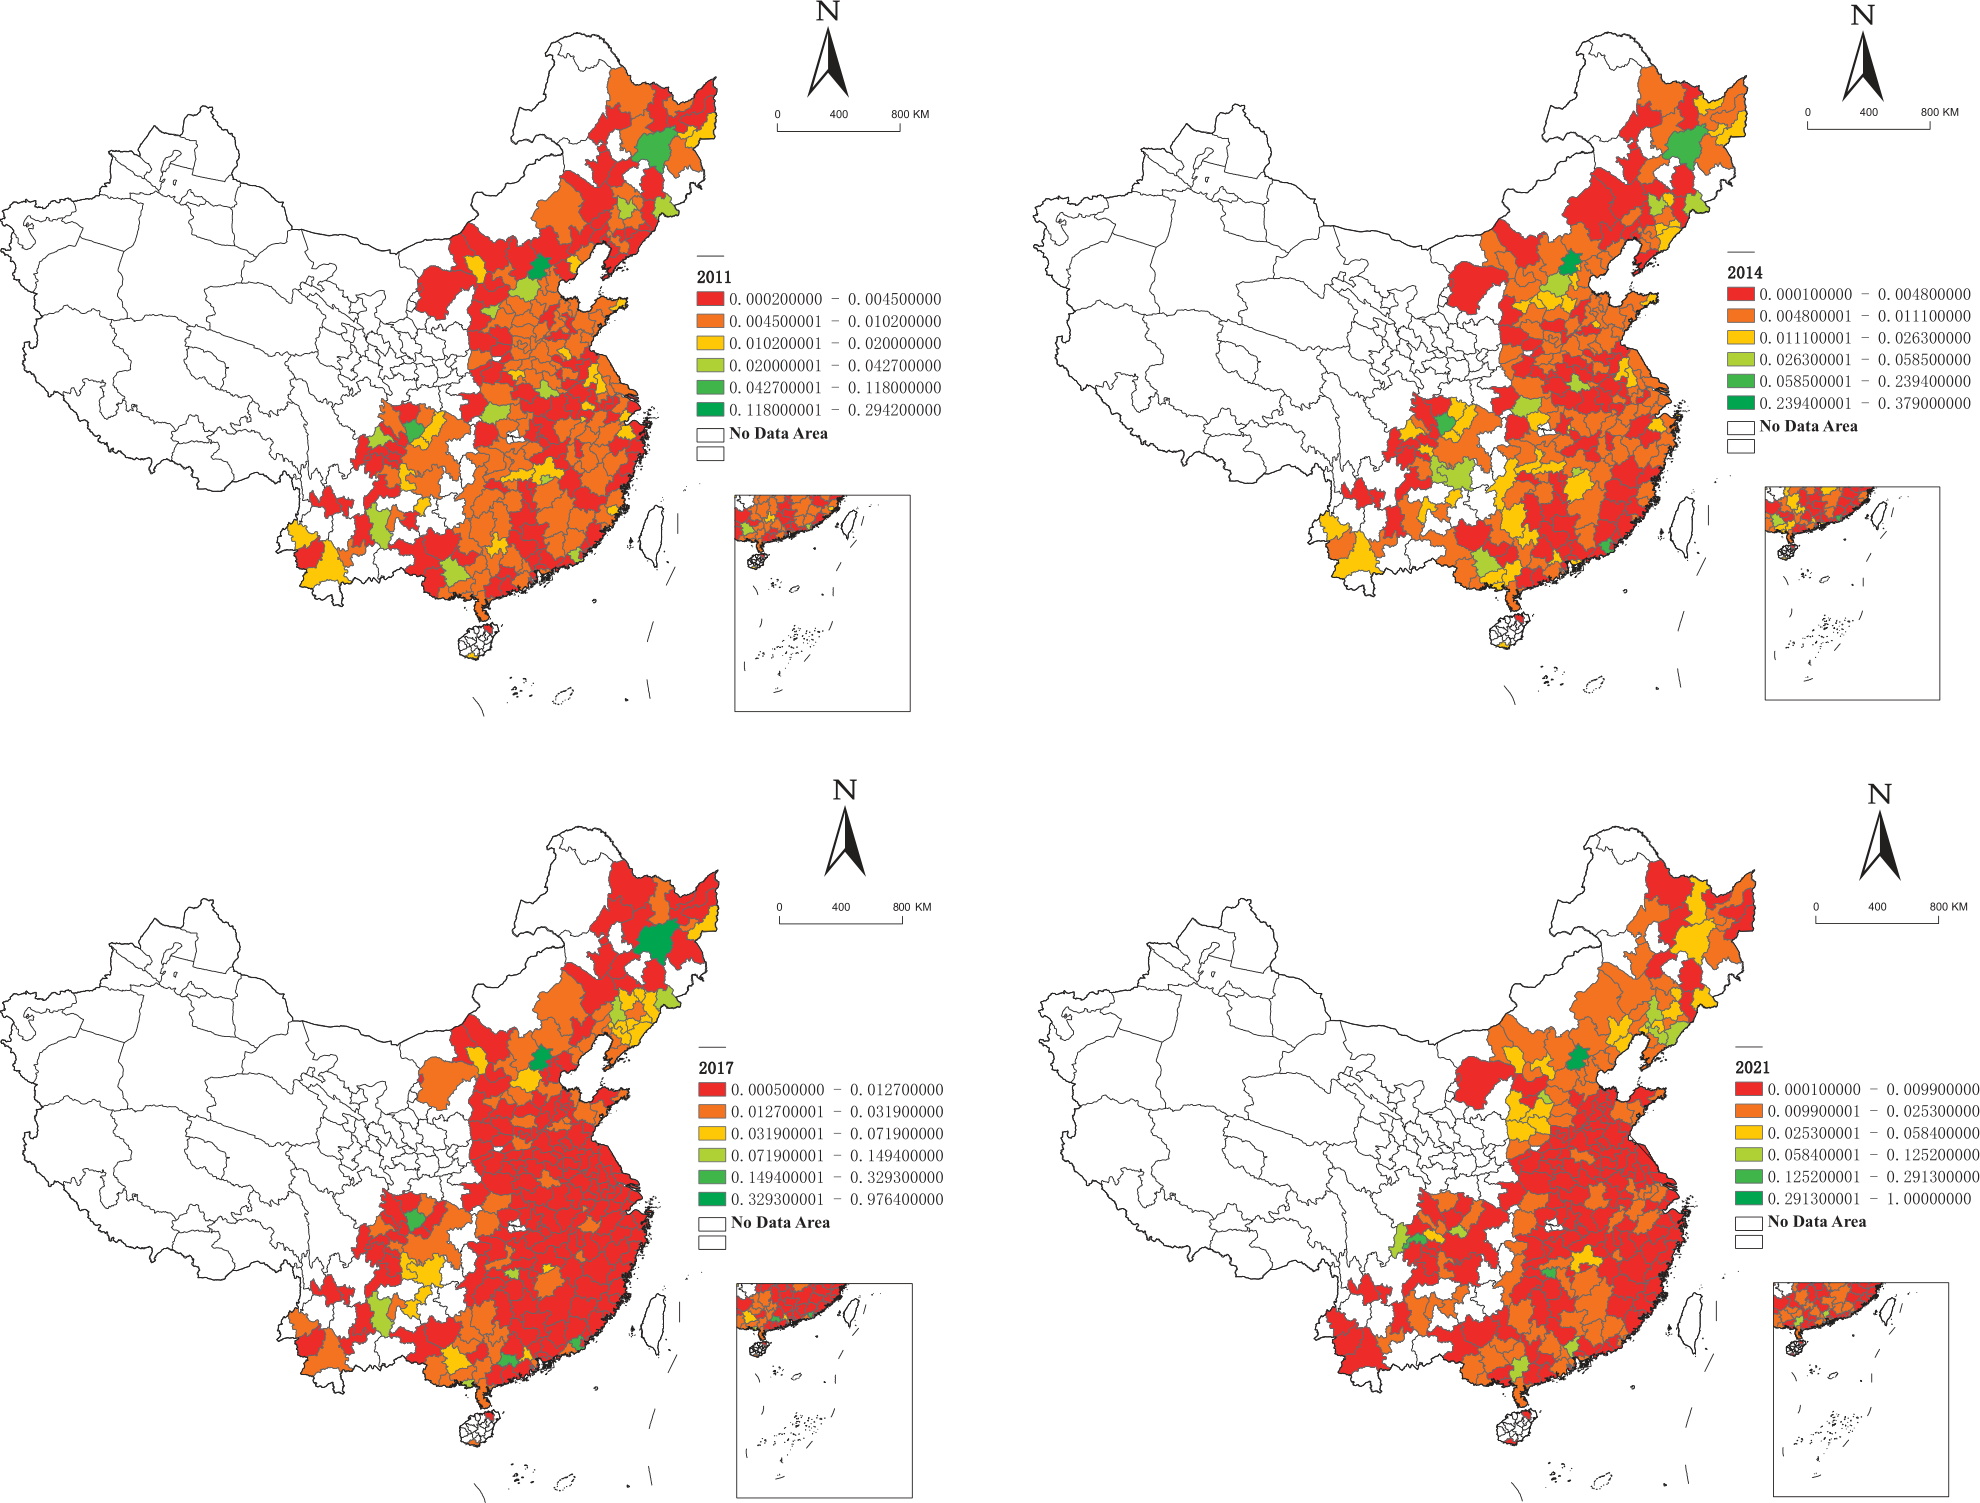
We applied the SBM model that involves the undesirable outputs to calculate the values of GIE in 271 prefecture cities [62, 63]. The input-output indicators were systematically analyzed. Fig. 2 shows the spatial and temporal characteristics of GIE in 2011, 2014, 2017, and 2021.
Overall, the GIE of cities in China remains low, with the average efficiency showing a fluctuating upward trend over the study period, increasing from 0.00861 in 2011 to 0.02182 in 2021. The average GIE of each region follows a similar growth trend to the national average, indicating a gradual improvement in China’s overall green innovation capabilities. From a regional perspective, the eastern region, with its economy, talent, and geographical location advantages, consistently maintains a higher average GIE level than the central and western regions. In recent years, as the state has increased development efforts in the western regions and high-end manufacturing has gradually shifted inland, emerging financial models such as digital finance have enabled the transcendence of geographical and temporal limitations, assisting less developed areas in their green innovation activities. Although the GIE in the western and northeastern regions has fluctuated substantially, it also shows a slow upward trend. It is noteworthy that since 2019, the GIE of all regions has declined, possibly due to the onset of the COVID-19 pandemic, which slowed down China’s economic development and led various industries into a slump, impeding the development of corporate green innovation activities and causing a drop in GIE levels. Still, there has been some recovery in recent years.
Benchmark Model Estimation Results
Moran’s I index
According to Tobler’s (1970) First Law of Geography, all things are related, but near things are more related than distant things. Moran’s I index has emerged as a fundamental metric for assessing spatial autocorrelation and expands on the previously mentioned law’s foundation [64]. This index ranges from -1 to 1. A Moran’s I index greater than 0 indicates a positive spatial correlation, and the higher the index value, the stronger the positive spatial correlation. Conversely, an index value less than 0 indicates a negative spatial correlation, and the lower the value, the more significant the negative spatial correlation. Equations (3) and (4) show the specific calculation formulas:
In the formula, s2 represents the variance of the subjects under study, wij is the spatial weight matrix. xi, xj demonstrating prefecture-level cities i and prefecture-level cities j, respectively. n represents the number of prefecture-level cities x̅ represents the average GIE of all the prefecture-level cities within the study area.
Moran’s I index was calculated for each variable, and from 2011 to 2021, the Moran’s I index for GIE was significantly greater than 0, demonstrating statistical significance at the 1% level. This result indicates that the GIE of the cities exhibits a significant positive spatial correlation, suggesting that GIE shows a clear trend of spatial clustering.
Spatial Econometric Model Selection Test
Table 3 shows the LM, LR, and Hausman tests conducted to validate the applicability of the spatial econometric model. Both the Spatial Error Model (SEM) and the Spatial Autoregressive Model (SAR) passed the significance test at the 1% level, rejecting the null hypothesis that the Spatial Durbin Model (SDM) could degenerate into a SAR or SEM; hence, the SDM model is more appropriate. Fixed and random effects model settings were considered when analyzing the spatial panel model. According to the Hausman test, the statistic was 102.95 and reached significance at the 5% level, indicating that the fixed effects model is more suitable than the random effects model. Additionally, tests for two-way, individual, and time-fixed effects were also conducted, and the results supported the rejection of the null hypothesis for individual and time-fixed effects, further indicating that the two-way fixed effects model is the more appropriate choice. Therefore, the subsequent empirical analysis will use the two-way fixed effects Spatial Durbin Model for empirical research.
Table 3.
Spatial econometric model selection test.
Benchmark Model Estimation Results
According to the results of the baseline regression analysis, as shown in Table 4, the effects of digital finance on GIE under the Spatial Durbin Model (SDM) are displayed. The spatial autoregressive coefficient (ρ) of the SDM model is -0.470, and it passes the test at the 1% level, indicating a significant spatial spillover effect.
This finding indicates that the development of digital finance can significantly promote local GIE while inhibiting the growth of GIE in surrounding areas. Additionally, economic development, financial support, and environmental regulation intensity are all significantly positively correlated with local GIE, indicating that increasing per capita GDP, intensifying environmental regulation, and expanding credit scale also contribute to improving GIE.
When analyzing spatial spillover effects, the estimated coefficient of digital finance is -0.213, showing a negative correlation at the 1% level. Similarly, economic development significantly weakens the improvement of GIE in adjacent regions, and the advancement of technological innovation accelerates the outflow of innovation factors, bringing negative impacts. Developing the tertiary industry in the industrial structure typically involves a large amount of knowledge and information exchange, accelerating the outflow of resources, talents, and high-tech industries in adjacent areas, significantly inhibiting the GIE of surrounding areas.
From the perspective of financial support, an increase in local loan balances stimulates the development of green technology innovation, attracting more funds to flow into the local green innovation field. However, this is detrimental to improving the GIE of neighboring areas, thus having a negative effect.
Based on the above empirical results, Hypotheses 1 and 2 are supported.
Spatial Spillover Analysis
Building on the above analysis and drawing from Cheng et al. (2023) [31], this study further utilizes partial differentiation of variable changes to explain spatial effects, decomposing direct and spillover effects, as shown in Table 5. The coefficient of digital finance on local GIE is 0.0618, showing a positive impact at the 1% significance level. However, its spillover effect coefficient on neighboring urban GIE is -0.1671, which is significant at the 5% level. This finding indicates that digital finance significantly enhances local GIE while exerting a significant inhibitory effect on the GIE of surrounding cities. The reason is that improving the development level of digital finance will provide a better credit fund environment, higher-quality financial services, and more precise innovation resource matching for local technological innovation, including green innovation. This result can also rationalize the flow of funds, promote the transformation and upgrading of industrial structure towards green and low-carbon, and facilitate the development of green innovation activities. However, for spatial spillover effects, enhancing the level of digital finance in a region can improve the overall financial ecological environment and create a siphoning effect. These advantages can attract the inflow of innovative elements such as talent and capital from relatively backward neighboring regions, thereby reducing the resource support for green innovation technologies in adjacent areas and inhibiting the growth of GIE in those regions.
Moreover, the direct effect of the economic development level is positive. In contrast, the spillover effect is significantly harmful, indicating that the economic development level promotes local GIE but suppresses the GIE of surrounding areas. With the improvement of the economic development level, on the one hand, the security level of local innovation fund sources increases, and market demand for innovation also increases. On the other hand, economically developed areas pay more attention to environmental quality development, attracting more high-quality resources, including talents, funds, and technology, making innovation factors relatively scarce in surrounding areas, which hinders the development of green innovation. The direct and indirect effects of industrial structure are unfavorable. However, the direct effect did not pass the significance test, possibly because the dominant industries in the region are not highly polluting or energy-intensive. Therefore, the adjustment of industrial structure has little impact on local green innovation. However, the slow growth of the tertiary industry in the region may lead to lagging green innovation development in this and adjacent areas, thereby negatively impacting GIE.
Table 4.
Benchmark regression results.
Table 5.
The result of spatial effect decomposition.
The local effect of technological innovation on GIE did not pass the significance test. Conversely, the spillover effect passed the 5% significance test, indicating a siphon effect of local technological progress on technological progress in neighboring areas. Financial support for local GIE is significantly positive, but its spillover effect is significantly harmful. Financial support can directly provide funds for local green innovation projects, reducing the financing threshold for innovation activities and thereby significantly promoting the improvement of local GIE. However, providing financial support to the local area may have a siphon effect on the funds, talents, and technological progress in surrounding areas, thereby inhibiting the improvement of GIE in surrounding areas. Environmental regulation intensity’s direct and spillover effects are insignificant because, despite China’s encouraging economic development, environmental regulation is still in its infancy and has yet to consider the specific conditions of different regions and industries. The policy implementation effects could be more satisfactory; some enterprises need to improve in interpreting and implementing regulatory policies, resulting in unclear improvements in GIE.
Further validation supports Hypotheses 1 and 2.
Heterogeneity Analysis
Low-carbon Policies Heterogeneity Analysis
Considering the substantial differences between low-carbon and non-low-carbon cities in aspects such as industrial structure and economic development, the impact of digital finance on green innovation development may vary between these two types of cities [55]. Therefore, this paper uses the “Notice on Carrying out Pilot Work on Low-Carbon Provinces and Low-Carbon Cities”, issued by the National Development and Reform Commission on July 19, 2010, to categorize the sample into low-carbon pilot cities and non-low-carbon pilot cities for heterogeneity testing.
According to Columns (1) and (2) in Table 6, digital finance significantly enhances the GIE of low-carbon cities, whereas its impact on the GIE of non-low-carbon pilot cities is not significant. This is because regions designated as low-carbon pilot cities typically enjoy more policy support, more developed market mechanisms, and stronger technological backing compared to non-low-carbon pilot cities. These advantages help better guide resource allocation, reduce financing costs, and provide a more favorable institutional environment and social atmosphere for the application of digital finance in the field of green innovation, thereby significantly promoting the GIE in these regions. In terms of spatial spillover effects, digital finance does not significantly impact the GIE of either low-carbon pilot cities or non-low-carbon pilot cities. This phenomenon might be due to the fact that the classification and development of low-carbon and non-low-carbon pilot cities are still in their early stages, and regional development is uneven, leading to an insignificant spillover effect on surrounding areas.
Human Capital Level Heterogeneity Analysis
Talent is a crucial carrier of innovation activities. Differences in human capital levels may affect a city’s innovation capacity and economic development [65]. Therefore, based on the average human capital levels of 271 cities in 2021, the sample is divided into cities with high and low levels of human capital. The heterogeneity regression results are shown in Columns (3) and (4) of Table 1. It is evident that, in terms of direct effects, digital finance significantly enhances GIE in cities with higher human capital levels compared to regions with lower human capital levels. The reason is that higher human capital areas also tend to have more developed digital finance, and these cities benefit from a demographic dividend. The knowledge reserves, innovation capabilities, and practical experience of highly skilled talents enable them to better utilize innovation resources, maximizing the role of digital finance in promoting GIE. Regarding spatial spillover effects, in comparison to regions with lower human capital levels, cities with higher human capital levels exhibit a stronger talent aggregation effect as their digital finance index increases. This significantly attracts green innovation elements from surrounding areas, thereby inhibiting the improvement of GIE in neighboring cities.
Table 6.
Heterogeneity regression results for digital finance and varying levels of human capital.
Regional Heterogeneity Analysis
Considering the differences in geographic location and economic development conditions of various cities, this paper categorizes the 271 prefecture-level cities nationwide into four regions – East, Central, West, and Northeast – according to the National Bureau of Statistics’ criteria and conducts subsample regression. Table 7 displays the regional differences in the spatial spillover effects of GIE.
In the Eastern region, digital finance positively impacts GIE directly but has a significant negative spillover effect. This is due to these areas having unique geographical locations, higher levels of economic development, advanced technological innovation capabilities, and well-developed infrastructure. They invest heavily in the research, development, and application of digital technologies, leading the forefront of development. Their green innovation activities developed earlier and may have reached a certain saturation level, making it difficult to achieve significant improvements in the short term.
However, due to their superior conditions, their suction effect is strong. The development of digital finance in the Eastern region attracts a large influx of financial, technological, and human resources, causing a scarcity of resources in surrounding areas, thereby significantly inhibiting the enhancement of GIE in neighboring regions. In the Central region, digital finance exerts a positive direct impact on GIE but also generates a negative spillover effect, both of which are significant. These results may be due to the policy inclinations in recent years and the gradual shift of high-end manufacturing to inland areas, increasing quality resources and gradually improving the economic development level in the Central region. The development of digital finance has been robust, remarkably promoting the local GIE.
Similarly, the Central region can also attract green innovation resources from relatively backward surrounding areas, significantly inhibiting the development of green innovation activities in those surrounding areas. In the Western and Northeastern regions, both the local and spillover effects are insignificant. Findings conclude that these regions need to bridge the divide compared to other areas in terms of economic development and innovation capabilities, with insufficient infrastructure construction and talent reserves, leading to low levels of investment and output in green innovation, limiting the popularization and application of digital finance. Additionally, the policy environment and institutional support for digital finance and green innovation may need strengthening, and effective regional cooperation mechanisms and information-sharing platforms may be lacking, resulting in fewer and lower-quality green innovation projects. Financial resources may only partially support green innovation activities. Therefore, in these regions, the promotional effect of digital finance on GIE is challenging to manifest significantly. However, as national support for the development of the Western and Northeastern regions continues to increase, the development of digital finance in these areas is gradually accelerating, and its promotional effect on GIE is expected to be further enhanced in the future.
Table 7.
Regional heterogeneity test results.
Influence Mechanism Analysis
Human capital is the carrier of knowledge and skills, and high-quality technical talent is indispensable for enterprises to engage in green innovation. The level of human capital significantly modulates the extent to which digital finance impacts GIE. This paper further introduces an interaction term between digital finance and human capital levels in the baseline regression model to analyze the moderating role of human capital on their relationship to try and validate the hypothesis presented above.
The impact of digital finance on GIE, and whether the level of human capital influences it, is estimated by observing the coefficients of the interaction terms DFI×Hum and W(DFI×Hum). The test results of the human capital moderating effect, as shown in Table 8, indicate that the regression coefficient of the interaction term (DFI×Hum) is 0.004, passing the significance test at the 1% level. The result indicates that the impact of digital finance on GIE influences human capital; namely, the higher the level of human capital, the more pronounced the promoting effect of digital finance on local GIE. Human capital reflects the quality of personnel in a region. When a region improves its human capital level, it signifies having more talents with higher education and specialized skills. These talents possess more formidable innovation capabilities and environmental awareness, enabling them to drive the research and application of green technology, forming a social atmosphere conducive to green innovation and providing intellectual and environmental support for enterprise-independent innovation and green innovation. Moreover, high-level talents are directly related to the acceptance and efficiency of digital finance, promoting the popularization and deepening of financial services, better mastering and applying new technologies and knowledge, and driving the development of green innovation, thereby enhancing urban GIE.
From a spatial perspective, the regression coefficient of the interaction term W(DFI×Hum) between digital finance and human capital level is -0.0021, failing to pass the significance test. This finding indicates that the local level of human capital plays a suppressive role but is not significant in the impact of digital finance on the GIE of surrounding areas. The reason for this may lie in the fact that there are differences in the level of human capital in different regions, and the talent concentration areas are more conducive to attracting foreign capital, technology and other resources to promote the development of technological innovation of enterprises, and siphon factors of production and green resources from the surrounding areas to the local area, resulting in weakening of the support for green innovation in the neighboring cities, which will inhibit the enhancement of the efficiency of green innovation in the surrounding areas. However, differences in geographic culture, industrial structure, policy environment, and other factors between different regions may hinder the full flow of human capital from regions with high levels of digital financial development to neighboring regions, thus limiting the spatial spillover effect of human capital regulation.
Therefore, Hypothesis 3 is supported.
Robustness Test
Replacing the Core Explanatory Variable
To verify the robustness of the conclusions regarding the impact of digital finance on GIE discussed earlier, this section conducts a robustness test using the coverage breadth of digital finance as a substitute for the total index of digital finance as the core explanatory variable. Table 9 shows the results of this test. The coefficient of the impact of the coverage breadth of digital finance on local GIE (i.e., the local effect) is 0.009, while the spillover effect coefficient on the GIE of neighboring cities is -0.0041, both of which pass the 1% significance test. This finding indicates that the coverage breadth of digital finance significantly improves GIE in the local area, and it also has a significant inhibitory effect on the GIE of surrounding cities, consistent with the empirical results presented earlier. Thus, substituting the total index of digital finance with the coverage breadth of digital finance, the impact of digital finance on GIE still exhibits a significantly positive local effect and a significantly inhibitory spillover effect. The results confirm that the conclusions drawn earlier are robust and convincing.
Table 8.
Moderating effect test results.
Table 9.
Robustness test.
Table 10.
Endogeneity test.
Spatial Matrix Substitution
To verify the robustness of the conclusion regarding the impact of digital financial inclusion on GIE, we employ an alternative spatial matrix substitution approach. Specifically, we replace the spatial geographic matrix with a 0-1 adjacency matrix for robustness testing. The results of this test are presented in Columns (3) and (4) of Table 9. The coefficient of digital financial inclusion on local GIE (i.e., the local effect) is 0.0341, which is statistically significant at the 5% level. Meanwhile, the spillover effect on the GIE of neighboring cities has a coefficient of -0.0135, which passes the 10% significance test. These findings indicate that digital financial inclusion significantly enhances local GIE while exerting a significant inhibitory effect on the GIE of surrounding cities. This result is consistent with the previous empirical findings, confirming the robustness of the earlier conclusions.
Endogeneity Test
Considering that the pilot policy for green financial reform may influence the relationship between digital financial inclusion and GIE, this study incorporates the green financial reform pilot policy into the analysis. In 2017, the State Council launched pilot programs for green financial reform and innovation in selected regions of Zhejiang, Guangdong, Jiangxi, Guizhou, and Xinjiang. Subsequently, the scope of these pilot zones was expanded. The results of this analysis are presented in Table 10. The coefficient of digital financial inclusion on local GIE (i.e., the local effect) is 0.0627, while the spillover effect on the GIE of neighboring cities has a coefficient of -0.1798, both of which are statistically significant at the 1% level. These findings suggest that even after accounting for the endogeneity of the green financial reform pilot policy, digital financial inclusion still significantly enhances local GIE while exerting a significant inhibitory effect on the GIE of surrounding cities. This result is consistent with the previous empirical findings. Furthermore, regarding the impact of being a green financial reform pilot city on GIE, neither the local effect nor the spillover effect passes the significance test. A possible explanation for this is that the number of pilot cities remains relatively limited, which may not be sufficient to exert a statistically significant influence on GIE.
Conclusions
Based on panel data from 271 prefecture-level cities in China from 2011 to 2021, this paper conducts a theoretical analysis of the impact of digital finance on GIE. Initially, the SBM model is used to measure GIE across cities, followed by the construction of a spatial Durbin econometric model to empirically study the spatial spillover effects of digital finance on GIE, exploring regional heterogeneity in the East, Central, West, and Northeast regions, and finally integrating a moderating effect analysis to investigate how human capital levels affect this relationship.
The robustness tests confirm the following main conclusions:
First, the overall GIE in China remains relatively low, with regional differences present. However, the general trend across all regions shows a fluctuating upward trajectory, indicating a gradual improvement in green innovation capability. The average level of GIE is continuously higher in the Eastern area, while the Central and Northeastern regions experience more significant fluctuations than the Eastern region.
Second, digital finance significantly enhances GIE in local cities. It enables the improvement of GIE by providing sufficient financial and technical support, easing enterprises’ financing difficulties, resolving information asymmetry, breaking away from the long-tail population, and reducing service costs. Conversely, it has a significant inhibitory effect on the GIE of surrounding areas. Regions with higher levels of digital finance development can attract more factor aggregation, reducing green resources in neighboring areas and suppressing the development of GIE in surrounding cities.
Third, the heterogeneity analysis shows that digital finance has a positive, albeit not significant, impact on GIE in the Eastern region but a significantly detrimental impact on surrounding areas. In the Central region, digital finance has a significantly positive impact on local GIE and a significantly negative impact on surrounding areas. In contrast, in the Western and Northeastern regions, digital finance’s direct and spillover effects on GIE are not significant. These results indicate significant differences in the impact of digital finance on GIE across the four major regions and a clear correlation between the development of GIE and digital finance.
Fourth, the impact of digital finance on GIE is moderated by human capital, with a higher level of human capital enhancing the promotional effect of digital finance on local GIE.
Policy Implications
Based on these findings, the following policy recommendations are proposed:
Firstly, enhance digital finance systems and bolster infrastructure development. On the one hand, increase governmental backing for digital finance, broaden its reach, and encourage nationwide implementation and growth to improve financial service accessibility and convenience. Financial institutions should improve the quality of digital finance services and consistently innovate financial goods and services, meet green innovation enterprises’ diversified financing needs, continue reducing financing costs for small and medium-sized enterprises, and improve financing efficiency. At the same time, the government should oversee financial institutions to enhance risk management levels to prevent financial risks and establish and perfect a digital finance regulatory system to ensure business compliance and maintain financial market order. On the other hand, our country should boost the construction of network and financial hardware infrastructure, such as enhancing the coverage and quality of the internet and mobile communications networks, ensuring stable and high-speed network services in remote areas, and providing the fundamental conditions for developing digital finance.
Second, strengthen regional cooperation and coordination to mitigate the inhibitory effect on GIE in surrounding cities. The country should actively promote the establishment of a cross-regional green innovation cooperation mechanism, encourage local and surrounding areas to engage in green innovation cooperation, share experiences and resources, and guide the flow of funds, technology, and talent to regions with relatively lower levels of financial development. Additionally, avoid excessive resource concentration in certain cities, promote the optimal allocation of digital finance resources, improve the level of digital finance development in neighboring cities, alleviate the siphoning effect of developed areas on relatively lagging neighboring regions, and collectively promote the development and application of green technology which would coordinate and enhance GIE across regions.
Third, fully leverage the moderating role of human capital and enhance the level of human capital. The government ought to put more money into education and develop more gifted people, including providing high-quality education and training opportunities and skill development plans, raising people’s educational and skill levels, and providing strong talent support for green innovation. Additionally, the government should optimize the talent structure, train and recruit high-tech and high-level talent targeted at the green innovation field’s needs, and enhance talent’s supportive and leading role in green innovation.
Fourth, differentiated digital finance policies tailored to local conditions should be formulated. The government should fully consider different regions’ economic, social, and cultural backgrounds, as well as the current status and needs of financial services, and develop precise strategies for enhancing GIE in different cities. For example, for economically weaker regions with lower levels of digital technology proliferation, such as the Western and Northeastern areas, the government could introduce policies to support and reward enterprises engaged in green innovation activities in these regions, intensify efforts in green technology research and innovation, and stimulate enterprise innovation and creativity. The government should increase environmental law enforcement for regions with a developed secondary industry. High-polluting, high-energy-consuming industries must be strictly limited, while industrial transformation and upgrading should be promoted.
Fifth, in response to the regional disparities in digital finance development, low-carbon pilot cities and non-pilot cities should formulate differentiated policies. For instance, in regions with higher levels of digital finance development, greater emphasis can be placed on leveraging digital technology to drive low-carbon technological innovation and industrial upgrading while encouraging financial institutions to innovate financial products and services to provide more funding support for low-carbon industries. Conversely, in regions with lower levels of digital finance development, it is necessary to prioritize strengthening digital finance infrastructure, enhancing the penetration and depth of digital finance adoption. Additionally, regional collaboration should be enhanced between low-carbon pilot cities and non-pilot cities to jointly promote the integrated development of digital finance and the low-carbon economy. Specifically, through regional collaboration, resource sharing and complementary advantages can be realized, facilitating the dissemination and application of low-carbon technologies.
Limitations and Suggestions for Future Research
The following limitations and potential directions for future research are identified regarding the aforementioned study: Firstly, the data scope of this paper is limited to the period from 2011 to 2021 and covers only 271 prefecture-level cities in China, which may result in incomplete data for some cities and fail to reflect the recent status of digital finance and GIE, especially in the rapidly evolving field of digital finance, where existing data may not capture these dynamic changes. Therefore, future research is suggested to expand the time range by incorporating data from 2022 onwards to examine the impact of recent policy and technological developments. Meanwhile, considering that changes in some regions, such as county-level cities and rural areas, may influence the overall results, data from these regions can also be included to obtain more universally applicable conclusions.
Secondly, although this study reveals the spatial spillover effects of digital finance in various aspects (such as eastern, central, and western regions, whether a city is a low-carbon pilot, and the level of human capital), the heterogeneity is still broadly categorized. For instance, the heterogeneity of different types of digital financial institutions, innovation policies, and industrial structures is not analyzed in depth. This may result in insufficient explanatory power for spatial spillover effects, especially as the impact on remote areas and resource-based cities may not be fully captured. Therefore, future research is recommended to further refine the regional classification by categorizing regions based on multiple dimensions such as industrial structure, resource endowment, and the level of digital financial development. Additionally, more detailed urban characteristics (such as industrial policies and technology innovation orientations) can be introduced to further explain the spatial effects in different regions.
Thirdly,, the study uses the SBM model to measure GIE. Although the SBM model is commonly used in efficiency evaluation, it still has certain limitations and potential measurement errors. Therefore, future research can attempt to combine other evaluation methods, such as the DEA model, or consider both technological progress and scale effects. It can also explore how to integrate external environmental factors (such as policy support and resource investment) to more comprehensively and accurately evaluate GIE and construct an indicator system for GIE.
By addressing these limitations and suggestions, future research can delve deeper into the complex relationship between digital finance and GIE and explore more refined policies and mechanisms to enhance GIE and sustainable development levels.

