

Introduction
In recent years, the global economy has experienced rapid growth, accompanied by significant environmental pollution issues. In 2022, the Fifth United Nations Environment Assembly put forward the goal of helping the world achieve sustainable development in society, economy, and environment through enhanced action on nature conservation. The greenhouse effect caused by carbon emissions has become the most difficult dilemma. The logistics and transportation sector produces more than one-third of the world’s carbon dioxide emissions, and this share is growing. 7.7 billion tons of carbon dioxide were emitted by the transport sector in 2021, and this was increased by a further 2.1 percent in 2022.
Therefore, supply chains should enhance environmental information disclosure to reduce carbon emissions and environmental pollution. Indeed, existing literature extensively demonstrates the positive impact of firm environmental information disclosure on environmental protection. For instance, Peng and Ji (2022) discovered that Environmental Information Disclosure Policies can optimize the innovation environment, leading to increased innovation input and the attraction of innovative talent, thus promoting green innovation [1]. Lin (2022) revealed that environmental information disclosure significantly reduces industrial pollutant emissions and enhances technological innovation, subsequently improving the efficiency of the green economy [2]. Additionally, environmental information disclosure has been found to significantly affect CPA audit fees, financial performance, and capital markets, as well as price delays (Xue et al., 2020; Wang et al., 2020; Zhang and Yang, 2023) [3-5].
The existing literature on how to promote firm environmental information disclosure focuses on environmental regulation, firm culture, and executive traits. Although the existing literature has extensively discussed this topic, it ignores the interactions between firms, in particular how the supply chain affects environmental information disclosure. The green demands of suppliers and customers can profoundly influence firm strategies and promote firm environmental information disclosure. Countries deepen supply chain innovation and application to drive a green supply chain transition. In 2018, China introduced the Notice on Carrying Out Pilot Supply Chain Innovation and Application, which aims to promote the construction of green supply chains by innovating supply chain technologies and models. Therefore, the implementation of this policy provides us with a research opportunity, which is used as a quasi-natural experiment in this study to investigate whether the construction of green supply chains can promote firm environmental information disclosure by constructing a difference-in-differences (DID) model.
The main marginal contributions of this study can be elaborated on in the following three aspects: Firstly, this paper contributes to the understanding of factors that promote firm environmental information disclosure. Adopting a micro perspective expands the scope beyond internal factors like corporate culture and executive traits to include the influence of supply chains in driving firm green strategies. The findings highlight that the establishment of green supply chains facilitates firms’ environmental information disclosure. This means that the construction of green supply chains in China has achieved some success, and the green demands of suppliers and customers will have an impact on firms.
Second, based on the theory of legitimacy and stakeholder agreement, the paper explores the potential mechanisms through which green supply chains work, providing lessons for better understanding and applying them. This paper explores the influence mechanisms resulting from internal incentives and external monitoring. The construction of a green supply chain promotes executives' environmental awareness and external media monitoring, which in turn enhances environmental information disclosure. This implies that the impacts of green supply chains come from multiple sources, influencing executives, the media, the public, and so on through the green demands of suppliers and customers.
Third, this paper offers recommendations to advance the development of green supply chains and promote environmental information disclosure. China’s green supply chain construction has achieved initial results, which not only provides reference experience for other firms in China, but also has profound significance for the construction of green supply chains in other countries, especially developing countries.
Literature Review
Sorting through the literature on how to promote firm environmental information disclosure, the macro aspect focuses on environmental regulation. For example, Zhang et al. (2020) found through a fuzzy-set qualitative comparative analysis that strict environmental regulation can significantly promote environmental information disclosure [6]. Chen et al. (2023) discovered that the Green Credit Policy has a notably positive impact on the quality of corporate environmental information disclosure [7]. Liu and Guo (2023) revealed that the environment fee-to-tax reform substantially enhances internal governance and controls within heavily polluting industries, consequently facilitating both monetary and non-monetary environmental information disclosure [8]. Siming et al. (2024) identified that air pollution significantly increases executives' negative emotions, thereby hindering firm environmental information disclosure [9]. Furthermore, digital finance has also been found to significantly influence environmental information disclosure (Guo et al., 2023) [10].
At the micro level, the existing literature focuses on firm culture and executive traits. For example, Chao et al. (2023) found that Confucianism has a significant contribution to firms' environmental information disclosure and is more pronounced among state-owned firms and firms in highly polluting industries [11]. Wang et al. (2023) found that entrepreneurial heterogeneity significantly contributes to environmental information disclosure by facilitating environmental management practices [12]. Hussain et al. (2023) revealed that enhanced CEO competence fosters firm environmental information disclosure, with a more pronounced effect observed in a sample comprising female CEOs [13].
At the same time, with the continuous development of green supply chain practices, many scholars have also carried out research on them. For example, Zhang and Dong (2023) developed a big data green supply chain system utilizing an enhanced genetic optimization algorithm [14]. Based on data from top hotels in Tehran, Iran, Ghaderi et al. (2023) found that green supply chain management significantly reduced environmental costs [15]. Using a sample of 153 firms in Ghana, Agyabeng-Mensah et al. (2024) found that green supply chain learning significantly influenced green organizational citizenship behavior [16]. It's true that the impact of green supply chains on firm environmental information disclosure has not received much attention from scholars, despite its significance. This gap in the literature highlights the importance and potential for further study in this area.
In this paper, the Supply Chain Innovation and Application Pilot Policy (SCIAPP), aimed at advancing green supply chain development in China, serves as a quasi-natural experiment. Through DID modeling, this study investigates its influence on firm environmental information disclosure, providing additional insights into existing research in the field.
Institutional Background and Theoretical Mechanism
Institutional Background
In China, the 13th Five-Year Plan introduced the concept of supply chain for the first time, emphasizing the need to accelerate various innovations, including Internet-based business models, service models, management models, supply chains, and logistics chains. It advocated for the swift construction of a green supply chain industry system.
Subsequently, China has issued several policy documents directly related to supply chain innovation. On October 5, 2017, China released the Guiding Opinions on Actively Promoting Supply Chain Innovation and Application, which underscored the importance of constructing a green supply chain. On April 10, 2018, China issued a Circular on the Pilot of Supply Chain Innovation and Application, which outlined the implementation period and support targets of the policy pilot. The aim was to advance the new development concept of innovation, coordination, greenness, openness, and sharing through supply chain innovation, ultimately constructing a green supply chain.
This pilot is divided into two parts, including city pilots and firm pilots. There are 57 city pilot projects and 266 firm pilot projects. Compared to traditional supply chains, this pilot project seeks to establish greener and more internationalized supply chains rather than focusing only on issues such as quality, price, and stable trading of raw materials and products. Therefore, as an important initiative to promote the greening of supply chains, this pilot program has profound significance for the green development of supply chains in China and globally.
Theoretical Mechanisms
Legitimacy theory states that firm behavior must meet the criterion of legitimacy. Legitimacy comes not only from the laws introduced by the government, but also from the demands of suppliers and consumers and the expectations of the public and the media. More specifically, environmental legitimacy requires that a firm's environmental behavior satisfy the pursuit of greenness, environmental protection, and efficiency by the government, suppliers, consumers, and the public. If a firm's behavior does not meet the criteria of environmental legitimacy, the firm will be penalized, such as government fines, consumer boycotts of products, and public pressure (Truong and Berrone, 2023) [17].
In addition to this, stakeholder theory states that the survival and development of a firm depend on stakeholders, not only shareholders, but also creditors, suppliers, consumers, and so on. Some of these stakeholders share the business risks of the firm, and some of them supervise and constrain the firm. Therefore, the business decisions of the firm must consider their interests and be subject to their supervision. This means that if firms are able to satisfy the needs of stakeholders, they will also receive more support, such as borrowing from creditors, support from consumers, and positive comments from the public (Simpson and Sroufe, 2014) [18].
The traditional supply chain establishes a close connection between firms, suppliers, and customers, whose focus is mainly on the quality and price of raw materials and products. SCIAPP promotes the construction of green supply chains, linking the interests of a wider range of stakeholders, including the government, the public, the media, and so on. As the public and other stakeholders become more concerned about the environment, the standard of environmental legitimacy is raised, and the environmental behavior of firms and supply chains is subject to more scrutiny and constraints.
Therefore, SCIAPP mandates pilot firms to disclose additional environmental information to adhere to environmental legitimacy standards in response to stakeholder scrutiny and constraints. Simultaneously, increased environmental information disclosure by firms enhances their external reputation, attracting more resource support. Consequently, the potential for resource support further incentivizes firms to disclose more environmental information, creating a virtuous cycle. Building on this premise, the paper proposes the following hypotheses:
Hypothesis 1: SCIAPP significantly promotes environmental information disclosure in pilot firms.
Specifically, this paper posits that the facilitative impact of SCIAPP on firm environmental information disclosure stems from two main factors: internal control mechanisms and external monitoring mechanisms.
First, based on the principal-agent theory, the interests of management and shareholders do not always coincide. Under the condition of information asymmetry, management usually takes advantage of the information to satisfy its personal interests, thus generating agency costs, adverse selection problems, and moral hazards. Agency conflicts not only make firm management inefficient and waste resources in the short term, but also cause firms to neglect their long-term development goals. In the case of low environmental legitimacy standards, management usually violates firm sustainable development goals, causing environmental information asymmetry and exacerbating environmental pollution (Zhao and Jia, 2023) [19].
Numerous studies have shown that environmental regulation is conducive to mitigating firms' agency conflicts and reducing agency costs (Houqe et al., 2022) [20]. From a constraint perspective, environmental regulation imposes supervision on firms from the outside and discourages management opportunism. If management violates corporate sustainability goals and does not meet external standards of environmental legitimacy, it is not only subject to administrative penalties, but also to negative public pressure from the managerial market. From an incentive perspective, environmental regulation also typically provides resource support for environmentally compliant firms. Environmental regulation can guide firms through market incentives to go green within limits and provide financial subsidies and policy preferences, a tool that largely enhances the incentives of firm managers to engage in environmental governance, thus making them proactively move closer to the needs of stakeholder interests. As a result, higher standards of environmental legitimacy promote greater environmental awareness among executives, which in turn improves firm environmental protection.
SCIAPP enables firms in the supply chain to reach a consensus on long-term development goals, which in turn promotes the improvement of the environmental awareness of the management of the firm, so that it converges with the interests of stakeholders and pays more attention to the fulfillment of firm social responsibility and sustainable development. On the one hand, SCIAPP raises the standard of environmental legitimacy, and the environmental pollution behavior of firms is subject to the constraints of relevant laws, regulations, and policy systems. Management must improve the transparency of firm environmental information to provide an information basis for firm green transformation. On the other hand, SCIAPP prompts chain firms to disclose more environmental information and reduce environmental information asymmetry, and further drives chain firms to form an environmental protection community of interest. Mutual constraints and supervision among firms prompt managers to continuously improve their environmental awareness, and firm decisions must be in line with the common interests of the green development of the supply chain. Based on this, this paper proposes the following hypotheses:
Hypothesis 2: SCIAPP significantly improves executives' environmental awareness, which in turn promotes firm environmental information disclosure.
Secondly, the stakeholder theory states that by actively meeting a certain level of stakeholder needs, firms can establish a close relationship with their stakeholders and thus gain a lot of resource support. The theory offers an explanation for firms’ disclosure of environmental information and their fulfillment of social responsibility. As stakeholders increasingly prioritize climate change and environmental concerns, firms must address their interests in firm environmental performance and disclose more environmental information accordingly. Thus, based on stakeholder theory, firms actively disclose environmental information to meet the demands of external monitors, particularly with the rapid advancement of media technology and the media economy, the media’s role in monitoring and constraining firms has strengthened (Kim et al. 2024) [21].
Existing literature has demonstrated the impact of environmental regulation and external media monitoring on the firm fulfillment of environmental responsibility. Kong et al. (2020) found that media monitoring can promote firm environmental responsibility [22]. Zhang et al. (2022) argue that media monitoring can replace environmental regulation to play a partial role in promoting firm environmental performance. Moreover, the role of media monitoring in promoting firm environmental protection is independent of the medium and tone of voice [23]. Yan (2023) argues that media monitoring and environmental regulation have a synergistic facilitating effect on firm fulfillment of environmental responsibility [24]. In order to obtain more positive media coverage and win the praise of the public, firms have to disclose more environmental information to establish a more environmentally friendly and responsible firm image (Wang et al. 2022) [25].
SCIAPP garnered more attention for the pilot firms, including more media coverage. As an external watchdog, the media focuses on the sustainability performance of the pilot firms and communicates their performance to the public. Further, stakeholders such as the government, market investors, and community residents will make decisions to support or resist the firm based on the information reported in the media. Facing the pressure of media reports, the pilot firms involved in SCIAPP will proactively disclose more environmental information and mitigate information opacity with external stakeholders to garner increased support. Building on this premise, the paper proposes the following hypotheses:
Hypothesis 3: SCIAPP significantly enhances external media monitoring, which in turn promotes firm environmental information disclosure.
Research Design
Model Building
In this study, a DID model is employed to evaluate the policy effect, specifically to examine whether SCIAPP promotes firms’ environmental information disclosure (EID). The DID model has been extensively utilized by scholars in policy effect assessment studies due to its effectiveness in mitigating endogeneity challenges, for example, Mao et al. (2023) [26]. The benchmark regression model is shown in model (1).
In model (1), i denotes a firm, t denotes a year, and EID denotes the environmental information disclosure of firm i in year t. Time×Treat denotes a policy variable, i.e., SCIAPP; X denotes a series of control variables; δ denotes an individual firm fixed effect, μ denotes a year fixed effect; ε is the disturbance term.
If SCIAPP can significantly promote the environmental information disclosure of pilot firms, the coefficient of Time×Treat should be significantly positive.
Variable Definitions
Explained Variable
For the explained variable (EID), this paper refers to the research methodology of Al-Tuwaijri et al. (2004) [27] and Zhang et al. (2023) [28], which assigns a value of 0 to the indicator of no disclosure, a value of 1 to the indicator of qualitative disclosure, and a value of 2 to the indicator of quantitative disclosure.
The monetary environmental information includes indicators such as wastewater emissions, chemical oxygen demand (COD) emissions, sulfur dioxide (SO2) emissions, carbon dioxide (CO2) emissions, particulate matter (soot and dust) emissions, industrial solid waste generation, waste reduction and management, wastewater emission reduction and management, dust and soot management, solid waste utilization and disposal, noise and light pollution management, and radiation management, among others. These indicators are assigned values of 0, 1, or 2 based on specific criteria.
The non-monetary environmental information includes indicators such as environmental protection concepts, environmental protection objectives, environmental management systems, environmental education and training, environmental special actions, environmental incident emergency response mechanisms, environmental honors or awards, “three simultaneous” systems, key pollution monitoring units, pollutant emission standards compliance, environmental accidents, environmental violations, environmental petition cases, ISO 14001 certification status, and ISO 9001 certification status, among others. These indicators are assigned values of 0 or 1 based on specific criteria.
This paper employs the equal weighted average method to derive three indicators for measuring the level of environmental information disclosure by the firm. Specifically, EID represents the total amount of environmental information disclosed, EID_M represents monetary environmental information disclosure, and EID_NM represents non-monetary environmental information disclosure.
Explanatory Variable
For the explanatory variable (Time×Treat), this paper uses SCIAPP as a quasi-natural experiment and evaluates its policy effect through a DID model.
The interaction term Time×Treat represents SCIAPP. First, this paper constructs the dummy variable Time, which represents the time before and after SCIAPP. If the year is before 2018, it is assigned a value of 0 (as before the policy). On the contrary, if the year is 2018 and after, it is assigned as 1 (as after the policy). Second, this paper constructs the dummy variable Treat to indicate whether a firm is a pilot firm or not. If a firm is selected as a pilot firm of SCIAPP, it is assigned a value of 1 (as a treatment group). If a firm is not selected as a pilot firm, it is assigned a value of 0 (as the control group).
Mechanism Variables
For the executives' environmental awareness (EEA), referring to Liu and Cao (2024) [29], this paper adopts the text analysis method to measure it. Combined with firm annual reports, this paper selects specific terms such as "Energy Saving and Emission Reduction," "Environmental Protection Strategy," "Environmental Protection Concept," "Environmental Management Organization," "Environmental Education," "Environmental Training," "Environmental Technology Development," and "Environmental Audit" to assess the awareness of firm executives regarding environmental protection. The frequency of occurrence of these terms in the annual reports of the firms is used as an indicator of executive environmental awareness.
For external media monitoring (EMM), referring to Guldiken et al. (2017) [30], this paper chooses media coverage data to measure the level of media monitoring. Specifically, this paper utilizes the total number of news stories featuring the firm in the content of newspaper financial news as a proxy variable. The logarithm of this variable is taken after adding 1 to it.
Control Variables
Referring to the research results of Zhang (2023) [28], this paper adds a series of control variables to the model. Specifically, this paper selects a number of firm-level financial and internal governance variables, including years of listing (Listing), firm size (Size), asset-liability ratio (Leverage), return on total assets (ROA), board size (Board), board independence (Independent), ownership concentration (Top1), and nature of property rights (SOE). In addition to this, this paper selects a number of variables for economic development at the regional level, including economic level (GRP) and economic structure (Industry).
The specific variable definitions are shown in Table 1.
Table 1.
Definition of Control Variables.
Samples and Data
The initial sample for this study shows A-share listed firms for the period spanning from 2013 to 2021. Subsequently, the sample is refined through the following steps: (1) excluding ST and *ST firms; (2) excluding firms operating in the banking and finance industry; (3) excluding firms listed for one year or less;
(4) excluding firms with gearing ratios greater than 1; and (5) excluding firms with missing values of core variables.
This study obtained 3,697 listed firms with a total of 25,884 observations. Among them, the number of pilot firms is 75, accounting for 2.2%. In order to avoid the effect of singular values, this study also did the shrinking tail on the 1% and 99% quantiles for all continuous variables in the above sample.
Based on the above determined sample, this study collects firm financial and environmental information data from the China Stock Market & Accounting Research Database (CSMAR) and relevant data at the regional level from the China Statistical Yearbook.
Empirical Analyses
Descriptive Statistics
Table 2 presents the descriptive statistics of the variables. Specifically, EID exhibits a mean of 0.267 and a standard deviation of 0.252. This suggests that the average level of environmental information disclosure among listed firms in China has been low and has displayed considerable variation in recent years. The mean value of the interaction term Time×Treat is 0.012, indicating that the observations of pilot firms after the implementation of the policy account for 1.2% of the whole, and the later paper needs to carry out a more complicated screening of the control group or the sample as a whole to ensure the robustness of the study. Descriptive statistics for other variables are not repeated.
Table 2.
Descriptive Statistics.
Correlation Analysis
Table 3 presents the correlations between all variables in the study. The correlation coefficients between the interaction term (Time×Treat) and EID are significantly positive at the 0.01 level, indicating a significant positive correlation between them. Additionally, the correlation coefficients between all other variables do not exceed 0.6, suggesting the absence of multicollinearity among them.
Benchmark Regression
Dynamic Effect Inspection
Satisfying the parallel trend assumption is one of the prerequisites for the application of the DID model, i.e., the trends of the explanatory variables in the experimental and control groups should be consistent before the shock. Drawing on the idea of the event study approach, this study constructed the following model for dynamic effects testing (Jacobson et al., 1993) [31].
Fig. 1 plots the estimates of the regression coefficients of the interaction term (Time×Treat) at 95% confidence intervals using the first year of the sample period (2013) as the base period (Nunn and Qian, 2011) [32].
As shown in Fig. 1, the confidence intervals of the coefficient values of the interaction term contain 0 in 2018 and before, which indicates that there is no significant difference in the trend of changes in environmental information disclosure between pilot and non-pilot firms, satisfying the parallel trend hypothesis.
Benchmark Regression Results
Table 4 presents the results of the benchmark regression. In column (1), after controlling for year fixed effects and individual fixed effects in the DID model, the regression coefficient of the interaction term (Time×Treat) is significantly positive at the 0.01 level, indicating that SCIAPP has a significant positive impact on the environmental information disclosure of the pilot firms. Moreover, in column (2), when control variables are added to the model, the regression coefficient of the interaction term (Time×Treat) remains significantly positive at the 0.01 level. These results support the conclusion that SCIAPP significantly promotes the environmental information disclosure of pilot firms, thus confirming Hypothesis 1 while controlling for other conditions.
Furthermore, in columns (3) and (4), the regression coefficients of the interaction term (Time×Treat) are both significantly positive at the 0.01 level. This suggests that SCIAPP has a significant facilitating effect on both monetary environmental information disclosure (EID_M) and non-monetary environmental information disclosure (EID_NM), with a stronger effect observed for the former.
Robustness Tests
Placebo Test
In order to verify that the results of the study are not influenced by unobservable factors, this study conducted a placebo test (Cai et al., 2016) [33]. Specifically, 75 firms with the same number of pilot firms as in this study were selected as the pseudo-experimental group by random sampling, interacted with Time to form a pseudo-policy variable, sampled 500 times, and regressed to test whether the coefficients were significant.
Fig. 2 plots the regression results for 500 samples. The horizontal coordinates of the hollow circles are the coefficient values, the vertical coordinates are the p-values, the real curves are the kernel density distributions of the sampling, the horizontal dashed line on the Y-axis scales the 10% significance level, and the vertical dashed line on the X-axis scales the true regression coefficient values (see Table 4, column (2)).
As shown in Fig. 2, most of the values of the regression coefficients for the 500 samples are around the value of 0 and are insignificant. Also, the true regression coefficients of this study are outliers. This indicates that the results of this study are almost free from the influence of unobservable factors that cannot be realized through random sampling. Therefore, the results of this study are robust.
PSM-DID Test
Since the pilot firms were not the result of random sampling, i.e., the selection of the experimental group may have been influenced by other factors, as evidenced by the significant differences between the experimental and control groups on other factors, this study screens the sample by propensity score matching (Heckman, 1997) [34] to control for these effects. Specifically, this study used all control variables as covariates, calculated propensity scores, and performed 1:2 nearest-neighbor matching. Table 5 presents the results of the balance test for propensity score matching (PSM). After matching, none of the covariates exhibited significant differences between the experimental and control groups, indicating the validity of the matching process.
Table 3.
Correlation Analysis
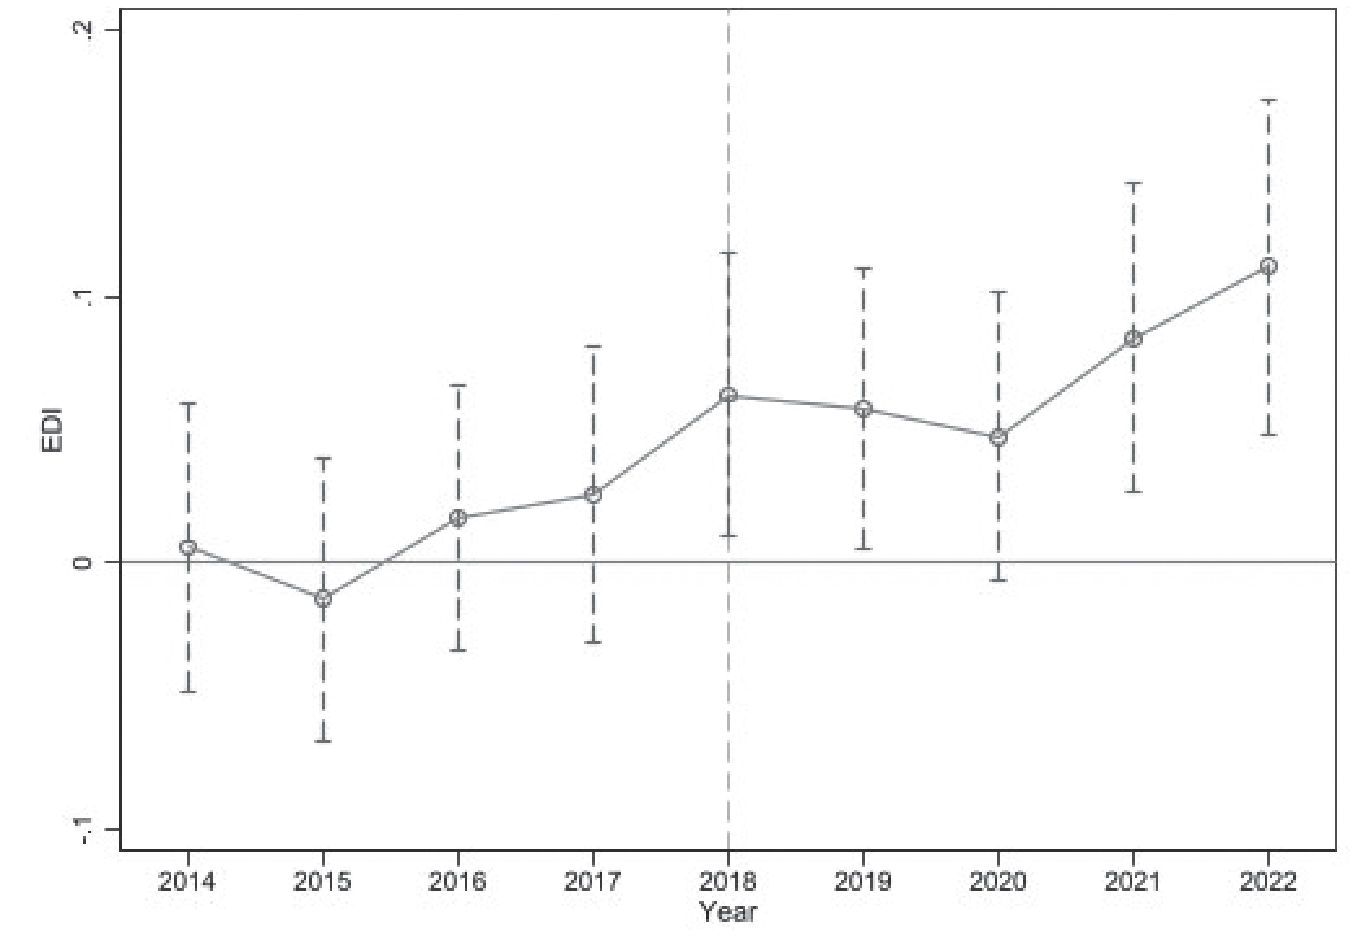
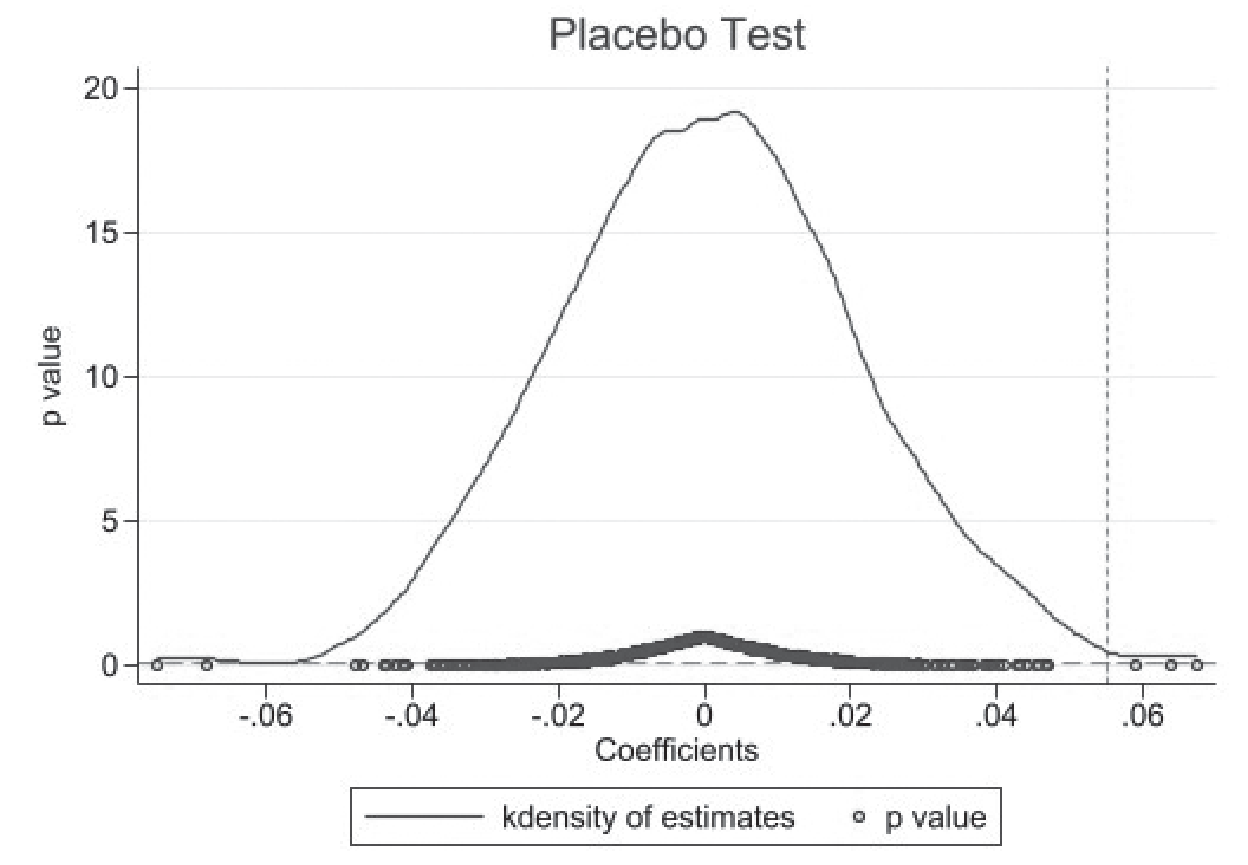
Table 4.
Benchmark Regression Results.
In column (1) of Table 6, with 1,102 PSM-matched observations, the regression coefficient of the interaction term (Time×Treat) remains significantly positive. This robustness check confirms that the results of the study hold even after controlling for potential confounding variables through PSM matching.
Replacement of the Control Group
SCIAPP is a dual pilot policy with both pilot cities and pilot firms. If the control group includes firms from non-pilot cities, the results of the study will be impacted by certain regional differences. Therefore, this study excludes non-pilot city firms from the sample to minimize the impact of regional differences.
As shown in column (2) of Table 6, where the regression coefficient of the interaction term (Time×Treat) remains significantly positive, it further reinforces the robustness of the study’s results.
Controlling Interference from Other Policies
The results of this study may also be interfered with by other contemporaneous policies, especially environmental protection policies.
First, to control for the impact of China’s environmental protection tax (Tu and Wang, 2021) [35], this study examines whether firms have paid the environmental protection tax from the “Taxes Payable” section in the notes to financial statements. Using the Difference-in-Differences (DID) model, the study constructs a dummy variable ET, which equals 1 if the firm pays the environmental protection tax after 2018 and 0 otherwise. This variable is then added to the regression model as a control variable.
Second, China piloted the Green Finance Reform and Innovation Pilot Zone in five provinces in 2017, including Guangdong, Zhejiang, Jiangxi, Guizhou, and Xinjiang. Existing studies have extensively examined the impact of this pilot policy on firms (Zhao et al., 2023) [36]. Therefore, based on the DID model, this paper generates the dummy variable GF of the Green Finance Reform and Innovation Pilot Zone and adds it to the regression model as a control variable.
As shown in column (3) of Table 6, where the regression coefficient of the interaction term (Time×Treat) remains significantly positive, the study’s results are robust even after controlling for the impact of China’s environmental protection tax.
Table 5.
Balance Test.
Table 6.
Robustness Tests.
Regarding the Replacement of EID Measures
This paper utilizes environmental rating data from Sino-Securities Index Information Service (Shanghai) Co. Ltd. (Zhang, 2024) [37], which provides a more accurate measure of each indicator compared to the common measure used in existing literature. In column (4) of Table 6, the regression coefficient of the interaction term (Time×Treat) remains significantly positive. Indicating the robustness of the study’s results when using this alternative measure for environmental information disclosure.
In addition to this, we replaced the environmental information disclosure (EID) measure with another method. We added 3 indicators related to the disclosure vehicle on top of 12 monetary disclosure indicators and 15 non-monetary disclosure indicators, as indicated in column (5) of Table 6, where the regression coefficient of the interaction term (Time×Treat) remains significantly positive, the study’s results are robust even after incorporating alternative measures of environmental information disclosure. These measures include disclosure of environmental information in the annual report, disclosure in a separate social responsibility report, and disclosure in a separate environmental report. Each indicator is assigned a value of 1 if environmental information is disclosed in the relevant vehicle and 0 otherwise. This finding further reinforces the robustness of the study’s results.
Other Robustness Tests
To further eliminate the endogeneity problem of the study, as shown in column (6) of Table 6, this study lags the interaction term (Time×Treat) and all control variables by one period, and the regression coefficients of the interaction term (Time×Treat) are significantly positive. As shown in column (7) of Table 6, this study clusters robust standard errors at the firm level, and the regression coefficient of the interaction term (Time×Treat) is significantly positive.
Further Analyses
Mechanism Tests
Executives' Environmental Awareness
To test Hypothesis 2, we first tested whether SCIAPP has a facilitating effect on executives' environmental awareness (EEA). Further, we added EEA as a control variable in the baseline regression model to test whether it has a mediating effect.
As shown in column (1) of Table 7, the coefficient value of the interaction term (Time×Treat) is significantly positive, indicating that SCIAPP significantly promotes executives' environmental awareness. In column (2), the coefficient value of EEA (executives' environmental awareness) is also significantly positive, suggesting that the enhancement of executives' environmental awareness further promotes firm environmental information disclosure. Moreover, the coefficient value of the interaction term (Time×Treat) is reduced compared to column (2) in Table 4, indicating that EEA plays a mediating role in the relationship between SCIAPP and firm environmental information disclosure. Furthermore, as shown in columns (3) and (4), these findings remain consistent when distinguishing between monetary and non-monetary disclosures of environmental information, indicating the robustness of the results.
In summary, SCIAPP can significantly promote executives' environmental awareness, which in turn promotes firm environmental information disclosure. Hypothesis 2 is proven.
External Media Monitoring
To test Hypothesis 3, we first tested whether SCIAPP has a facilitating effect on external media monitoring (EMM). Further, we added EMM as a control variable in the baseline regression model to test whether it has a mediating effect.
As shown in column (5) of Table 7, the coefficient value of the interaction term (Time×Treat) is significantly positive, indicating that SCIAPP significantly promotes external media monitoring. In column (6), the coefficient value of EMM (external media monitoring) is also significantly positive, suggesting that the enhancement of external media monitoring further promotes firm environmental information disclosure. Moreover, the coefficient value of the interaction term (Time×Treat) is reduced compared to column (2) in Table 4, indicating that EMM plays a mediating role in the relationship between SCIAPP and firm environmental information disclosure. Furthermore, as shown in columns (7) and (8), these findings remain consistent when distinguishing between monetary and non-monetary disclosures of environmental information, indicating the robustness of the results.
In summary, SCIAPP can significantly promote external media monitoring, which in turn promotes firm environmental information disclosure. Hypothesis 3 is proven.
Heterogeneity Analysis
Internal Control
Information asymmetry is indeed closely linked to firm internal governance. Generally, a firm with a well-structured internal control system tends to have higher information transparency and is less likely to engage in opportunistic behaviors by its management. Moreover, the effectiveness of external monitoring often depends on the strength of internal control mechanisms. Therefore, this paper concludes that the impact of SCIAPP on firm environmental information disclosure is more pronounced in samples with stronger internal control.
Table 7.
Mechanism Tests.
Table 8.
Heterogeneity Analysis of Internal Control.
In this study, the degree of internal control perfection of firms is measured using the internal control index constructed by the DIB database (Wang et al., 2021) [38]. The sample is then divided into two groups based on the median of the index for each year, with the group possessing a higher index indicating stronger internal control. As shown in Table 8, the coefficient value of the interaction term is larger in the group with stronger internal control for EID, EID_M, and EID_NM. This suggests that the enhancement of internal control within firms reinforces the effectiveness of SCIAPP in promoting environmental information disclosure.
Environmental Concern
At the regional level, the level of environmental information disclosure varies among firms in different regions. Based on the stakeholder theory, firms have to satisfy the public's demands on them. The higher the environmental concern in a region, the more environmental information firms in that region have to disclose. Therefore, this paper argues that SCIAPP has a stronger role in promoting firm environmental information disclosure in regions with higher environmental concern.
This paper searched the search index on Baidu's website with pollution as the keyword (Li et al., 2021) [39] and used the index as the level of environmental concern in the region for that year, as well as dividing it into two groups using the median of that year as a criterion, with the group with the higher index being the one with the stronger level of concern. As shown in Table 9, the coefficient value of the interaction term is larger in the group with stronger environmental concern, both for EID, EID_M, and EID_NM. This indicates that increased regional environmental concern has contributed to the positive impact of SCIAPP.
Table 9.
Heterogeneity Analysis of Environmental Concerns.
Conclusions and Recommendations
Environmental pollution and ecological destruction make the world realize the urgency of building green supply chains. In 2018, China issued the Circular on Pilot Supply Chain Innovation and Application, aiming to promote the construction of a green supply chain. This study takes it as a quasi-natural experiment to study the consequences of its impact by constructing a DID model. It is found that, firstly, the SCIAPP pair significantly promotes firm environmental information disclosure, which is established after a series of robustness tests such as the placebo test and the PSM-DID test. Second, SCIAPP promotes firm environmental information disclosure by raising executives’ environmental awareness and facilitating external media monitoring. Third, the role of SCIAPP is more pronounced among firms with stronger internal governance and firms in regions with higher environmental concern.
Based on the above findings, this study proposes the following policy recommendations: First, all countries in the world should recognize the significant advantages of green supply chains in coping with climate and environmental protection and promote resource integration, communication, and collaboration in supply chains through some governmental measures. Evidence from China proves that the formation of green supply chains can be effectively promoted through policy tools and further contribute to their environmental information disclosure, which may be worthwhile for many countries.
Second, to foster the development of green supply chains, the government should implement a range of complementary measures to support and incentivize firms. Specifically, the government ought to promptly establish standardized guidelines for firms' environmental information disclosure and create a dedicated platform for information disclosure. Additionally, the government could provide incentives, such as rewards to firms that disclose environmental information more comprehensively and with higher quality. Furthermore, by leveraging environmental information disclosure, the government can integrate green financial policies with green supply chains to effectively drive the green transformation of firms.
Third, in promoting the construction of green supply chains, especially in the process of policy implementation, the government should pay attention to the differences between different firms and different regions. The implementation of policies must not be one-size-fits-all, and different strategies should be formulated according to individual differences. At the same time, the government should also pay attention to the feedback and suggestions of firms and make timely adjustments to policy measures.
This study also has some limitations. First, this paper’s exploration of the micro impacts of SCIAPP is inadequate, and future research can continue to explore its impacts on firm green innovation, productivity, and so on. Second, limited by the availability of data, this paper does not directly test the impact of SCIAPP on firm pollutant emissions. Future research can put effort into this, provided that accurate data on firm pollutant emissions is obtained. Finally, this paper mainly examines the impact of firm pilots in SCIAPP, and future research can continue to explore the impact of urban pilots, such as regional carbon emissions, energy efficiency, green total factor productivity, and so on.

