

Introduction
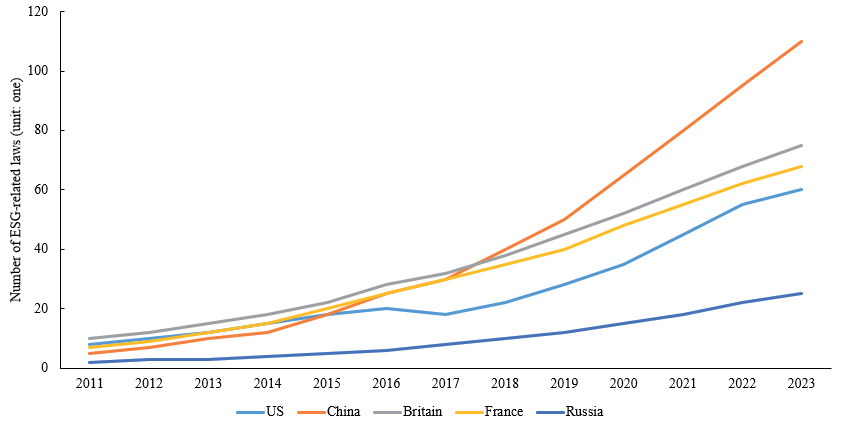
In recent years, the frequent occurrence of global climate disasters has raised significant concerns [1]. According to data from the International Disaster Database, there has been an average of over 300 climate disasters (such as floods, storms, extreme heat, and typhoons) worldwide each year from 2011 to 2024, as shown in Fig. 1. These disasters not only severely damage natural ecosystems but also pose a significant threat to human life and property safety. “2024 Natural Disaster Loss Record Report” of the Munich Reinsurance Company indicates that climate disasters in 2024 caused global economic losses amounting to $320 billion, with an estimated death toll of 11,000. In the face of this severe situation, governments and organizations around the world are actively exploring paths for green development to balance economic growth with environmental protection. During the process of sustainable development, countries have recognized that ESG principles can facilitate the synergistic development of environmental, social, and economic benefits [2]. To promote the widespread adoption of ESG concepts, many countries have implemented policies to support the green transformation of companies. For instance, the five permanent members of the United Nations Security Council have seen a yearly increase in ESG-related policies since 2011, which has contributed to the global dissemination of ESG principles, as illustrated in Fig. 2.
The ESG concept establishes a comprehensive value assessment system that encompasses environmental, social, and governance dimensions, requiring companies to fulfill their environmental and social responsibilities while optimizing their internal governance structures. This not only helps enhance a company’s environmental image and increases its attractiveness to capital and talent [3, 4], but also improves management efficiency, drives innovation, and ultimately boosts total factor productivity [5]. However, as major polluters, heavily polluting companies face numerous challenges when implementing ESG strategies [6]. Firstly, the high pollution levels and large workforce of heavily polluting companies result in elevated costs for ESG implementation. Secondly, the rising public awareness of environmental protection places greater demands on these companies, thereby reducing the returns on their ESG strategies [7]. Additionally, the instability of the international environment has intensified. Reports from the Uppsala Conflict Data Program, the International Crisis Group, and annual reports from international economic research institutions indicate a continuous rise in geopolitical conflicts and economic warfare from 2011 to 2023, as shown in Fig. 3. These events exacerbate global economic uncertainty and affect the economic performance of various countries through supply chains, increasing the complexity of the impact of heavily polluting companies’ ESG performance on total factor productivity [8]. For example, uncertainty in the economic environment may lead heavily polluting companies to reduce ESG investments that yield lower short-term benefits, negatively affecting their ESG performance. Geopolitical risks and supply chain disruptions also heighten cost pressures, further impacting the ESG performance and resource utilization efficiency of heavily polluting companies. However, amidst rising environmental uncertainty, if heavily polluting companies enhance their ESG performance, they can demonstrate their organizational capabilities and risk resilience, attract more capital and talent, and swiftly seize market opportunities, thereby achieving economic growth.
Currently, scholars are exploring the impact of ESG performance on total factor productivity from various perspectives and have clarified its influencing mechanisms. For instance, the study by Deng et al. (2023) indicates that performance in the three dimensions of Environmental, Social, and Governance can enhance total factor productivity [9]. Zhu et al. (2025) found that a company’s ESG performance can improve total factor productivity by reducing financing constraints and promoting technological innovation [10]. Additionally, research by Yu et al. (2024) approaches the issue from the perspective of information asymmetry and demonstrates that improving ESG performance can enhance total factor productivity by reducing internal labor costs and agency costs [11]. However, due to the specific nature of their industry, the impact of ESG performance on total factor productivity for heavily polluting companies carries a degree of uncertainty, and the currently highly unstable external environment may interfere with this relationship. Existing studies have noted that environmental uncertainty can diminish a company’s willingness to implement ESG performance [12], but they have not focused specifically on heavily polluting companies or investigated how environmental uncertainty affects the relationship between their ESG performance and total factor productivity. As the world’s largest hub for heavily polluting companies, China provides ample and typical subjects for research. Moreover, during its economic transformation and green development process, the government has introduced a significant number of ESG-related policies, with 110 policies launched by 2024, making it a pioneer in global policy formulation. In this context, studying the ESG performance of heavily polluting companies in China can not only reveal companies’ behavioral patterns under environmental uncertainty but also provide valuable insights for other developing countries.
Based on the analysis above, this study utilizes data from heavily polluting companies listed on the A-share market in China from 2011 to 2022 to explore the impact of ESG performance under environmental uncertainty on total factor productivity. The main contributions are as follows: (1) Current academic research on heavily polluting companies is relatively scarce, and there is little literature examining how environmental uncertainty affects the relationship between ESG performance and total factor productivity. The heavily polluting companies play a significant role in economic development, yet they also face severe environmental challenges and regulatory pressures. By focusing on this critical area and incorporating environmental uncertainty into the analytical framework, this study not only fills an important gap in the existing literature but also provides new insights into how heavily polluting companies can adjust their business strategies in a complex environment. (2) As global attention to sustainable development and ESG investment continues to grow, companies, particularly in heavily polluting industries, are facing increasingly severe environmental challenges and regulatory pressures. The findings of this study provide empirical evidence and practical guidance for heavily polluting companies in formulating and implementing their ESG strategies, helping them to more effectively respond to the risks and opportunities posed by environmental uncertainty. Furthermore, the insights gained from this research are not only significant for the sustainable development of heavily polluting companies but also offer feasible solutions for global environmental governance, helping to improve the sustainable development capacity of all countries in the world.
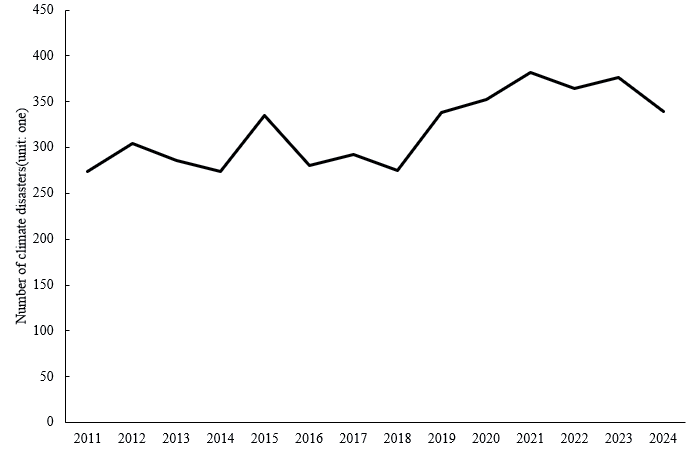
Theoretical Basis and Research Hypothesis
Sustainable development theory emphasizes the importance of meeting the needs of the present without compromising the ability of future generations to meet their own needs. In recent years, China’s heavily polluting companies have made significant contributions to economic growth, but they have also led to serious environmental pollution issues. For example, in 2020, China’s steel production accounted for 56.5% of the global total, providing millions of jobs and greatly boosting the national economy [13, 14]. However, in the same year, the carbon dioxide emissions from this industry accounted for approximately 30% of total emissions from the industrial sector, causing severe environmental pollution [15]. Similarly, other heavily polluting companies, such as coal, oil, and textiles, have contributed to rapid economic growth while also resulting in significant environmental pollution problems. Therefore, accelerating the green transition of heavily polluting companies is crucial for achieving sustainable economic development.
ESG performance is used to measure a company’s overall performance across the environmental, social, and governance dimensions, reflecting its practices in sustainable development and fulfillment of responsibilities. Total factor productivity measures resource utilization efficiency, indicating the increase in output achieved through technological advancements and organizational innovations while keeping capital and labor inputs constant. Existing research indicates that improvements in corporate ESG performance can promote growth in total factor productivity through multiple mechanisms. Specifically, ESG performance can significantly reduce information asymmetry between companies and regulatory agencies as well as the capital market, while also enhancing the effectiveness of internal governance. This, in turn, contributes to improving the total factor productivity of the companies. For instance, He et al. (2022) and Xue et al. (2024) noted that enhanced ESG performance demonstrates a company’s commitment to sustainable development and social responsibility, which helps to build trust among stakeholders such as regulatory agencies, investors, and consumers, thereby reducing the risk of project disruptions [16, 17]. Shakil (2021) focused on heavily polluting companies and found that higher ESG performance can signal a company’s determination for long-term value creation and risk management to the market, which in turn attracts more funding and high-quality talent, improves project execution efficiency, and ultimately drives an increase in total factor productivity [18]. Furthermore, Ghanbarpour (2022) indicated that ESG practices can optimize a company’s internal governance structure, reduce project redundancies, and expedite project implementation processes, thus positively impacting total factor productivity [19].
Drawing from these findings, this study posits the following hypotheses:
H1: Improving ESG performance in heavily polluting companies can accelerate project advancement speed by shaping an environmentally friendly image and optimizing internal governance, thereby enhancing total factor productivity, as supported by the studies of Shakil (2021) and Ghanbarpour (2022) [18, 19].
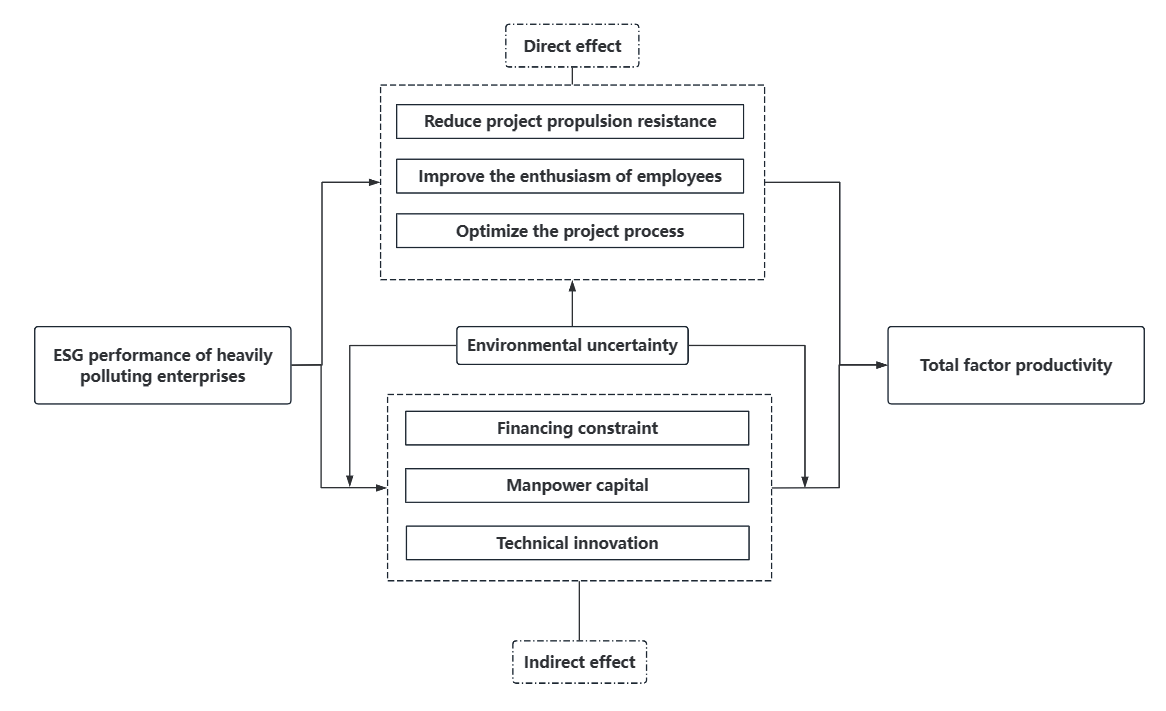
According to the Cobb-Douglas production function, capital, labor, and technology are considered the core factors directly influencing total factor productivity [20]. Capital and labor provide the essential resources for production, while the level of technology determines the efficiency with which these resources are utilized. Therefore, optimizing the allocation of capital, labor, and technology is widely regarded as a key approach to enhancing total factor productivity. It is noteworthy that a company’s ESG performance plays a crucial role in these three aspects. Furthermore, environmental uncertainty not only affects the relationship between the ESG performance of heavily polluting companies and total factor productivity but may also influence the pathways through which these two factors interact. The theoretical mechanism diagram illustrating the impact of ESG performance on total factor productivity under environmental uncertainty for heavily polluting companies is shown in Fig. 4.
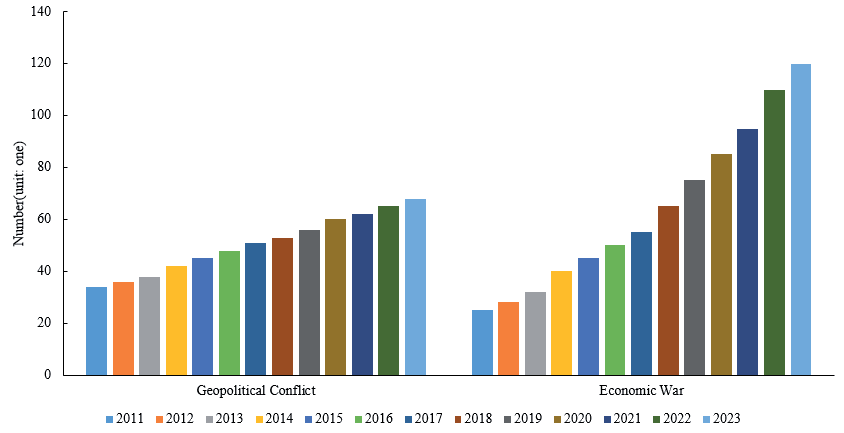
The theory of financial constraints posits that due to information asymmetry between companies and the market, the cost of external financing for companies is typically higher than that of internal financing. This discrepancy can hinder a company’s ability to upgrade equipment, innovate technologically, and develop talent, ultimately negatively impacting its total factor productivity. Notably, existing research has found that implementing ESG strategies can reduce information asymmetry with the market and alleviate financing constraints. For instance, Pedersen et al. (2021) and Guo et al. (2024) discovered that companies with strong ESG performance are more likely to gain recognition from government and financial institutions, thereby lowering their financing costs [21, 22]. This is because companies with higher ESG ratings typically exhibit stronger risk-bearing capabilities and can convey a responsible and positive image to the capital market, making it easier for them to secure funding through green bonds, preferential loans, or equity financing [23, 24]. The influx of capital can assist companies in improving resource utilization efficiency, thereby enhancing total factor productivity. Xiao et al. (2023) and Hou et al. (2024) found that sufficient funding can help companies achieve economies of scale and improve operational efficiency, further boosting total factor productivity [25, 26]. Therefore, heavily polluting companies can increase their total factor productivity by implementing ESG strategies to reduce financing constraints.
The endogenous growth theory posits that a company’s economic growth relies not only on external technology but also on internal innovation and talent accumulation. By improving working conditions, promoting fair compensation, and providing career development opportunities through ESG practices, companies can enhance employee belonging and motivation while attracting more talent. For instance, Deng et al. (2023) and Meng et al. (2024) indicates that heavily polluting companies can significantly improve their corporate reputation by enhancing their ESG performance, and simultaneously create a safe and inclusive work environment for employees, thereby becoming more attractive in a competitive talent market [9, 27]. The accumulation of high-quality human capital provides essential support for a company’s innovation and development, as well as enhances total factor productivity. Chen (2024), in a study of manufacturing companies, found that effectively integrating quality human capital resources can drive innovation, optimize resource allocation, and achieve sustained productivity growth [28]. Furthermore, implementing ESG practices enables companies to better respond to environmental changes, enhancing their learning and adaptability, which in turn boosts innovation capabilities. Zhang et al. (2024) noted that heavily polluting companies investing in ESG initiatives can improve corporate governance, clarify decision-making and responsibilities, reduce internal friction costs, and achieve more effective resource allocation and risk management, thereby promoting technological innovation [29]. The enhancement of a company’s innovation capabilities ultimately translates into increased total factor productivity. Gao et al. (2023) found that strengthening innovation capabilities can lower input costs, thereby increasing total factor productivity [30]. Therefore, heavily polluting companies can improve human capital and technological innovation through ESG practices, ultimately enhancing total factor productivity.
Drawing from these findings, this study posits the following hypotheses:
H2: Heavily polluting companies can alleviate financing constraints by improving their ESG performance, which enhances their capacity for risk-taking and subsequently improves capital allocation efficiency, thereby increasing total factor productivity, aligning with Guo et al. (2024)’s and Xiao et al. (2023)’s findings [22, 25].
H3: Heavily polluting companies can enhance their attractiveness to talent by creating a fair, safe, and inclusive work environment through improved ESG performance, which in turn enhances the companies’ market judgment and innovation capabilities, ultimately increasing total factor productivity. This hypothesis is supported by the research of Meng et al. (2024) and Chen (2024) [27, 28].
H4: Heavily polluting companies can improve their innovation ability by improving ESG performance, clarifying the distribution of responsibilities, and reducing project redundancy, thereby increasing total factor productivity, as supported by Zhang et al. (2024) and Gao et al. (2023) [29, 30].
In the context of increasing environmental uncertainty, combined with resource dependence theory, it can be observed that companies can effectively reduce the disruptions caused by external environmental turbulence and enhance their resource acquisition capabilities through the implementation of ESG practices. For instance, economic uncertainty often reduces the liquidity of capital, particularly for heavily polluting companies that face higher environmental risks. In such cases, these companies can demonstrate their resilience and commitment to long-term sustainable development by improving their ESG performance. This, in turn, enables them to secure more financing and talent, thereby enhancing their innovation capabilities and improving total factor productivity [31]. Furthermore, geopolitical conflicts may expose heavily polluting companies to risks such as rising raw material costs or supply chain disruptions. Companies with strong ESG performance can leverage their positive image to quickly find partners, thereby mitigating the impacts of geopolitical conflicts. More importantly, these companies can respond swiftly to seize market share, further enhancing their competitive advantage.
Drawing from these findings, this study posits the following hypotheses:
H5: In the context of significant environmental uncertainty, the ESG performance of heavily polluting companies can help them capture a larger market share by attracting capital, accumulating talent, and enhancing their innovation capabilities, thereby more effectively improving their total factor productivity, as supported by Vural-Yacas (2021) [31].
In summary, heavily polluting companies play a critical role in China’s industrial output and are key targets for reducing carbon emissions and advancing sustainable development. Although ESG performance offers significant advantages to these companies, the industry faces challenges such as high initial investment costs and slow returns. Current research on the economic benefits of ESG performance in heavily polluting companies is relatively limited. Furthermore, there is a scarcity of studies examining how environmental uncertainty moderates the relationship between ESG performance and economic benefits. In the international context, the ESG performance of heavily polluting companies not only affects the domestic economy and environment but also has significant implications for global sustainable development goals. As global attention to climate change intensifies, China’s green transition policies are increasingly under international scrutiny. Therefore, it is crucial to conduct in-depth research on the impact of the ESG performance of heavily polluting companies in China on total factor productivity and to explore the intrinsic mechanisms involved, as well as the moderating effects of environmental uncertainty. Such research will not only provide theoretical support for the government in formulating sound industrial policies but also help to solve emerging issues such as green supply chains, circular economy, and digital transformation, thereby helping heavily polluting companies to achieve sustainable development in a complex environment. Moreover, China’s successful experiences in ESG practices within heavily polluting companies may serve as a reference for other developing countries, thereby promoting global economic sustainable development.
Materials and Methods
Sample and Data
Due to the characteristics of heavily polluting companies, which are associated with high pollution and significant economic contributions, it is crucial to clarify the impact of their ESG performance on total factor productivity. This understanding is essential for achieving a balance between economic growth and environmental protection. This study selects heavily polluting companies listed on the A-share market from 2011 to 2022 as the research sample. In terms of data quality control, the study excludes companies marked as “Special Treatment” (ST) and those with missing observations in certain years, ultimately resulting in 7,061 annual company observations. It is noteworthy that the sample companies in this study generally possess relatively mature governance structures, which may limit the generalizability of the conclusions to non-listed companies and reduce their applicability in an international context. Therefore, future research could consider expanding the sample to include non-listed companies and international data. This approach would not only enhance the generalizability of the research findings but also facilitate comparisons of ESG performance and its economic benefits across different markets and regions. The ESG rating data used in this study is sourced from the Wind database, while the remaining data is obtained from the China Securities Market and Accounting Research (CSMAR) database.
Dependent Variable
This study selects the total factor productivity calculated using the Levinsohn-Petrin (LP) method as the dependent variable. The LP method addresses endogeneity issues by incorporating intermediate inputs (such as raw materials), effectively overcoming the sample bias and endogeneity problems associated with Ordinary Least Squares (OLS) and Fixed Effects models (FE). Furthermore, the LP method also resolves the limitation of the Olley-Pakes (OP) method, which requires investment to be greater than zero [32]. This makes it more suitable for measuring heavily polluting companies with atypical investment patterns.
Independent Variable
This study employs the ESG rating system developed by Huatai Securities to assess the ESG performance of heavily polluting companies. The system consists of three main indicators, 14 secondary indicators, and multiple fundamental indicators, focusing on ESG factors closely related to China’s market and government policies. This allows for a more accurate reflection of China’s companies’ actual performance in social responsibility, environmental protection, and corporate governance. Although the Huatai Securities rating system is tailored specifically for China’s market, it shares commonalities with global standards in its evaluation dimensions. Similar to MSCI and Sustainalytics, the Huatai rating system encompasses the three core areas of environmental, social, and governance, emphasizing corporate performance in governance structure, environmental protection policies, and social responsibility. Thus, despite its localized characteristics, the commonalities in its evaluation dimensions and methodology ensure that the findings of this study provide valuable references for the international community.
Having discussed the ESG performance measure and dependent variable (total factor productivity), the next sections will examine the mediating and moderating factors that might influence this relationship. Specifically, we explore the roles of financing constraints, human capital, technological innovation, environmental uncertainty, and control variables.
Mediating Variable
Existing research indicates that a decrease in financing constraints, along with improvements in human capital and technological innovation, can enhance a company’s total factor productivity [33- 35]. Additionally, a company’s ESG performance can influence its financing constraints, human capital, and technological innovation [36-38]. Therefore, this study examines the impact pathway of ESG performance on total factor productivity in heavily polluting companies, using financing constraints, human capital, and technological innovation as intermediary variables.
Financing constraints refer to the limitations and challenges that companies face when raising capital in the market, reflecting the alignment between a company’s financing capabilities and the external financing environment. The KZ index, commonly used to analyze the relationship between a company’s investment behavior and capital structure, is suitable for a variety of companies and geographic backgrounds, effectively reflecting a company’s financing constraints. This study uses the KZ index to measure the financing constraints of heavily polluting companies.
Human capital refers to the knowledge, skills, and abilities of employees within a company, serving as a crucial driver for improving productivity and fostering innovation. High-quality employees are often better equipped to adapt to the introduction and application of new technologies, thereby promoting technological transformation and enhancing efficiency. In this study, we use the natural logarithm of the number of employees with a bachelor’s degree or higher (plus one) and the natural logarithm of the number of employees with a postgraduate degree or higher (plus one) to measure human capital. This approach smooths data distribution, minimizes the impact of outliers, and allows for a more accurate assessment of the role of human capital in the relationship between ESG performance and total factor productivity in heavily polluting companies.
Technological innovation is a key driver of sustainable development for companies, particularly in heavily polluting companies, where advancements in technology can effectively reduce pollutant emissions and improve resource utilization efficiency. R&D expenditures and patent counts serve as important indicators of a company’s investment in and outcomes of research and development. In this study, we use the natural logarithm of utility model patent counts (plus one) and the natural logarithm of R&D expenditures (plus one) to smooth the data distribution.
Moderating Variable
Compared to macro-level indicators such as the policy uncertainty index or geopolitical risk index, abnormal sales revenue fluctuations better capture industry-level and market-level dynamics, making it particularly suitable for heavily polluting companies. Consequently, this research follows the methodology proposed by Ghosh and Olsen (2009), employing sales revenue data from the previous five years of listed companies [39]. By using Equation (1), it separately calculates the abnormal sales revenue over the past five years.
Here, Sale refers to sales revenue, and Year denotes the fiscal year. Abnormal sales revenue is derived from the residuals of Equation (1). The environmental uncertainty for listed companies without industry adjustment is calculated by taking the standard deviation of the abnormal sales revenue over the past five years and dividing it by the average sales revenue during the same period. Industry environmental uncertainty is defined as the median of environmental uncertainty of all listed companies in the same industry and in the same year, without industry adjustment. The industry-adjusted environmental uncertainty for a listed company is obtained by dividing its unadjusted environmental uncertainty by the industry environmental uncertainty. It is important to note that environmental uncertainty in China varies significantly across different companies and regions. For instance, policy-driven companies (such as energy and steel) are more affected by policy fluctuations, while competitive companies (such as chemicals) are more influenced by market demand. Additionally, the differences in market maturity and policy implementation between the eastern coastal regions and the central and western regions further exacerbate this uncertainty. Future research could explore how industry and regional differences impact the measurement of environmental uncertainty.
Control Variables
Referencing the previous research [40-42], this study chooses Total Assets (Ta), Firm Age (Age), Shareholding Concentration (Shrcr1), Net Profit (Np), Long-term Debt Ratio (Ldr), Current Asset Turnover Ratio (Catr) and Local environmental regulation intensity (Eri) as control variables. These variables impact the financial condition and market performance of companies in various ways. Ta reflects the availability and efficiency of resources, while Age influences corporate culture and resource acquisition capabilities. Shrcr1 affects decision-making efficiency and resource allocation. Np is directly related to profitability and investment capacity, and the Ldr indicates financial risk and capital structure. The Catr measures how effectively a company utilizes short-term assets to generate sales, which is particularly important in heavily polluting companies for responding quickly to market demands. Eri can affect the daily operations of heavily polluting companies, thereby interfering with their resource utilization efficiency.
The definitions of the primary variables utilized in this study are detailed in the Table 1.
Model Design
This study employs a Regression Model (2) to examine the impact of ESG performance on total factor productivity in heavily polluting companies:
where i denotes the firm index, and t signifies the year index. TFP_lpit is the dependent variable and is calculated for heavily polluting companies using the LP method, ESG_ait is the primary independent variable and represents the average ESG score from the four quarters of the preceding year for heavily polluting companies, and controlit encompasses all control variables. δi, λj, ut correspond to industry fixed effects, individual fixed effects, and time fixed effects, respectively. The inclusion of these three fixed effects is due to the differences in technological levels and market environments among different companies, allowing for a more accurate assessment of the impact of ESG performance on total factor productivity. At the same time, the individual fixed effects control for individual characteristics, while the time fixed effects eliminate the influence of macroeconomic factors. This approach not only enables us to gain a clearer understanding of the relationship between ESG performance and total factor productivity but also reduces endogeneity issues to some extent, thereby enhancing the credibility and interpretability of the research findings. εit is the error term within the equation.
Moreover, to delve into the mechanisms through which ESG performance impacts total factor productivity in heavily polluting companies, the study adopts Models (3) and (4) to assess the mediating roles played by financing constraints, human capital, and technological innovation:
Within these formulas, Middleit represents financing constraints KZit, human capital lnugeit(lnpgeit), and technological innovation lnpatentit(lnRDit), respectively. Here, β1 measures the effect of the ESG performance of heavily polluting companies on the mediating variable, β2 represents the direct impact coefficient of ESG performance on total factor productivity, and w2 indicates the impact of the mediating variable on total factor productivity after controlling for the effect of ESG performance. If β1, β2, and w2 are all significant, the mediating variable plays a partial mediating role. If β1 and β2 are significant but w2 is not, the mediating variable plays a full mediating role, and β0 = β1 + β2w2.
Furthermore, the study utilizes Equation (5) to explore the moderating effect of environmental uncertainty on the relationship between ESG performance in heavily polluting companies and total factor productivity:
Table 1.
Variable definition.
The sign and significance of μ3 in Equation determine if environmental uncertainty moderates the effect of ESG performance on total factor productivity in heavily polluting companies positively, negatively, or not at all.
Results and Discussion
Descriptive Statistics Analysis
The descriptive statistical outcomes for the relevant variables are presented in Table 2. For heavily polluting companies, the mean of total factor productivity is 8.364, indicating that these companies perform well in resource utilization efficiency. However, the minimum value of 5.403 suggests that there are still some companies that require improvement in efficiency. In terms of ESG performance, the average score is 4.118, reflecting an overall acceptable performance. However, the mean score for the environmental dimension is only 2.089, which is significantly lower than the scores for social (4.118) and governance (5.280), indicating a notable deficiency in environmental protection efforts. Additionally, the standard deviation for the environmental dimension is 1.230, highlighting substantial variability among companies, with a maximum score of 8 and a minimum score of 1, further emphasizing the extreme imbalance in environmental performance. Therefore, although heavily polluting companies demonstrate relatively good performance in governance and social responsibility, their shortcomings in environmental management require urgent attention to achieve more comprehensive sustainable development.
Basic Regression Results
To explore the relationship between ESG performance and total factor productivity in heavily polluting companies, this study conducted a systematic analysis based on different regression models, with specific results presented in Table 3. In the absence of control variables but controlling for industry, individual, and year fixed effects, the study found that ESG performance had a significant positive effect on total factor productivity at the 1% level. When control variables were further introduced into the analysis, the results still showed a significant positive correlation between ESG performance and total factor productivity (coefficient = 0.0424, p<0.01). Moreover, a more detailed analysis of the effects of ESG performance dimensions (environmental, social, and governance) on total factor productivity revealed that good performance in the environmental and social dimensions significantly increased total factor productivity. This highlights the critical roles of these dimensions in improving resource efficiency, optimizing production processes, and enhancing external relationships. However, the governance dimension did not show a significant positive impact on total factor productivity. Possible reasons include the difficulty in realizing short-term effects of governance improvements on productivity or the presence of formalized governance practices in some companies, which have yet to translate into actual productivity gains.
Table 2.
Descriptive statistics of variables.
Table 3.
Benchmark regression results.
The regression results for control variables show that Ta, Age, Shrcr1, Np, and Catr all have a significant positive impact on total factor productivity (p<0.01 or p<0.05). This indicates that economies of scale, accumulated experience, optimized shareholding structures, enhanced profitability, and efficient asset operations play crucial roles in improving corporate productivity. Although the coefficient for Ldr is positive, it is not statistically significant, suggesting its impact on productivity may be weak or uncertain. The coefficient for Eri is also positive but not significant, implying its effect on the productivity of heavily polluting companies might be complex, encompassing both the positive effects of technological upgrades and the negative impacts of increased compliance costs.
In summary, heavily polluting companies can significantly enhance total factor productivity by improving their ESG performance, particularly in the environmental and social dimensions. These improvements not only help companies adapt to increasingly stringent environmental regulations but also promote operational efficiency through technological innovation and resource optimization. However, to fully unlock the potential of the governance dimension, companies may need to strengthen the implementation and transparency of governance mechanisms to comprehensively drive productivity improvements.
Robustness and Endogenous Tests
To verify the reliability and robustness of the empirical results, this study employed three approaches to test the stability of the baseline regression outcomes, as detailed in Table 4. First, following the methodology of Xiang, Deng, and Li (2023), total factor productivity was recalculated using the OP methods [9] while keeping other variables consistent. The results of the regression analysis indicate that the ESG performance coefficients for the LP method and the OP method are 0.0521 and 0.0314, respectively, both of which are statistically significant at the 1% level. This suggests that the variation in total factor productivity calculation methods has a minimal impact on the robustness of the conclusions. Second, to test the robustness of the ESG performance variable, the quarterly median of the Huatai ESG score was used as a substitute explanatory variable, while other variables remained unchanged. The regression results showed that the adjusted ESG coefficient was 0.0285, still significant at the 1% level, indicating consistency in the positive impact of ESG performance on total factor productivity across different measurement methods. Finally, to mitigate the influence of outliers, a 1% tail-trimming procedure was applied to the dataset. The regression results after outlier exclusion indicated an ESG coefficient of 0.0397, which remained significant at the 1% level, further confirming the robustness of the findings.
To address potential endogeneity issues arising from possible reverse causality between ESG performance and total factor productivity in heavily polluting companies, this study adopted multiple strategies to ensure the robustness of results. First, the introduction of lagged variables. To mitigate the potential reverse causality, the model incorporated a one-period lag of ESG performance for heavily polluting companies. This approach ensures that changes in ESG performance precede changes in total factor productivity over time, thereby reducing the likelihood of reverse causality. The regression results in Table 5 (Column (1)) show that past ESG performance exerts a significant positive influence on subsequent total factor productivity (coefficient = 0.0215, p<0.01). Second, the instrumental variable method. Referring to the approach of Breuer et al. (2018), this study uses the average ESG score of other companies within the same heavily polluting industry as an instrumental variable to address potential endogeneity issues [43]. Using the two-stage least squares (2SLS) method, the results in Table 5 (Columns (2) and (3)) further confirm the positive relationship between ESG performance and total factor productivity. Specifically, the first-stage regression shows that the instrumental variable (average ESG score of other companies within the same industry) is significantly correlated with the ESG performance variable (coefficient = 0.696, p<0.01), confirming the relevance of the instrument. In the second stage, the coefficient of ESG performance on total factor productivity is 0.0970, significant at the 1% level, further substantiating the robustness of the positive effect. These results demonstrate that whether applying the one-period lagged ESG performance or the instrumental variable approach, ESG performance significantly enhances total factor productivity in heavily polluting companies.
Table 4.
Robustness test results.
Table 5.
Endogenous test results.
In summary, after conducting robustness checks by replacing the dependent and independent variables, excluding outliers, and performing lagged variable and instrumental variable endogeneity tests, the conclusion that the ESG performance of heavily polluting companies has a significant positive impact on total factor productivity remains valid. This indicates that heavily polluting companies can effectively balance economic growth and environmental protection through the implementation of ESG practices. However, it is important to note that this conclusion primarily applies to heavily polluting companies listed on China’s A-share market, and its applicability in a global context requires further exploration.
Heterogeneity Tests
The economic status of the industry to which heavily polluting companies belong, the level of internal competition within the industry, and the characteristics of ownership not only shape their behavioral patterns in the market and society but also profoundly influence their ability to integrate and utilize resources to enhance production efficiency and sustainability. Based on this, this study examines the impact of ESG performance on the total factor productivity of different heavily polluting companies from these three key dimensions.
Economic Position
Pillar industries play a critical role in the national economy, encompassing sectors such as manufacturing, electricity, chemical production, and metal smelting. These industries are not only significant drivers of economic growth but also have profound implications for resource consumption, environmental protection, and sustainable development. Therefore, analyzing the heterogeneous impact of ESG performance of heavily polluting companies in both pillar and non-pillar industries on total factor productivity can reveal the role of ESG strategies across different economic sectors. Based on the contributions and functional significance of various industries to the economy, the sample is divided into pillar industries, which include manufacturing, electricity and heat production and supply, chemical industries, and metal smelting, while other sectors are categorized as non-pillar industries. The results from the grouped regression presented in Table 6, Column (1), indicate that the ESG performance of heavily polluting companies in pillar industries has a significantly positive effect on total factor productivity (coefficient = 0.04144, p<0.01). In contrast, the ESG performance of heavily polluting companies in non-pillar industries also shows a significant impact on total factor productivity, albeit slightly weaker (coefficient = 0.04136, p<0.05). This suggests that, due to their central role in the national economy, heavily polluting companies in pillar industries are better positioned to optimize resources and enhance efficiency through ESG practices. Therefore, the government should formulate policies such as tax reductions and talent recruitment to encourage heavily polluting companies in both pillar and non-pillar industries to actively implement ESG strategies, thereby enhancing their capacity for sustainable development.
Degree of Intra-Industry Competition
The level of market competition within an industry influences the strategic decisions and resource allocation efficiency of heavily polluting companies. Intense market competition may impose greater pressure on heavily polluting companies, making it difficult for these companies to effectively translate ESG practices into improvements in productivity. In contrast, heavily polluting companies operating in industries with relatively low competition typically hold larger market shares and enjoy higher profit margins, enabling them to make optimal ESG investments and realize the economic benefits of their ESG strategies. Based on this analysis, this study evaluates the market competition level of the industries to which heavily polluting companies belong by calculating the squared ratio of each company’s revenue to the total revenue of the industry (Herfindahl-Hirschman Index, HHI). The sample companies are categorized into low competition (HHI above the median) and high competition (HHI below the median). Through group regression, we explore the heterogeneous impact of ESG performance on total factor productivity across different levels of market competition, with results presented in Column (2) of Table 6. The findings indicate that ESG performance has a significant positive effect on the total factor productivity of low-competition companies (coefficient = 0.0597, p<0.01), while the impact on high-competition companies is not significant (coefficient = 0.0161, p>0.1). This may be attributed to the higher market share and profit margins of low-competition, heavily polluting companies, which support efficient ESG investments and enhance the economic benefits of their ESG performance.
Ownership Characteristics
Ownership characteristics directly influence a company’s governance structure, decision-making mechanisms, and strategic orientation. State-owned companies (SOEs) are typically driven by policy objectives and bear greater social responsibilities, while non-state-owned companies (non-SOEs) focus more on market efficiency and economic returns. Therefore, studying the impact of ESG performance on total factor productivity in heavily polluting companies with different ownership characteristics is crucial for understanding the behavioral differences of companies with varying ownership structures in sustainable development. Based on ownership type, companies were classified into SOEs and non-SOEs for regression analysis. The results presented in Column (3) of Table 6 indicate that ESG performance has a significant positive effect on total factor productivity in non-SOEs (coefficient = 0.0474, p<0.01), while the effect is not significant in SOEs (coefficient = 0.0362, p>0.1). This suggests that non-SOEs, driven by market forces, are more effective at leveraging ESG practices to enhance market competitiveness and resource efficiency. In contrast, SOEs may exhibit weaker performance in translating ESG strategies into productivity improvements due to policy-driven objectives and institutional constraints, with their ESG benefits more likely reflected in fulfilling social responsibilities rather than economic outcomes.
Table 6.
Heterogeneity analysis.
In summary, for heavily polluting companies that belong to non-pillar industries or operate in sectors characterized by lower market competition or that are non-state-owned, their ESG performance has a more pronounced positive impact on total factor productivity. Therefore, the government should formulate targeted policies based on the specific factor endowments of these heavily polluting companies to fully leverage the economic and environmental benefits of their ESG practices.
Mechanism Test
Heavily polluting companies can significantly enhance their corporate image by improving ESG performance, thereby increasing their attractiveness to capital and talent. Based on this premise, this study evaluates the mediating roles of financing constraints and human capital in the relationship between ESG performance and total factor productivity in heavily polluting companies, as detailed in Table 7. The results in Column (1) show that the regression coefficient of ESG performance on financing constraints is -0.167, which is significant at the 1% level. Meanwhile, the impact of financing constraints on total factor productivity is significantly negative (coefficient = -0.0336, p<0.01). These findings align with the research of Xiang, Deng, Li, and Ren (2023), indicating that while financing constraints may hinder companies’ investment decisions, good ESG performance can effectively alleviate the negative effects of financing constraints on business operations [9], providing strong empirical support for H2. The results in Column (2) indicate that, regardless of whether measured by the number of employees with a bachelor’s degree or higher or those with a master’s degree or higher, the ESG performance of heavily polluting companies has a significant positive impact on human capital. Additionally, human capital has a significantly positive effect on total factor productivity. This indicates that good ESG performance can indirectly enhance total factor productivity by attracting highly educated technical talent, thereby confirming H3.
To improve ESG scores, heavily polluting companies need not only to increase R&D investment to reduce pollutant emissions but also to strengthen corporate governance to minimize project redundancy. These measures can effectively enhance the innovation capabilities of companies and significantly improve total factor productivity. Based on this, the study adopts a mediation effect model to explore the impact of ESG performance on total factor productivity through the technological innovation pathway, with detailed results presented in Table 8. The findings show that the regression coefficients of ESG performance on R&D investment and innovation output are 0.109 and 0.0437, respectively, both statistically significant. Furthermore, the impacts of R&D investment and innovation output on total factor productivity are significantly positive at the 1% significance level, and the direct effect of ESG performance on total factor productivity is also significantly positive. These results indicate that good ESG performance not only directly enhances total factor productivity but also further promotes productivity growth through the indirect pathway of technological innovation.
Table 7.
Results of testing the mechanism (1).
Table 8.
Results of testing the mechanism (2).
Table 9.
Results of testing the mechanism (3).
Furthermore, this study calculated the impact coefficients of the pathways related to financing constraints, human capital, and technological innovation, finding that each pathway satisfies the equation β0 = β1 + β2w2, as detailed in Table 9. This further validates the effectiveness of financing constraints, human capital, and technological innovation as mediating pathways.
In summary, heavily polluting companies can effectively alleviate financing constraints, enhance human capital, and promote technological innovation by improving their ESG performance, thereby increasing total factor productivity. Therefore, when implementing ESG strategies, heavily polluting companies should strategically convey their responsible image to the capital and talent markets, while also strengthening internal governance and enhancing technological innovation capabilities to more effectively improve their total factor productivity.
Further Analysis
Examination of Moderating Effects
This study incorporates the interaction term between environmental uncertainty and ESG performance to examine the moderating effect of environmental uncertainty on the relationship between ESG performance and total factor productivity in heavily polluting companies, with detailed results presented in Table 10. The findings reveal that after adding the environmental uncertainty variable and its interaction term, the regression coefficient of environmental uncertainty itself is 0.0547, significant at the 1% level. Meanwhile, the interaction term between ESG performance and environmental uncertainty has a coefficient of 0.0191, significant at the 5% level, confirming the positive moderating role of environmental uncertainty in the relationship between ESG performance and total factor productivity. Therefore, under higher environmental uncertainty, heavily polluting companies can significantly enhance total factor productivity by improving ESG performance. These findings provide strong empirical support for H5.
Moderating Mechanism of Environmental Uncertainty
This study examines how environmental uncertainty moderates the impact of ESG performance on total factor productivity in heavily polluting companies. Environmental uncertainty is shown to enhance the positive relationship between ESG performance and total factor productivity, but it also brings additional challenges in financing constraints, human capital investment, and technological innovation. For instance, environmental uncertainty could intensify financing constraints faced by heavily polluting companies, where companies with superior ESG performance are more likely to attract financing, leaving those with weaker ESG scores struggling to secure necessary funds. Meanwhile, environmental uncertainty may increase the capital requirements of heavily polluting companies, potentially exacerbating the negative impact of financing constraints on total factor productivity [44, 45]. Furthermore, environmental uncertainty might impact the investment in human capital within heavily polluting companies. Companies with strong ESG commitments may attract and retain talent more effectively, as employees increasingly prefer employers who prioritize welfare and development [15]. Concurrently, environmental uncertainty may heighten employees’ awareness of crises, compelling self-driven learning, which can affect the company’s productivity. Additionally, environmental uncertainty can drive companies to increase investments in technological innovation to improve efficiency and develop new products, as well as manage their resource allocation more prudently to ensure the effective utilization of resources [46]. Based on these, Equations (6)-(8) are employed to analyze these moderating effects:
Table 11.
Test results of the regulation mechanism in capital elements.
The moderating variable influences the connection between ESG performance and the mediator:
Each parameter retains the same definition as previously detailed. Integrating Equations (6) and (7) reveals that the indirect influence of ESG performance on total factor productivity in heavily polluting companies can be expressed as θ5(β4 + μ4EUit).
The moderating variable affects the connection between the mediator and total factor productivity:
Integrating Equations (3) and (8), the indirect influence of ESG performance on total factor productivity in heavily polluting companies can be depicted as β4(w6 + ζ6EUit).
Testing the Moderating Mechanism of Environmental Uncertainty
Based on Equations (6)-(8), this paper analyzes the moderating mechanisms of environmental uncertainty in the positive impact of ESG performance on total factor productivity in heavily polluting companies, focusing on three aspects: financing constraints, human capital, and technological innovation.
Test Results of the Regulation Mechanism in Capital Elements
Table 11 shows that the interaction term between environmental uncertainty and ESG performance on financing constraints is not significant, indicating that environmental uncertainty does not significantly alter the direct impact of ESG performance on financing constraints. However, environmental uncertainty significantly exacerbates the negative effect of financing constraints on total factor productivity (interaction coefficient = -0.00610, p<0.05). This shows that when environmental uncertainty rises, capital shortage will lead to the inability of heavily polluting companies to make effective investments and further reduce their total factor productivity. Therefore, although environmental uncertainty does not significantly affect the direct relationship between ESG performance and financing constraints, it indirectly enhances the positive impact of ESG performance on total factor productivity by amplifying the negative effects of financing constraints on total factor productivity.
Table 12.
Test results of the regulation mechanism in human elements.
Test Results of the Regulation Mechanism in Human Elements
Table 12 shows that the interaction term between environmental uncertainty and ESG performance on human capital is not significant, indicating that environmental uncertainty does not significantly alter the direct impact of ESG performance on human capital. However, environmental uncertainty significantly enhances the positive impact of human capital on total factor productivity (interaction coefficient = 0.0193, p<0.01). This result indicates that in an environment of uncertainty, the ability of talent to grasp market changes accurately and quickly adapt becomes a key factor in enhancing the total factor productivity of heavily polluting companies. Therefore, although environmental uncertainty does not significantly affect the direct relationship between ESG performance and human capital, it indirectly enhances the positive impact of ESG performance on total factor productivity by amplifying the positive contribution of human capital to total factor productivity.
Test Results of the Regulation Mechanism in Technological Elements
Table 13 shows that the interaction term between environmental uncertainty and ESG performance does not have a significant impact on technological innovation, indicating that environmental uncertainty does not significantly alter the direct impact of ESG performance on technological innovation. However, environmental uncertainty significantly enhances the positive impact of technological innovation on total factor productivity (interaction coefficient = 0.0186, p<0.01). This indicates that under conditions of high environmental uncertainty, the enhancement of a company’s innovative capabilities can help the company respond more effectively to environmental pressures and improve its resource utilization efficiency. Therefore, although environmental uncertainty does not significantly affect the direct relationship between ESG performance and technological innovation, it amplifies the positive impact of technological innovation on total factor productivity, thereby indirectly enhancing the contribution of ESG performance to total factor productivity in heavily polluting companies.
Table 13.
Test results of the regulation mechanism in technological elements.
In conclusion, environmental uncertainty does not moderate the impact of the ESG performance of heavily polluting companies on financing constraints, human capital, and technological innovation. This may stem from the fact that financing constraints are influenced by a multitude of factors, including environmental, social, and governance performance, internal capital structure, and market financing conditions. Regarding human capital, this phenomenon may arise because the accumulation and development of human capital are typically long-term processes that are less affected by short-term environmental uncertainties. The level of human capital in heavily polluting companies often relies more on long-term human resource strategies and investments. Finally, concerning technological innovation, a company’s capacity for innovation primarily depends on R&D resources, technological reserves, and market demand, which are unlikely to be directly influenced by environmental uncertainty. However, environmental uncertainty may amplify the negative impact of financing constraints on total factor productivity and enhance the positive effects of human capital and technological innovation on total factor productivity, thereby indirectly magnifying the positive impact of ESG performance of heavily polluting companies on total factor productivity. It is noteworthy that while this study focuses on China’s heavily polluting companies, the findings may offer broader insights for companies in other countries or industries facing environmental uncertainty. However, caution is warranted when generalizing these results, as regulatory and market conditions in different regions may influence the relationship between ESG performance and total factor productivity in varying ways.
Conclusions
The advent of ESG criteria offers a new avenue for integrating economic advancement with ecological preservation. However, the prevailing highly unstable international environment may induce a surge in short-sighted managerial behaviors, especially within heavily polluting companies, where the unique challenges of their industry could amplify the effects of increased environmental uncertainty. Furthermore, irresponsible corporate actions can reduce a company’s capability for sustainable development. Consequently, this study investigates the impacts of rising environmental uncertainty on businesses by focusing on heavily polluting companies listed in the A-share market from 2011 to 2022, exploring the influence and mechanisms of ESG performance on total factor productivity amidst environmental uncertainty. The study concludes that:
First, the ESG performance has a significant positive impact on the total factor productivity of heavily polluting companies, and this effect is particularly pronounced in pillar industries, low-competition markets, and non-state-owned heavily polluting companies.
Second, financing constraints, human capital, and technological innovation play a partial mediating role in the relationship between ESG performance and total factor productivity in heavily polluting companies.
Third, in heavily polluting companies, environmental uncertainty positively moderates the promoting effect of ESG performance on total factor productivity. Specifically, environmental uncertainty amplifies the negative impact of financing constraints on total factor productivity and enhances the positive effects of human capital and technological innovation on total factor productivity, thereby indirectly magnifying the promoting effect of ESG performance on total factor productivity in heavily polluting companies.
Based on the findings, we propose several targeted recommendations for enhancing ESG performance in heavily polluting companies, crucial for their sustainable development:
First, governments and financial institutions should prioritize funding for ESG projects, such as providing low-interest loans for renewable energy investments and offering subsidies for clean production technologies. These measures can effectively reduce the financial pressure on companies during their transition, encouraging more businesses to engage in sustainable development. Additionally, governments could establish special funds to support the research and application of innovative green technologies, promoting industrial upgrading. For example, the fiscal incentives in Germany and Denmark have accelerated the adoption of green technologies, and the Investment Tax Credit (ITC) in the United States has significantly boosted solar energy investments.
Second, when formulating ESG strategies, it is essential to consider the resource endowments and external environments of heavily polluting companies across different industries. For pillar industries, companies with low intra-industry competition and non-state-owned heavy polluters, policy guidance should align ESG performance with their long-term development goals. Governments can incentivize these companies by establishing special funds, providing low-interest loans, or tax reductions, while also enhancing the transparency of ESG information disclosure. For instance, China’s renewable energy project subsidies have significantly increased the deployment of solar and wind energy. In Canada, the Clean Growth Program provides funding support for clean technology projects, assisting companies in transitioning to sustainable practices. For non-pillar industries, companies with a high degree of competition in the industry and state-owned heavy polluters, providing technical assistance and financial support is crucial for helping them overcome challenges in their green transition.
Third, developing scientifically sound policies is crucial for guiding heavily polluting companies in the implementation of ESG strategies and managing uncertainties. While uncertainties can exacerbate financing constraints on total factor productivity, they can also amplify the positive effects of human capital and technological innovation. Therefore, governments should strengthen policy support systems, establish early warning mechanisms for environmental risks, and promote green credit, technology subsidies, and tax incentives. Furthermore, policies should encourage investment in human capital and R&D to drive innovation. For instance, Australia’s Clean Energy Finance Corporation supports renewable energy projects, providing both financial backing and fostering innovation.
While these findings are helpful in supplementing the existing literature, it is important to acknowledge the limitations of the study and outline directions for future research. First, this study clarifies the impact of current ESG performance on total factor productivity for heavily polluting companies. However, incorporating machine learning-predicted ESG performance into the model could provide a more accurate estimation of the effect of ESG performance on total factor productivity. This is because, with the rapid development of machine learning, the ESG performance predicted by machine learning may influence financing constraints, human capital, and technological innovation, which in turn can further affect total factor productivity. Secondly, the sample of this study is limited to heavily polluting companies in China’s A-share market. Including a broader range of global companies in the research and conducting heterogeneity analyses based on the specific circumstances of different countries could yield more universal and targeted conclusions. Therefore, future research should collect more global data and employ more advanced methods to clarify the impact of ESG performance on total factor productivity and the regional disparities among global companies.

