

Introduction
The Paris Agreement was signed by 175 countries on 22 April 2016, providing guidelines for global efforts in addressing climate change. In response to the Paris Agreement, the Chinese government announced in 2020 that it would strive to peak carbon dioxide emissions by 2030 and achieve carbon neutrality by 2060. Carbon emissions trading has become extremely important for countries to control carbon emissions [1-3]. In order to fulfill its commitment to emission reduction, the European Union launched the international carbon emissions trading system in 2005. In 2011, China announced the launch of a pilot carbon market. Since 2013, eight regions, including Shenzhen, Shanghai, Beijing, Guangdong, Hubei, Tianjin, Chongqing, and Fujian, have successively established carbon markets and carried out carbon emissions trading. The construction of a national unified carbon market was launched at the end of 2017. After nearly four years of planning, the national carbon market was officially launched in 2021. China has thus established the world’s largest trading market covering carbon emissions.
The continuous deepening of carbon emission trading reflects China’s strong desire to transform its economic development to green and low-carbon. However, whether carbon emissions trading can take into account both low-carbon and high-quality development and achieve a win-win situation for the environment and the economy has not yet been determined. Total factor productivity (TFP) is referred to as the efficiency of production activities over a certain period, and the continuous improvement of TFP is the fundamental path to achieving long-term, high-quality, sustainable development. Green and low-carbon development is not simply at the expense of economic growth rate, national wealth accumulation, and improvement of living standards but to achieve sustainable economic growth supported by TFP. Therefore, studying the impact of carbon emission trading on the enterprises’ TFP is particularly important. It can not only reveal the mechanism of the carbon market on microeconomic entities but also provide a theoretical basis for promoting high-quality, sustainable development and the construction of China’s unified carbon emission trading market.
There are two viewpoints on the relationship between carbon emission trading and enterprises’ TFP in the existing literature. Some scholars believe that implementing carbon emission trading increases the cost of enterprises and thus reduces their TFP. For example, carbon emissions trading will bring additional production costs to enterprises, squeeze out other research and development expenditures [4], and may have a negative impact on enterprises’ productivity [5]. Participating in carbon emission trading has suppressed the enterprises’ TFP by cost effect [6]. Other scholars believe that carbon emission trading policies can promote corporate innovation and thus enhance their TFP. For example, carbon emissions trading can stimulate enterprises to green technology innovation [7-9] or low-carbon innovation [10] and stimulate the improvement of enterprise productivity [11]. Carbon emission trading in the European Union has a positive impact on the TFP of Germany and Norway in Phase I and Phase II and also has a positive impact on Italian manufacturing enterprises with sectoral heterogeneity [12].
Existing studies have shown that carbon emission trading has no statistically significant effect on the TFP of enterprises [13]. In addition, carbon emission trading is a type of environmental regulation that may inhibit productivity [2] or improve productivity [14]. Some studies have used carbon emission trading as a representative of environmental regulation to explore the existence of Porter’s hypothesis [15]. In conclusion, researchers are divided over the relationship between carbon emission trading and enterprises’ TFP in existing research. Moreover, when explaining the impact mechanism of carbon emissions trading on enterprises’ TFP, existing research has only focused on the role played by corporate innovation. Whether there are other mechanisms of action is worthy of further study. Carbon market prices play a vital role in the carbon emission rights trading mechanism and have a profound impact on enterprises’ production decisions and business models. However, few studies have explored whether the price of carbon emissions trading will affect the relationship between carbon emissions trading and corporate TFP.
The purpose of this study is to use the data of A-share listed companies from 2010 to 2020 to verify the impact of carbon emission trading on the TFP of enterprises and its mechanism of action through the difference-in-differences method. The results show that, first, the operation of carbon emission trading can significantly improve the TFP of enterprises, and the conclusions of the study still hold after considering the endogeneity problem and robustness test. Second, the operation of carbon emission trading has improved the TFP of enterprises by improving the level of research and development and investment efficiency of enterprises. Third, for enterprises with low equity concentration, capital-intensive and technology-intensive carbon emission trading has a more significant role in promoting TFP, while for enterprises with low equity concentration and labor-intensive, this effect is not significant. Finally, the level of carbon emission trading prices will have a regulatory effect on the TFP of enterprises, and high prices are not conducive to enterprises improving TFP.
The possible innovations of this study are as follows: First, this study expands the content of the mechanism of the impact of carbon emission trading on the TFP of enterprises. Existing studies mostly focus on the impact of carbon trading on corporate innovation and cost [6-10], believing that carbon emission trading can stimulate enterprises to carry out low-carbon innovation and improve productivity. However, corporate investment efficiency and price factors in the carbon market design mechanism may also have an important impact on enterprises’ TFP. Hence, this study conducts supplementary research from the perspective of corporate investment efficiency mechanisms and uses the four-step method to verify and expand related research. Second, this study innovatively explores the regulatory effect of carbon trading prices on the relationship between carbon emission trading and corporate TFP. Each region decides on the implementation plan of the carbon emission trading policy. Therefore, the policy implementation strength in different pilot areas is different, and there are also large differences in carbon trading prices in different pilot areas. Existing studies have confirmed that the price of carbon emission rights trading has a regulatory effect on pilot policies in the opposite direction [16]. Will the price of carbon emission trading affect the relationship between carbon emission trading and the TFP of enterprises? Based on the existing literature, this study has considered that carbon market prices negatively regulate the impact of carbon emission trading on enterprises’ TFP. This finding provides a new perspective and theoretical support for the theoretical research and practice of the relationship between the carbon trading market and the TFP of enterprises.
Literature Review
As a market-based environmental regulation tool, carbon emission trading aims to promote enterprises to reduce carbon emissions, improve resource utilization efficiency, and overall economic benefits by pricing carbon emissions. In terms of their economic consequences, many studies have pointed out that the carbon trading market can effectively promote technological innovation and improve economic efficiency. The Porter hypothesis holds that appropriate environmental regulations can stimulate enterprise innovation potential. Although the cost of enterprises increases in the short term, these costs can be offset by innovation and efficiency improvement in the long run, and net benefits can even be achieved [17]. Carbon emission trading, as an environmental regulatory tool, can form an effective incentive for emission-controlled enterprises, promote technological innovation and resource allocation optimization of enterprises, and thus improve their TFP [18]. However, some studies have also found that the carbon trading market may increase the production costs of enterprises and affect their short-term market competitiveness. Environmental regulation increases the operating costs of enterprises, which may inhibit their innovation activities and thus reduce their TFP [4]. In addition, studies have shown that carbon trading policies have significantly stimulated enterprises’ innovation activities in low-carbon technologies [10] and increased the number of green technology patents of enterprises [8].
Carbon emission trading has effectively improved green innovation efficiency by increasing enterprises’ research and development investment, alleviating financing constraints, and stimulating the number of green innovation applications [19, 20]. Carbon emission trading has inhibited corporate carbon emissions, and the synergy between carbon emission trading and green financial tools further effectively reduces the carbon emissions of enterprises [21]. Moreover, participation in the carbon emission trading market is conducive to improving the sustainable development performance of enterprises [22, 23].
The continuous improvement of TFP is regarded as the fundamental path to achieving long-term, high-quality, sustainable development. In terms of factors affecting the enterprises’ TFP, recent studies show that innovation (research and development), digital transformation, information and communication technology, and climate strategy are all important. Innovation is a key factor in improving the enterprises’ TFP, and enterprises’ investment in research and development and innovation can significantly improve their TFP [24]. Broadband adoption and internet facilities affect the TFP of the Italian business sector firms [25]. Enterprises’ digital transformation impacts TFP through working capital turnover rate, human capital structure, and financing constraints [26]. The digital economy, proxied by e-government, e-commerce, and household internet users at home, has a positive and significant impact on TFP across the European regions. [27]. In addition, the external environment, including policies, market competition, and the economic environment, will also affect the TFP of enterprises. Climate policy uncertainty leads to cost escalation, reduced turnover, and constrained investment, thus affecting enterprises’ TFP [28].
The researchers have conducted extensive research on the economic consequences of the carbon trading market and the factors affecting the TFP of enterprises. Although the impact of carbon emissions trading on enterprises’ TFP has also been explored, extant studies have shown inconsistent conclusions about their relationship. Second, aside from the impact path of innovation, other action mechanisms of carbon trading policy on corporates’ TFP need to be further studied. Third, carbon market prices play a vital role in the carbon emission rights trading mechanism and profoundly impact production decisions and enterprise business models. However, few studies have explored whether the price of carbon emissions trading will affect the relationship between carbon emissions trading and corporate TFP. To address the above issues, this study will propose the following research hypotheses based on existing literature.
Research Hypothesis
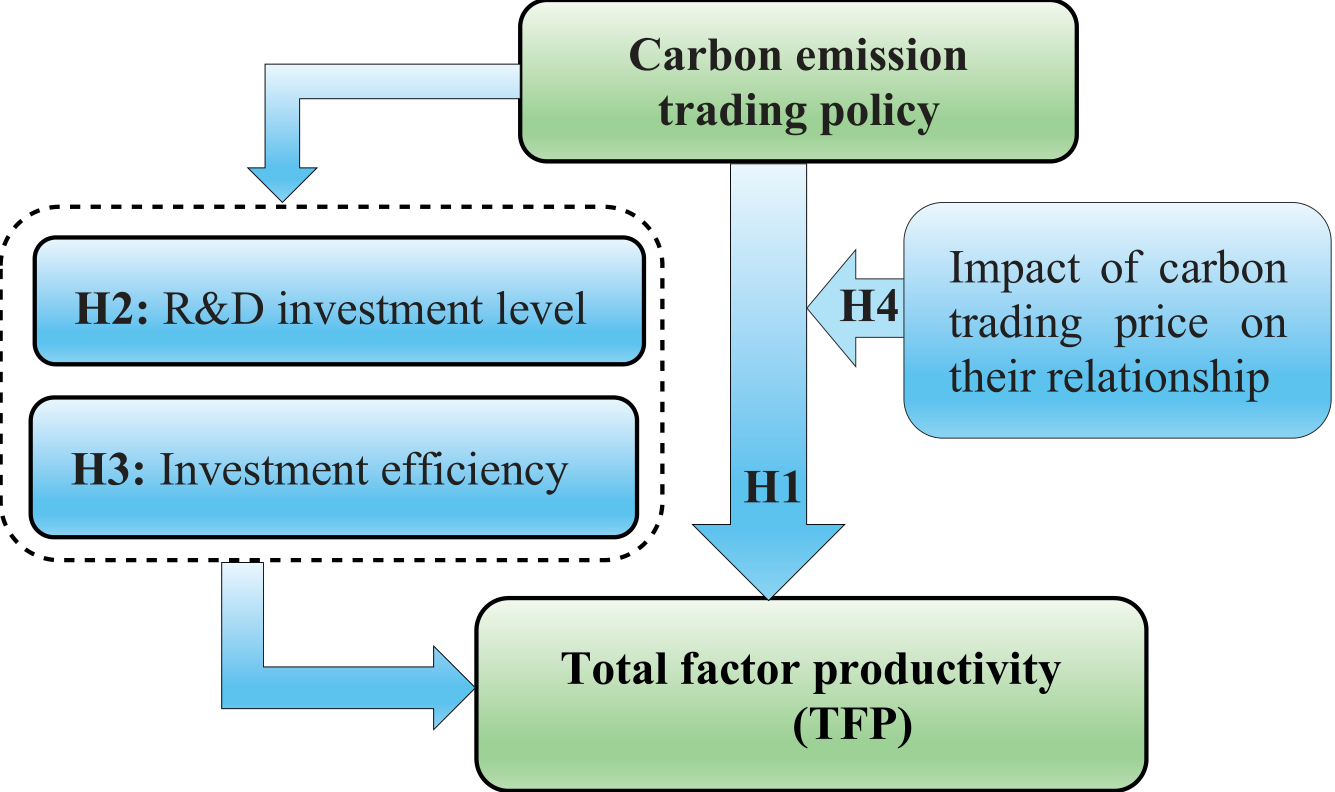
The impact of carbon emission trading policy on the enterprises’ TFP is shown in Fig. 1. The carbon emission policy internalizes the cost of carbon emissions through market-based means, allowing enterprises to consider environmental costs in economic activities, thereby prompting enterprises to carry out technological innovation and management optimization to achieve emission reduction targets and improve production efficiency. This policy not only aims to reduce carbon emissions but also hopes to improve the TFP of enterprises by promoting enterprises to carry out clean technology research and development and improve resource allocation efficiency. The Porter hypothesis believes that appropriate environmental regulations can stimulate enterprise innovation potential. Although it may increase enterprise costs in the short term, net benefits can be achieved through technological innovation and management improvements in the long run [16].
The carbon emission trading mechanism can effectively motivate emission-controlled enterprises, promote technological innovation, optimize resource allocation, and thus improve enterprises’ TFP. For example, studies have found that the Chinese carbon emission trading policy has significantly improved enterprises’ environmental protection technology innovation and thus improved productivity [15]. Another study pointed out that the carbon emission trading pilot policy has promoted enterprises’ investment in low-carbon technologies, thereby improving their TFP [29]. Although environmental regulations may increase the production costs of enterprises and affect their market competitiveness in the short term, through technological innovation and management optimization, enterprises can improve TFP in the long run and achieve higher economic benefits [30]. Therefore, this study proposes hypothesis 1.
H1: The implementation of carbon emission trading can promote the improvement of enterprises’ TFP.
From the perspective of innovation and research and development, implementing carbon emission trading policies not only provides enterprises with a fair, competitive environment but also enhances their sense of social responsibility [31]. In the context of the operation of the carbon trading market, relevant production technology innovation regulations are constantly being improved, prompting enterprises to be more forward-looking in decision-making. The operation of carbon emission trading not only provides direct economic incentives for emission reduction but also promotes technological progress and enterprise innovation through various indirect channels.
First, carbon emission trading provides enterprises with clear price signals, enabling them to foresee future carbon costs and thus actively invest in technologies to reduce carbon emissions [32]. This has been verified in the practice of the carbon emission trading system in the European Union; that is, this system has significantly promoted the research and development investment and technological innovation of enterprises [33]. Second, carbon emission trading pilot areas are usually accompanied by a series of preferential policies, such as tax exemptions, subsidies, and technical support [34], which are conducive to improving the innovation enthusiasm of enterprises and creating a good atmosphere for the sustainable development of enterprises. In addition, the competitive pressure generated during the operation of the carbon trading market also forces enterprises to constantly seek new technological breakthroughs to maintain or enhance their market position. In order to maintain competitiveness in the market, enterprises must increase research and development investment and develop efficient and low-carbon production technologies. This competition-driven innovation not only contributes to the sustainable development of the enterprise itself but also promotes technological progress in the entire industry [35]. In the long run, enterprises can reduce costs and increase profits through continuous technological innovation and improved production efficiency, thereby improving their TFP [36]. Based on this, this study proposes hypothesis 2.
H2: Implementing carbon emission trading can promote the improvement of enterprises’ TFP by increasing the level of research and development.
From the perspective of enterprise investment efficiency, Dai [37] found that factor market distortions offset the factor replacement effect of enterprise innovation by affecting enterprise innovation, production, and market entry and exit decisions, thereby reducing enterprises’ TFP. Innovation can also improve the TFP of innovative enterprises themselves, leading to the flow of production factors from non-innovative enterprises to innovative enterprises, thereby improving the TFP; however, factor market distortions can lead to factor mismatches among incumbent enterprises, distorting the decision-making of enterprises in innovation and market entry and exit, resulting in total factor productivity losses. Factor allocation is an important factor affecting enterprises’ TFP. Implementing carbon trading policies is conducive to promoting enterprises to correctly guide factor flows [38], achieve technological progress, and optimize factor resource allocation. Based on this, this study proposes hypothesis 3.
H3: Implementing carbon emission trading can promote the improvement of enterprises’ TFP by improving their investment efficiency.
Carbon market prices play a vital role in the carbon emission rights trading mechanism and profoundly impact the production decisions and business models of enterprises. By setting the price of emission rights, the carbon trading market conveys an economic signal to enterprises to reduce carbon emissions, prompting enterprises to weigh the cost of carbon emissions against operating benefits [39]. Different carbon price levels not only reflect the intensity of market constraints on carbon emissions but also affect enterprises’ TFP.
First, higher carbon prices suggest that companies must bear higher emission costs, which puts significant pressure on their production and operations [40]. In the early stages of the carbon market, companies may not have fully adapted to the new cost structure, resulting in a significant increase in operating costs. In response to this increase in price, companies may cut investment in research, development, and innovation, a strategy that may limit their ability to improve TFP through technological progress and management optimization [41]. In addition, high carbon prices may also prompt some companies to choose to reduce the production of high-carbon-intensive products, further adversely affecting their market competitiveness and long-term development [42].
Secondly, high carbon prices may make companies more inclined to short-term cost control and ignore long-term strategic investment [43]. Under the pressure of high carbon prices, companies may take short-term measures such as reducing the operation of high-energy-consuming production lines or postponing capital expenditures to cope with instant financial pressure [44]. Although these measures can alleviate cost pressure in the short term, they may weaken companies’ investment in research and development and innovation and ultimately affect their future competitiveness and production efficiency [45]. At the same time, high carbon prices may also prompt companies to rely more on purchasing carbon emission quotas to reduce emission pressure, but this strategy often fails to improve enterprises’ TFP and may instead cover up their technical and management deficiencies [8].
Therefore, the level of carbon market prices has an important impact on enterprises’ TFP. Although high carbon prices can effectively curb carbon emissions, they may also force enterprises to cut innovation investment, thereby weakening their long-term competitiveness. On the contrary, low carbon prices provide enterprises with more room for innovation and efficiency improvement, promoting sustainable development. Therefore, it is crucial to set carbon market prices reasonably, which is not only related to achieving emission reduction targets but also affects enterprises’ long-term growth and competitiveness. Based on this, this study proposes hypothesis 4.
H4: Carbon market prices negatively regulate the impact of carbon trading on enterprises’ TFP.
Materials and Methods
Data Sources
From 2013 to 2020, China has carried out pilot projects on carbon emissions trading in eight provinces and cities, including Beijing, Shanghai, Tianjin, Chongqing, Hubei, Guangdong, Shenzhen, and Fujian. Since the national formal carbon market will not start to operate until 2021, considering the short operation time of the carbon market and data availability and accuracy, this study selects 2010-2020 as the sample period. The sample data used in this study are the panel data of A-share listed companies from 2010 to 2020 and the average daily price and trading volume data of the carbon trading market from 2013 to 2020. The former is mainly derived from the China stock market & accounting research database and the Wind database, and the latter is mainly derived from the carbon trading website.
The sample data were processed as follows: First, according to the 2012 China Securities Regulatory Commission industry standards, manufacturing enterprises were classified into two levels, and the corresponding second-level industry codes were retained. Second, since financial and insurance companies are less affected by the carbon trading pilot policy, financial and insurance companies were excluded. Third, the enterprises subject to special treatment (ST) and particular transfer (PT) are removed because these companies or their financial data are abnormal. Additionally, ST enterprises that have suffered losses for more than two consecutive years are excluded. Fourth, companies with missing financial data were excluded, and data were collected manually to fill in the missing values as much as possible. Finally, the carbon trading price and transaction volume of the pilot area carbon trading market from 2013 to 2020 were manually calculated to obtain its average annual transaction price. A total of 26,755 sample observations were obtained.
Empirical Model
This study uses the method of difference-in-difference for hypothesis testing and selects enterprises in seven regions, including Shenzhen, Shanghai, Beijing, Guangdong, Hubei, Tianjin, and Chongqing, as the treatment group (Fujian started late and was not included in the treatment group here, but it was added during the robustness test), while enterprises in other regions are the control group, and 2014 is used as the policy implementation node for analysis. Second, this study uses a high-dimensional fixed effect model analysis, controls the three fixed effects of time, region, and industry, and clusters to the individual level to construct an empirical model to analyze the impact of implementing the carbon trading pilot policy on the TFP of enterprises. Finally, during the robustness test, this study uses the staggered difference-in-difference method, joins Fujian’s carbon trading market, and conducts empirical tests on the specific implementation nodes of each carbon trading market.
The baseline regression model is constructed and expressed as follows:
where TFPi,t is the explained variable, which represents the TFP of enterprise i in t year, Treati,t×Post i,t is the core explanatory variable, which represents the dummy variable of the carbon emission trading pilot. If the enterprise i is located in the pilot area of a carbon emission trading pilot, and t is in the base year or after the base year, the value is 1; if the location of the enterprise i is a non-carbon emission trading pilot area or is located in a carbon emission trading pilot area but not in the base year, the value is 0. Controlsi,t represents a set of control variables; γt represents the year fixed effect; ηi represents the region fixed effect, μ represents the industry fixed effect and εi,t is a random error term.
Variable Description
The explained variable in this study is the TFP of enterprises. This study uses the Levinsohn and Petrin (LP) algorithm to measure the TFP of manufacturing enterprises. The LP algorithm was proposed by Levinsohn and Petrin and then widely used to measure the TFP of enterprises [46]. This algorithm employs intermediate inputs as a proxy variable for unobserved productivity shocks, which could account for possible endogeneity arising from unobserved shocks. Referring to the previous studies [47], TFP value can be obtained from the following Equation (2):
where i and t refer to the firm and year, respectively, Yi,t is the total output of enterprises. This study uses annual revenues as its proxy index because industrial-added value data is not published in enterprises’ annual reports. li,t are the labor input variables. This study uses cash paid to and from employees in the enterprise cash flow statement to measure. ki,t is the capital input variable, which is expressed by the net value of fixed assets and is deflated by the consumer goods price index and fixed asset investment price index of the province where the enterprises are located. mi,t is the intermediate variable and is measured by the sum of operating costs, sales expenses, administrative expenses, and financial expenses minus depreciation, amortization, and cash paid to and for employees. θi,t is the residual item and represents the part of output growth that cannot be explained by labor input, capital input, and intermediate input, that is, total factor productivity (TFPi,t).
The core explanatory variables of this study are the pilot conditions of carbon emission trading policies represented by dummy variables, namely the interaction term Treati,t×Posti,t, which is the variable of the implementation time of the carbon emission trading pilot policy (Posti,t) times the variable of whether it is from the pilot area (Treati,t). Treati,t represents whether the enterprise i is located in the pilot area of a carbon emission trading pilot. If so, it is 1; otherwise, it is 0. Posti,t is the time dummy variable to measure the exogenous impact of the policy. Seven carbon markets were established in the second half of 2013 and the first half of 2014, so 2014 is the base year. If the time is in 2014 and later, Posti,t is assigned a value of 1; otherwise, it is assigned a value of 0.
According to existing research [18], this study selected the following control variables: the listing age of the enterprise (AGE), financial leverage (LEV), the shareholding ratio of the largest shareholder (TOP1), the financing constraint measured by size-age index (SA), the return on assets (ROA), and the cash holding ratio (CR). The descriptive statistical results of all variables are shown in Table 1.
The results of descriptive statistical analysis show that the maximum value of the TFP of enterprises is 13.00, the minimum value is 3.78, and the mean value is 8.33. There is a certain gap among enterprises’ TFP; the variance is 1.10, suggesting that the degree of dispersion is small. Regarding controlling variables, the standard deviation of the shareholding ratio of the largest shareholder and financial leverage is large, indicating significant differences in these variables among the selected sample enterprises. The other selected control variables have small differences, including cash holding ratio, enterprise age, financing constraint index of size-age, and return on assets.
Results and Discussion
Benchmark Regression Results
The results of the impact of carbon emission trading on enterprises’ TFP obtained by regression based on model (1) are shown in Table 2. Column (1) of Table 2 is the baseline regression result of the model without adding control variables, and Column (2) is the regression result of the model adding control variables. The results show that regardless of whether control variables are added, the carbon emission trading policy has statistically significantly improved enterprises’ TFP in the pilot area (p<0.01). The value of the R square increased from 0.1473 to 0.2392 after adding control variables, indicating that the model fit is better after adding control variables. The regression coefficient increased from 0.0880 to 0.1156 after adding control variables, indicating that after considering control variables, the carbon emission trading policy has a greater impact on the TFP of enterprises in the sample area. Furthermore, the regression results of this study considering time-fixed effects, industry-fixed effects, and regional-fixed effects are shown in Tables 2-4. All regression results are significant (p<0.01). Finally, this study added all control variables, controlled the fixed effects of time, region, and industry, and clustered them to the individual level for regression. The regression results in Column (5) of Table 2 show that the coefficient of the interaction term Treat×Post is 0.1033, indicating that implementing the carbon emission trading policy has significantly improved enterprises’ TFP. Hypothesis 1 has been verified, and the effectiveness of the policy implementation has been demonstrated, suggesting that carbon emission trading has significantly enhanced enterprises’ TFP, which is consistent with the conclusions of the extant study [6, 18]. However, their influence paths differ, and their research also does not consider the moderating effect of carbon market prices between carbon emissions trading and corporate TFP. This study will verify these two issues later.
Table 1.
Descriptive statistics.
Table 2.
Benchmark regression results.
Heterogeneity Analysis
To explore whether the impact of carbon emission trading on enterprises’ TFP varies depending on the type of industry, this study conducts sub-sample regression tests based on the differences in the industries to which enterprises in various provinces and cities belong. First, according to the industry codes of the national economic industry categories, this study divides the sample enterprises into labor-intensive industries, capital-intensive industries, and technology-intensive industries. The regression results in Tables 1-3 show that the estimated coefficients of technology-intensive and capital-intensive enterprises are significantly positive at a significance level of 1%, indicating that carbon emission trading has significantly improved the TFP of capital-intensive and technology-intensive enterprises. However, for labor-intensive enterprises, the estimated coefficient of the interaction term Treat×Post is not significant, indicating that carbon trading policies have no significant promoting effect on the TFP of labor-intensive enterprises. The possible reason is that from the perspective of the transmission mechanism of carbon trading affecting the TFP of enterprises, capital-intensive and technology-intensive enterprises have more advantages in optimizing capital allocation and improving innovative technologies, so the carbon trading policy has a more significant impact on their TFP.
Second, the equity structure is an important factor reflecting the corporate governance system. Different equity concentrations will lead to different production and operation decisions, affecting the production activities of enterprises. Excessive equity concentration will lead to collusion between major shareholders and management to control corporate decisions, infringe on the rights and interests of small shareholders, and reduce corporate performance. Under different equity concentrations, is there heterogeneity in the impact of the carbon trading pilot policy on enterprises’ TFP? The sample enterprises were grouped based on whether the shareholding ratio of the top five shareholders exceeded 50%. If the shareholding ratio of the top five shareholders in the enterprise is greater than 50%, it is classified as a group with high equity concentration, with a value of 1; otherwise, it is a group with low equity concentration, with a value of 0. A sub-group regression empirical test is performed.
The regression results are shown in Table 3 Column (4) and (5). For the group of low equity concentration, the estimated coefficient of the interaction term Treat×Post is positive at a significance level of 1%, indicating that the carbon trading policy significantly improves the TFP of enterprises with low equity concentration. However, for the group with high equity concentration, the estimated coefficient of the interaction term is not significant, indicating that the carbon trading policy has no significant promoting effect on the TFP of enterprises with high equity concentration. That is, the results of the heterogeneity analysis based on equity concentration show that the carbon emission trading policy can promote the improvement of enterprises’ TFP with relatively low equity concentration, while for enterprises with higher equity concentration, its promoting effect is not remarkable. The reason may be that the higher degree of equity concentration makes corporate decision-making too arbitrary, resulting in some unreasonable decisions affecting corporate production efficiency and thus affecting the sustainable development of enterprises.
Table 3.
Heterogeneity regression results.
Robustness Test
Parallel Trend Test Results
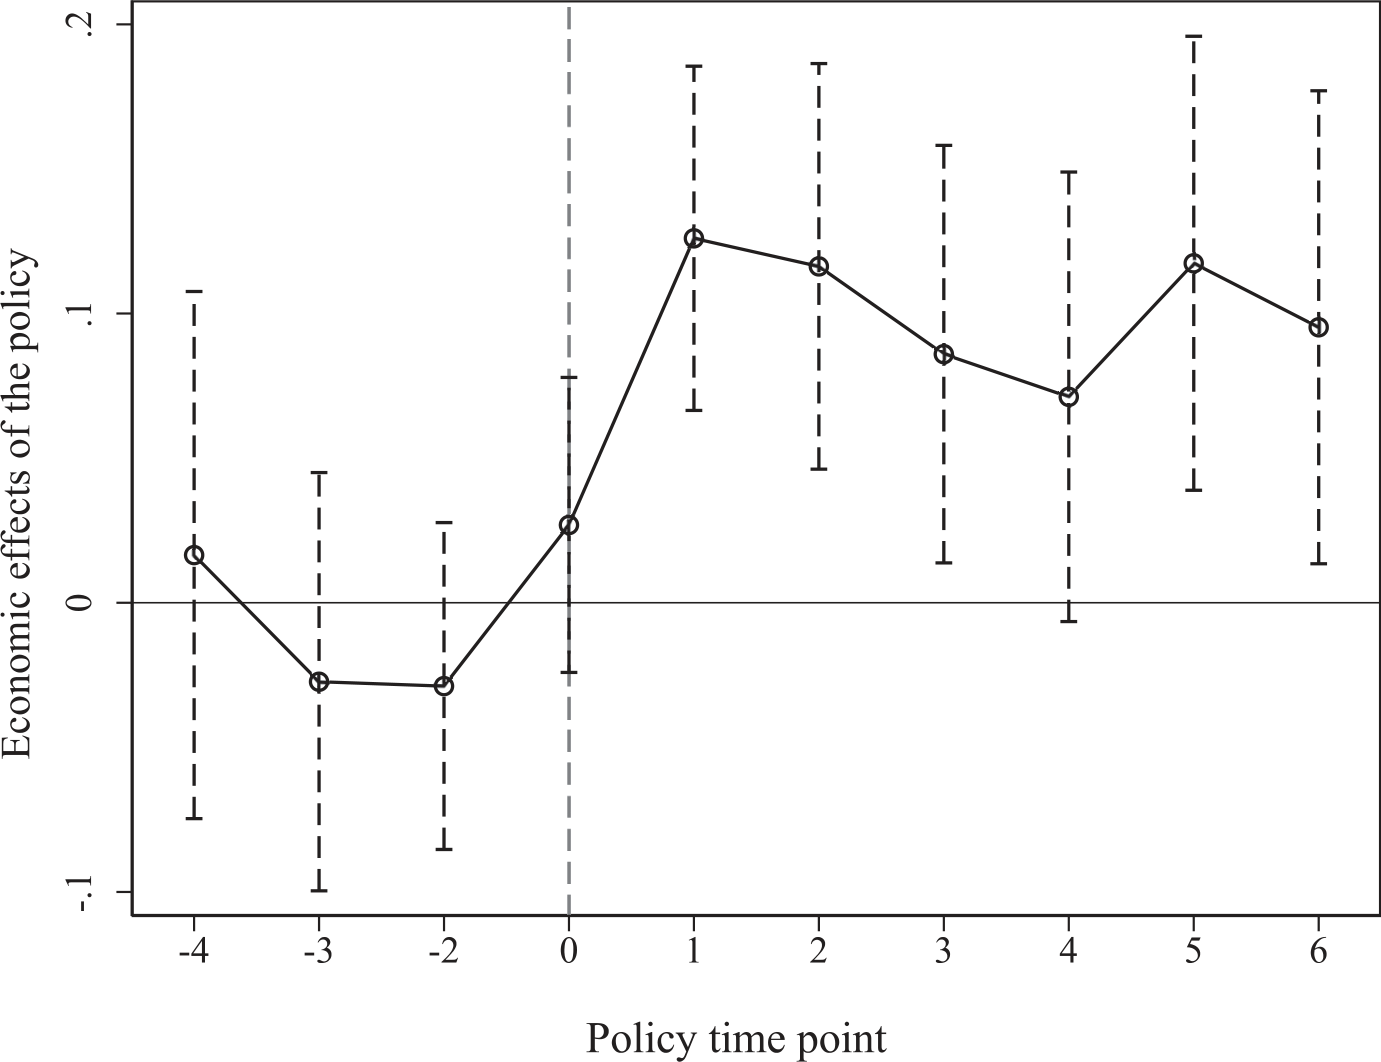
This study uses the year before the implementation of the policy in 2014 as the baseline period to test whether the TFP of the treatment group and the control group conform to the parallel trend. Fig. 2 shows the results of the balanced trend test. Before the policy was implemented, the curves all crossed the zero point, and the 95% confidence interval of the interaction term coefficient included 0, indicating that the differences in enterprises’ TFP between the carbon trading pilot areas and non-pilot areas were small, which conforms to the parallel trend assumption. The curve crossed the zero point in the year of policy implementation. After the policy was implemented, the enterprise needed a certain amount of time to adjust its production and operation decisions. Hence, after the policy was implemented, it slowly deviated from 0, indicating that the policy played a role in improving enterprises’ TFP. In 2018, the confidence interval included 0. The reason may be that the relaxation of carbon trading policy control under the complex economic environment, such as the transformation of new and old kinetic energy and the Sino-US trade war, affected the policy effect. In summary, the coefficients of the variables in each period before the policy were not significant, and they were not significant in the year of policy implementation. However, the coefficients of the variables in each period after the policy were almost significant since there may be a lag effect in policy implementation, which met the parallel trend assumption.
Placebo Test
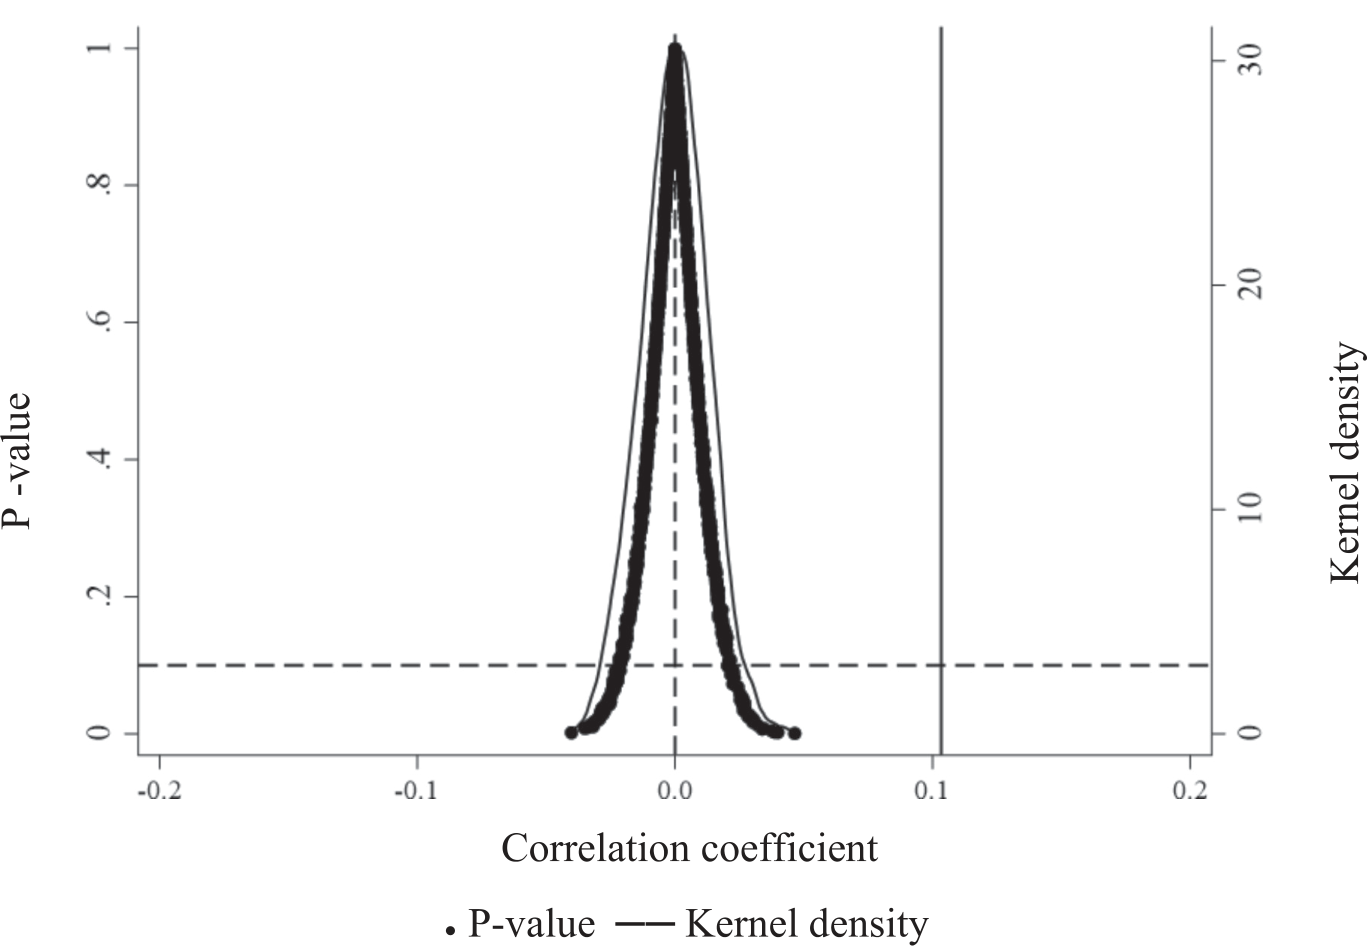
The placebo test evaluates whether the research results are affected by unobservable factors. This paper draws on existing research methods to randomize the carbon trading pilot policy shocks; that is, we randomly select the treatment group from the sample enterprises, and the rest are the control group. The redistributed groups are brought into the benchmark model for regression. We randomly select 1000 times and obtain 1000 DID estimated coefficients, as shown in Fig. 3. The horizontal axis shows the estimated coefficient of the interaction term, ranging from -0.05 to 0.05, and the estimated coefficient is concentrated around 0. From Table 2 Column (5), we can see that the vertical solid line represents the true estimated coefficient of the interaction term, with a value of 0.1033. The interaction term coefficient of the placebo test is much smaller than the true coefficient estimate. The left vertical axis is the P value, with a value range of [0-1], and the horizontal dotted line is the P value, with a value of 0.1. It can be seen that most of the points are above the horizontal line, indicating that most of the simulated data are not significant. The right vertical axis is the coefficient kernel density, which is between 0 and 30. The above analysis confirms the robustness of the empirical research results.
Propensity Matching Score and Difference-in-Difference (PSM-DID)
There are significant differences in the production and operation conditions and internal structures of enterprises, and there are significant differences in the geographical location, economic conditions, and industrial structure of various provinces and cities, which help us to obtain a relatively ‘perfect’ control group when using propensity matching scores for analysis. Based on existing research, this study selects six variables from the enterprise level, including enterprise listing age, cash holding ratio, shareholding ratio of the largest shareholder, financial leverage, return on assets, and financing constraint index of size-age, and uses 1:1 nearest neighbor matching to match.
We have controlled for the fixed effects of time, region, industry, and clusters at the individual enterprise level. The basic regression results of PSM-DID are shown in Table 4 Column (1), indicating that the coefficient of the interaction term is significant at the 1% level, and the estimated coefficient is 0.1044, which is higher than the coefficient of the ordinary regression without propensity matching, suggesting that the regression results after propensity matching scores are more obvious.
Staggered Difference-in-Difference
In fact, Beijing, Shanghai, Guangdong, Shenzhen, and Wuhan launched carbon trading policies in 2013; Hubei and Chongqing implemented carbon trading pilot policies in 2014, and Fujian joined the carbon trading market in 2016. The different implementation times of carbon trading policies in pilot cities may lead to bias in the estimation results. Hence, this study uses the staggered difference-in-difference model for robustness testing, and the model is constructed as follows:
As in model (1), Controls is a set of control variables, γt, ηi, and μ are fixed effects of time, region, and industry, respectively, and εi,t is a random error term. Treat×Post is an interaction term that divides the carbon trading pilot areas into three groups. The first group is Beijing, Shanghai, Guangdong, Shenzhen, and Wuhan. If the time is in 2013 and later, Post is assigned a value of 1; otherwise, it is assigned a value of 0. Hubei and Chongqing are the second group. If the time is in 2014 and later, Post is assigned a value of 1; otherwise, it is assigned a value of 0. Fujian is the third group. If the time is in 2016 and later, Post is assigned a value of 1; otherwise, it is assigned a value of 0. If the enterprise is located in the pilot area, Treat is assigned a value of 1; otherwise, it is 0. The estimated results of staggered difference-in-difference are shown in Table 4 Column (2). The coefficient of the interaction term is 0.0897, which is significant at the 1% level, suggesting the carbon trading policy still promotes the TFP of enterprises, and Hypothesis 1 is further verified. This result also suggests that choosing 2014 as the unified time node will not significantly impact the results of the empirical analysis.
Table 4.
PSM-DID regression results.
Instrumental Variable Test
The model of the difference-in-difference method to test the impact of the carbon trading pilot policy on enterprises’ TFP could alleviate the endogeneity problem to a certain extent. To ensure the robustness of the results, this study uses instrumental variables for testing. According to the research by Hering and Poncet [48], the annual average temperature of the sample area was selected as the instrumental variable. The data came from the China Meteorological Statistical Yearbook and were manually matched. On the one hand, the implementation of the carbon trading policy will promote regional emission reduction and thus control the temperature, satisfying the correlation condition. On the other hand, the regional temperature depends on the geographical location and climate characteristics, as well as exogenous characteristics. The two-stage least squares method is used. The core explanatory variable in the second-stage regression is the fitted value of the explained variable in the first-stage regression. Temp represents the region’s annual average temperature, and the remaining parameters and variable explanations are the same as in model (1).
Phase 1:
Phase 2:
The empirical results of the instrumental variables and the Heckman two-step method are shown in Table 5. The Kleibergen-Paap rk LM statistic at the 1% significance level is 185.931, rejecting the unidentifiable test. The Cragg-Donald Wald F statistic is greater than the 10% level critical value of Stock-Yogo, passing the weak instrumental variable test. Therefore, the selected instrumental variables meet the requirements of the endogeneity test. From the estimated results, it can be seen that the estimated coefficients of Post×temp in the first stage and Treat×Post in the second stage are significantly positive, which not only shows that the model passes the instrumental variable test and the instrumental variable selection is reliable but also shows that carbon trading policy is conducive to the improvement of enterprises’ TFP. Hypothesis 1 is further verified.
Changing the Sample Period
First, in the benchmark regression, this study uses 2010-2020 as the sample time to conclude that carbon trading policies are conducive to improving enterprises’ TFP. However, there is a certain time difference between introducing and implementing the carbon trading pilot policy, and the pilot time in different regions is different. The expected effect of the pilot region may also interfere with the results of this study. In order to further improve the robustness of the conclusion, this study examines whether enterprises are forward-looking about the carbon trading pilot policy and adjust their business strategies to respond to the policy. Referring to the research method of Cai et al. [17], we excluded 2011 and 2012 before the policy was implemented and performed regression again using the benchmark model (1). The estimation results are shown in Table 6 Column (1). After excluding the expected effect, the estimated coefficient is still significant and positive. Hypothesis 1 is further verified.
Table 5.
Instrumental variables test results.
[i] Note: *, **, *** indicate significance at the 10%, 5%, and 1% levels, respectively. Kleibergen-Paap rk LM statistic is the result of the identifiable test, and the values in brackets are the P values of the corresponding statistics. Cragg-Donald Wald F statistic is the test result of the weak instrumental variable, and the values in brackets are the 10% level critical values of Stock-Yogo.
Second, the occurrence of accidental events may also affect the effectiveness of policies. For example, the Sino-US trade friction in 2018 may cause a decrease in exports and industrial production, which will have a certain impact on the measurement of enterprises’ TFP. In order to make the estimation results more robust, we shortened the sample period to 2010-2017 and performed regression again. The results are shown in Table 6 Column (2). After shortening the sample period, the regression coefficient is still significant and positive. Hypothesis 1 is further verified.
Eliminating the Impact of Other Policies
In addition to the carbon emission trading policy, other policies implemented at the same time may also have an impact on the TFP of enterprises. For example, the emission trading pilot was implemented in 2007, and the low-carbon pilot was implemented in 2010. The implementation of these policies affects the TFP of enterprises [49, 50], so will these policies weaken the effectiveness of carbon emissions trading policies in improving corporate TFP? Therefore, in order to eliminate the interference of other relevant policies in the same period, we eliminated the regions that were significantly affected by other pilot policies and performed regression again. The results are shown in Columns (3) and (4) of Table 6. The regression coefficients are still significant, proving that the carbon trading policy will indeed have a positive effect on the TFP of enterprises, further confirming the robustness of the results.
Table 6.
Regression results in eliminating the impact of other policies.
Mechanism Test
Carbon emission rights trading policy may improve the TFP of enterprises by providing research and development (R&D) and improving enterprise investment efficiency. This study uses the mediation effect model to test the mechanism. First, for the selection of the mediating variable R&D, this study uses the annual R&D investment amount of the enterprise as the proxy variable. For selecting the mediating variable enterprise investment efficiency, we use the enterprise investment level as the proxy variable of enterprise investment efficiency; that is, the enterprise investment level is equal to capital expenditure divided by the asset stock at the end of the previous period. Capital expenditure is equal to the cash paid for the construction of fixed assets, intangible assets, and other long-term assets; capital stock is equal to the net value of depreciable tangible assets (total assets of the enterprise, net value of intangible assets, net value of goodwill). Second, when selecting the mediation model, the traditional ‘three-step method’ of the mediation effect model has obvious causal inference defects [51, 52], leading to serious endogeneity problems [53]. Based on the research [53], this study adopts the ‘four-step method’ for mechanism analysis. It adds the regression of the mediating variable to the explained variable based on the ‘three-step method’. The results are shown in Tables 7 and 8. First, this study examines the impact of carbon trading on enterprises’ TFP, and the results show a significant positive correlation. Second, this study examines the impact of carbon trading on mediating variables (investment level and R&D), and the results are all positively correlated. Third, we add mediating variables to the model and regress them, and the results show that the carbon trading policy variable still has positive significance. Fourth, the mediating variables are regressed on TFP, and the results show a positive significance. The final results show that implementing carbon trading policies has prompted enterprises to increase R&D investment and improve their innovative technology, thereby positively impacting their TFP. Hypothesis 2 and Hypothesis 3 were verified.
Moderating Effect Test
Existing studies have shown that the higher the carbon trading price, the better the effect of the pilot policy on emission reduction [16]. Whether the carbon trading price also affects the TFP of enterprises needs further exploration. Each carbon trading market needs to implement carbon emission policies according to its own situation. Therefore, the implementation strength of different pilot areas may be different. We obtained carbon market transaction price data from 2013 to 2020 from the China Carbon Trading Network. After analysis, we found that the prices of various carbon markets have different fluctuation trends over time. There are large differences in prices in different pilot areas, and these differences have shown different trends over time with the passage of carbon emission rights trading policies. Therefore, this section uses two methods, interaction terms and sub-group regression, to test the moderating effect of carbon trading prices on carbon trading policies.
Table 7.
Regression results of R&D level mechanism.
Table 8.
Investment efficiency mechanism regression results.
Table 9 Column (1) shows the regression results after adding the moderating variable and its interaction term; that is, based on model (1), we add the moderating variable carbon price and its interaction term with the original independent variable (policy variable). The estimation results show that the estimated coefficient of the policy variable is significant and positive, while the estimated coefficient of the interaction term with the moderating variable is significant and negative, which indicates that the carbon price mechanism inhibits the positive effect of carbon trading on the TFP of enterprises, and hypothesis 4 is verified.
Table 9.
Moderating effect regression results.
This study further uses the group regression method for verification. According to the annual average trading price, the seven carbon trading pilots are divided into two groups: the high-price group and the low-price group. The specific operation is as follows: we first manually sort out the daily average price announced by the carbon trading market. We then calculate each trading market’s annual average carbon price and the median annual average price of the seven carbon trading markets. Finally, the year with a higher annual average price than the median of each carbon trading market is assigned a value of 1, and the year with a lower annual average price is assigned a value of 0. According to the study [16], if a province or city is assigned a value of 1 for more than 4 years from 2013 to 2020, it will be priced as a high-price group; otherwise, it will be priced as a low-price group. Therefore, in this study, Beijing, Hubei, Shanghai, and Shenzhen are classified as high-price groups, while Guangdong, Chongqing, and Tianjin are low-price groups. We regressed the sub-sample separately, and the results are shown in Table 9 Column (2) and Column (3). The estimated coefficient of the policy variable in the high-price group is not significant, while the estimated coefficient of the policy variable in the low-price group is significant and positive, which shows that the higher the carbon trading price, the less obvious the positive effect of the carbon emission trading policy on the TFP of enterprises, that is, the carbon trading price has a negative regulatory effect on the relationship between the carbon emission trading policy and the TFP of enterprises, and hypothesis 4 is verified again.
Conclusions
Based on the data of A-share listed companies from 2010 to 2020, this study empirically analyzed the impact of the carbon trading market on enterprises’ TFP through the difference-in-difference method. The results show that, first, the implementation of the carbon trading market has significantly improved the TFP of enterprises. Second, the carbon trading policy has promoted the improvement of TFP by enhancing the level of R&D and investment efficiency. Third, the study also found that the carbon trading market has a more significant promoting effect on enterprises with low equity concentration, capital intensiveness, and technology intensiveness, while the impact on enterprises with high equity concentration and labor intensiveness is relatively limited. Fourth, further analysis shows that the level of carbon market prices has a regulatory effect on the TFP of enterprises, and high prices may weaken the positive impact of carbon trading on productivity. Based on the above conclusion, in order to further promote the development of the carbon trading market and improve enterprises’ TFP, the following policy recommendations are put forward:
First, enterprises should be encouraged to increase their investment in innovation and R&D. Studies have found that carbon trading policies have significantly improved total factor productivity by encouraging enterprises to invest in R&D in green technology and low-carbon innovation. Therefore, policymakers should formulate incentives, such as R&D subsidies and tax incentives, to encourage enterprises, especially capital-intensive and technology-intensive enterprises, to increase their investment in green technology innovation and enhance their competitiveness in the carbon trading market.
Second, the investment efficiency of enterprises should be improved. Empirical results show that carbon trading policies have promoted the improvement of enterprises’ TFP by optimizing the investment efficiency of enterprises. Therefore, it is recommended that the government introduce relevant policies to encourage enterprises to optimize capital allocation and resource management, reduce ineffective investment, and improve capital utilization efficiency. This can promote the improvement of the overall investment efficiency of enterprises by guiding funds to high-efficiency and high-tech projects.
Third, the carbon market price should be set reasonably. Studies have shown that the carbon market price has a significant regulatory effect on the TFP of enterprises, and high carbon prices may weaken the positive impact of carbon trading on enterprise productivity. Therefore, policymakers should maintain a balance when setting carbon market prices, avoiding the inhibitory effect of excessively high prices on corporate innovation and investment while ensuring that prices are sufficient to encourage enterprises to reduce emissions and innovate technologies.
Finally, from a macro perspective, a policy environment for sustainable development should be established. The government should strengthen policy coordination to ensure that the carbon trading market, innovation incentive policies, and economic growth policies support each other and form a synergy. At the same time, it should strengthen policy implementation and supervision to ensure the effectiveness and fairness of policies and create a stable and predictable market environment for the sustainable development of enterprises.
Limitations and Future Research
The study has certain limitations that can be improved in future studies. First, this study focuses on the effect that carbon emissions trading has had on TFP growth by enhancing the level of R&D and investment efficiency. However, the impacts of carbon emissions trading are multifaceted, and the TFP growth is also affected by various factors. Therefore, other impact paths, which need further research, may exist. Second, limited to the implementation time of the carbon emissions trading pilot policy, the national formal carbon emissions trading market began to operate in 2021; hence, future studies can explore the effectiveness of the national carbon emissions trading market implementation in more depth.

