

Introduction
As environmental and climate change risks have become a global challenge, the lives and health of billions of people are at risk, to counter this risk, various countries have successively adopted tough environmental regulations. Most recently, the United States proposed Clean Future Act in 2021, and the European Commission proposed the European Climate Law in 2021. China is inevitably facing serious environmental and climate change risks after experiencing rapid economic development driven by highly polluting manufacturing industries [1]. Therefore, the Chinese government have formulated dozens of policies aimed at improving the environment. Since 1979, China started to impose an emission fee, and subsequently introduced a series of environmental regulation to regulate the emission of enterprises. The implementation of China’s new Environmental Protection Law in 2015 and new Environmental Protection Tax Law in 2018 have resulted in stricter environmental regulations [2, 3]. As far as China’s environmental pollution problem is concerned, high energy-consuming enterprises are the main source of environmental pollution. This can threaten human health and the living environment. At the same time, they create enormous energy pressures. Their development requires large amounts of energy. These are not conducive to economic and social development. High energy consuming enterprises should be the focus of environmental policy. High energy consumption firms are under enormous pressure. However, stringent environmental regulations often impose additional compliance costs on firms. High energy consuming firms have had to make changes to improve their ability to compete, such as improving technology innovation [4], production shifts [5] and decreased exports [6].
Environmental regulation has a direct impact on the behaviour of firms. It has been shown that environmental regulation affects firm innovation [7], energy use [8] and the upgrading of industry institutions [9]. As a key component of firm behaviour, the efficiency of investment will directly affect firm profits. As a micro-entity of economic development, and corporate investment is an important corporate financial decision. Its efficiency is closely linked to high-quality economic growth. In the context of various environmental regulations, it is important to explore the impact of environmental regulations on the investment efficiency of high energy-consuming firms. In this paper, we investigate how the investment efficiency of high energy-consuming firms changes when they encounter stringent environmental regulations. Ideally, firms would try to utilize all positive net present value and reject those with negative net present value. However, adverse selection problems can lead to under-investment or overinvestment, thus reducing the investment efficiency of energy-intensive firms. Government action will play an important role in this. Financial investment by government will facilitate the accumulation of talent and public capital [10]. Governments can also incentivize firms to invest through tax policies, which will further influence the distribution of productivity and firm development [11]. This paper focuses on the effects of government competition. On the one hand, government competition will put some pressure on local firms. It can force them to engage in technological innovation in order to improve their competitiveness. But the impact of government competition on firms is complex. On the one hand, government competition compensates for market failures and optimizes inter-regional factor allocation. A good allocation of production factors encourages energy-intensive enterprises to invest and innovate. In addition, political competition can lead to local protectionism and market segmentation. This can be harmful to the exchange and development of enterprises and to the enforcement of environmental regulations. There are both positive and negative effects. The impact of environmental regulation may change dynamically as the level of government competition increases. This in turn will have an impact on the investment efficiency of high energy-consuming firms. No studies have yet focused on this point.
This paper uses data from Chinese firms in six high energy-consuming industries from 2011 to 2020 to explore the relationship between local government competition, environmental regulations, and investment efficiency. Our study finds an inverted U-shape in the impact of government competition and environmental regulation on investment efficiency. Tests of heterogeneity show that this boosting effect is more pronounced in high-tax areas and low-market areas. The main innovations and contributions of this paper are as follows. First, this paper widens the relevant research on high-energy-consuming enterprises. By examining the investment efficiency, this paper provides effective suggestions for Chinese high-energy-consuming enterprises to formulate investment policies. Second, this paper provides an effective reference for moderate competition among governments. This paper finds that there is a threshold for the positive regulatory effect of government competition through the threshold model. The inhibitory effect occurs when the level of government competition exceeds 2.097. Only moderate government competition will produce positive effects. Third, this paper extends the literature on environmental regulations and government behavior. Previous studies have examined the effects of governance on leader characteristics and financial reporting quality [13-16]. However, these studies ignore the combined effects of environmental regulations and government competition on investment efficiency. This paper provides new insights into how environmental legislation affects the investment behavior of energy-intensive firms by demonstrating the link between government competition, environmental regulation, and investment efficiency. At the same time this paper is important for environmental policy makers to promote the development of high energy consuming enterprises.
Literature Review
Government Competition, Environmental Regulation and Firms
Environmental protection is an increasingly important challenge to a country’s development. Economic development generates large amounts of PM2.5, which causes severe air pollution [17]. It is estimated that the economic losses caused by environmental pollution tripled from 2004 to 2013, reaching around 3% of the entire GDP [18]. The government solves the problem by formulating appropriate environmental regulations, but accordingly, it raises the external costs for companies, who have to take measures to reduce them. The new environmental policy not only can directly restrain the environmental behavior of enterprises but also can strengthen the interaction between different stakeholders, such as government and enterprises. Environmental protection is achieved by weakening the environmental problem. The impact of environmental regulation on firms has been discussed extensively in the literature. For example, Zhou (2023) [19] uses a DDD model to find that environmental regulation can promote the quantity and quality of green innovation in firms and can facilitate the transformation and upgrading of firms in highly polluting industries. Zor (2023) [20] finds that environmental regulations can facilitate the transformation and upgrading of Chinese textile companies. And this promotion can be influenced by deviant strategies. Li (2022) [21] finds that a CO2 emissions trading system increases corporate cash holdings. Ramanathan (2010) [22] found through his study that environmental protection taxes increase firms’ production costs, do not provide external benefits, and negatively affect firm innovation. As shown by Porter’s hypothesis, appropriate environmental policies will improve firm performance [23]. For example, Hattori (2017) [24] conducted a separate study on taxes in environmental policy and found that in the case of high carbon taxes, there was a boost to firm technological innovation.
Some studies also conclude that environmental regulations have no significant impact on businesses. For example, Wang (2019) [25] examined the impact of policy on green production performance in polluting industries in China and found that environmental performance did not improve significantly. Moreover, tax avoidance issues can occur for companies. As companies seek to ease the pressure of extraction caused by a strict environment [26]. The above articles have discussed extensively the relationship between environmental regulation and firms. The research direction mainly focuses on the macro impact of environmental regulation on enterprises. However, scholars have ignored the fact that environmental regulation may also affect the investment efficiency of enterprises. Adequate environmental legislation will encourage technology advances and productivity benefits. As a result, these companies expand their operations and optimise their investments. This leads to more efficient investments. Second, external pressures from environmental regulation may prompt firms to adjust their strategies and contribute to improving their longer-term competitiveness in the marketplace. Thus, environmental regulation may lead firms to shift their investment approach from blind investments in the short term to investments geared towards adapting to long-term growth opportunities. As mentioned above, environmental regulation can also have an impact on firm investment. But few articles have focused on the investment efficiency of firms.
Some studies have also analyzed the indirect effects of local protection policies and tax incentives on innovation output. But few articles discuss the impact of government competition. To the extent of competition, moderate fiscal incentives can activate capital markets. This will stimulate growth and ease the financing constraints of firms. Insufficient or excessive competition may discourage investment in energy-intensive enterprises. Insufficient competitive incentives mean that officials do not gain enough from improving their performance to offset the costs of doing so. Local governments may adopt negative strategies and become lazy in their governance. This can lead to a lack of incentives for firms to innovate and invest in the system. Excessive competition and preferential land use can have negative consequences. Firstly, it can lead to a lack of government revenue, which will limit the development potential of the region. The government may seek to increase revenue through other means in order to maintain expenditure. The government may increase its exploitation of enterprises, which would be detrimental to the efficiency of investment. Firms may expect the government to raise hidden revenues through other means in the future. This will not be effective in stimulating investment and may even induce roving tax avoidance. This paper considers both the effects of government competition and environmental regulation on the investment efficiency of firms.
Investment Efficiency
Investment efficiency measures the extent to which corporate investment activities match corporate growth and investment opportunities and is an essential indicator for judging the effectiveness of corporate investment decisions. According to the principle of maximizing shareholder value, the ideal investment decision should be to fully use all investment opportunities with positive net present value to achieve the optimal level of investment and no inefficient investment [27, 28]. However, numerous studies have shown that overinvestment, under-investment, and short-sightedness are prevalent in many firms [29]. Current research on corporate investment efficiency can be broadly divided into two perspectives; the first is analyzed from the macro level of the external governance environment. As environmental pollution itself is characterized by negative externalities, state control of corporate behavior through environmental policy to ensure coherent development of the environment and the economy will have a significant impact on the microsphere of the company, such as industry regulation [30], government intervention [31], institutional environment [32]. For example, Pasto (2012) [32] shows that economic policy uncertainty increases the difficulty of management in judging investment projects and choosing to reduce investment to avoid the failure of investment projects. Mandatory environmental policies aim to reduce the return on investment and availability of financing for polluting projects and to penalize heavily polluting firms. This measure increases the likelihood of heavy polluters being penalized by reducing information asymmetry, thus forcing regulators to increase environmental spending and discouraging overinvestment [33, 34]. On the other hand, the analysis is carried out from the micro level of governance within the firm, such as strategic behavior [35], level of governance [36], managerial competence, and background [37], and other perspectives on the impact of investment efficiency. For example, Bushman (2001) [38] argues that improving the quality of corporate accounting information can reduce the degree of information asymmetry, alleviate adverse selection, reduce the under-investment caused by adverse selection, and discourage inefficient corporate investment. However, few articles focus on the relationship between environmental regulation and corporate investment efficiency. We fill this gap with our research. It is essential to study the relationship between them to solve environmental problems.
Material and Methods
Measurement for Investment Efficiency
Following Richardson (2006) [39], we evaluate investment efficiency using the investment model shown in Equation (1).
(1)
In this equation, Investi, t is the ratio of net cash flows from the purchase of total assets by the high energy-consuming firm I in year t divided by fixed assets, intangible assets, and other long-term assets. Lev is the firm’s financial leverage. Size is the natural logarithm of the market capitalization. And cash is cash and cash equivalents scaled by total assets. Growth is the rate of sales growth. The age of a company is the time period between its current year and the year it went public. Return is the annual stock return of the company after accounting for dividends and stock splits. A number of dummy variables are utilized to account for the fixed effects of industry and year. We use the absolute value of this residual to determine the investment’s inefficiency. In addition, we treat the positive part of the residuals as overinvestment and the negative part as underinvestment.
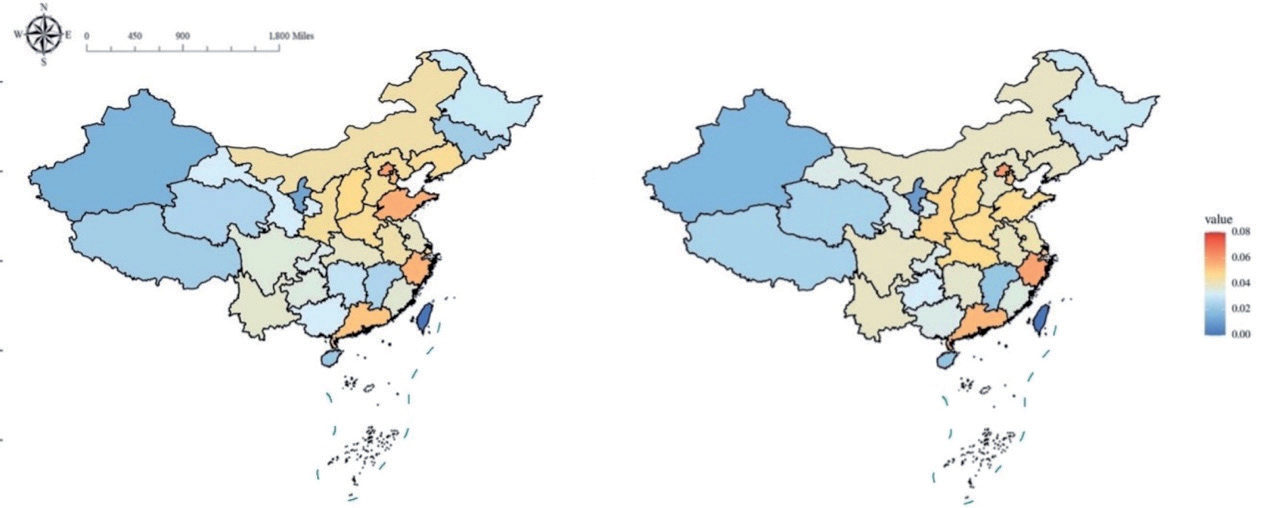
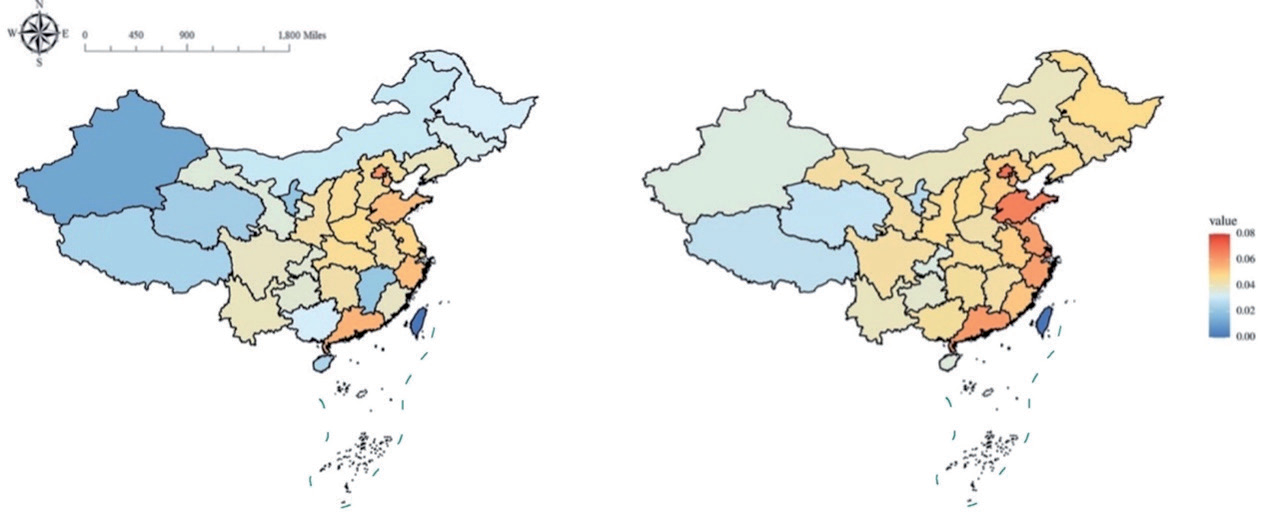
We select the provinces corresponding to high energy consuming enterprises. We then take the average of the investment efficiencies of the high energy consuming firms in the same province. The specific results are shown in Figures 1 and 2. Figure 1 (a) and (b) show the efficiency of corporate investment in each province of China in 2011 and 2014 respectively. Figure 2 (c) and (d) show the efficiency of corporate investment in each province of China in 2017 and 2020 respectively. A simple comparison shows that the efficiency of firms’ investment has increased over the years. The article further explores the impact of environmental regulation on business investment below.
Measurement for Environmental Regulation
We count the number of environment-related terms in the government’s annual work report to gauge the effectiveness of environmental regulations. In China, the government work report is an essential official document that discloses the government’s efforts in social governance throughout the year. When local governments devote additional resources to problems, such as environmental protection, the relevant section of the report will be expanded. Consequently, text analysis of government work reports using statistical keyword frequencies is a viable tool for evaluating the efforts of local governments in certain domains [5]. We undertake a textual analysis of yearly government work reports from 2011 to 2020 for all prefecture-level cities in China (including the four provincial level city, Beijing, Shanghai, Tianjin and Chongqing). Following Chen et al. (2018) [5], we conducted word frequency statistics for the following 15 keywords in the government work report. The 15 key words are “huanjing” (environment), “wuran” (pollution), “shengtai” (ecology), “huanbao” (environmental protection), “nenghao” (usage of energy), “jianpai” (emission reduction), “paiwu” (pollutant emissions), “lvse”(green), “ditan” (low carbon), “wumai” (haze), “kongqi” (air), “eryanghualiu” (sulfur dioxide), “eryanghuatan” (carbon dioxide), “PM2.5” and “PM10”. Then, we set the ratio of the total number of these keywords to the total number of words in ratio of government activity as a measure of strength local government environmental regulations.
Since the lack of direct evaluation to measure the strength of environmental regulations and changing the measure of the strength of environmental regulations can also affect the research findings when evaluating policy effects. We used the environmental regulation intensity (ERI) score established by Zhang et al. (2022) [40]. The strength of each policy’s measures and objectives was assessed by manually reading and assessing them. Each regulation is independently evaluated by multiple evaluators, and each regulation is rated on an intensity scale of 1 to 5, reflecting the importance the regulation places on certain measures or objectives. The model for the intensity of environmental regulation is then constructed as follows:
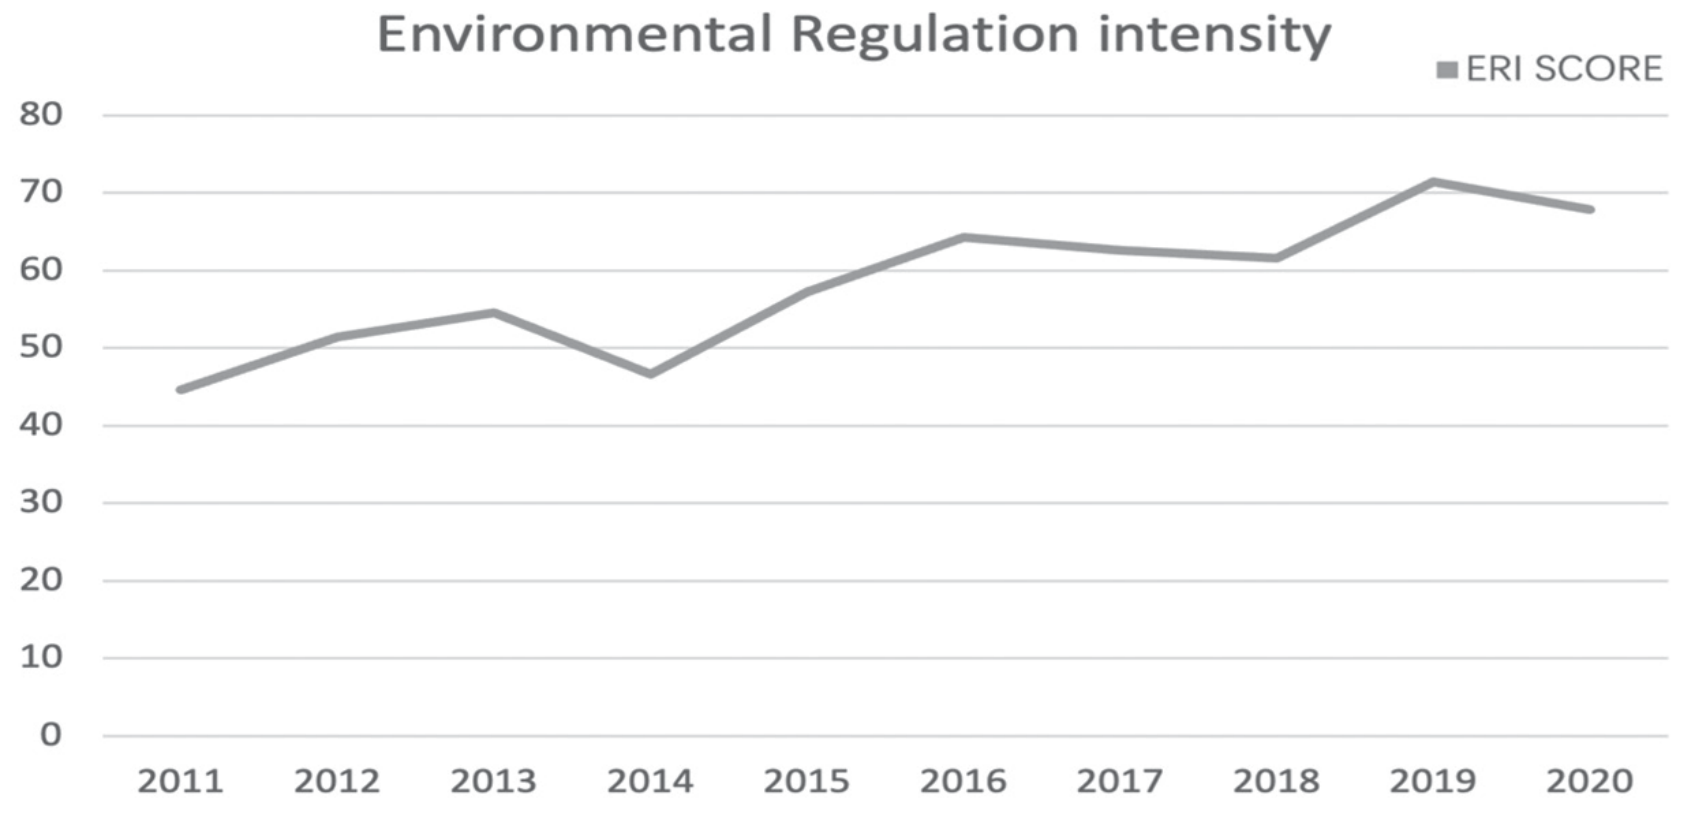
Where, t represents the year, and r represents a regulation. Mtrk is the sum of the intensity of k regulation measures in a certain year, and Otrn is the sum of the intensity of n policy objectives in a certain year. To determine the level of yearly environmental control, we averaged all ERI ratings throughout the course of the year. Additionally, we contrast the yearly ERI ratings with the severity of environmental regulation as determined by the environmental regulation terms in local government work reports. According to the findings in Fig. 3, environmental regulation in China has been much more stringent since the new Environmental Protection Law was enacted in 2015. This is indicated by the fact that environmental regulation has become significantly more stringent since 2015.
Measurement for Local Government Competition
Local government competition is a set of proactive actions taken by local governments to increase population, compete for economic resources, seek political advancement or other benefits. This paper uses the level of regional financial competition as a proxy variable to measure the degree of competition among regional governments. At the same time, the use of fiscal expenditure flow data also provides an intuitive picture of government behavioral decisions in the current period. It is possible to exclude the path accumulation and regional endowment factors implied by the stock data. LGCg,t is the level of government competition in region g in year t. feg,t and GDPg,t are the actual fiscal expenditure and regional GDP of the region in that year. fetand GDPt are the national fiscal expenditure and GDP in that year. The indicator reflects the relative intensity of the regional government’s fiscal competition. The higher the value of the indicator, the greater the degree of fiscal competitiveness of the region.
Control Variables
To assess the impact of government competition, environmental regulation on the investment efficiency, we also examine characteristics such as firm size (SIZE), return on assets (ROA), the ratio of market value plus total liabilities to total assets (TOBIN Q), cash on hand (CASH), Besides, we also control the city-level information. Industry structure (Struct). Measured by secondary industry/GDP. Level of economic development (Lev). Measured using the real GDP per capita of each city.
Empirical Models
The primary panel regression model is constructed to verify the above tests with the following equation:
In formula (6), Investi,t shows the level of investment efficiency of high energy consumption firms in the period t , ERi,t depicts the regulatory intensity of ER in the period t , Controli,t represents the control variable, vi symbolizes the spatial fixation effect, κt represents the time-fixed effect, and εit represents the term for random disturbance. In order to weaken the effects of covariance and extreme values, we logarithmize the variables in the model.
To test the impact of local government competition on environmental regulation and investment efficiency of high energy-consuming firms, we constructed the following model:
To avoid various cointegrating issues, the interaction items are decentralized.
Sample Selection
This paper conducts an empirical study using data on Chinese listed firms with high energy consumption from 2011 to 2020. In terms of industry selection, we have selected six major high energy-consuming industries based on China’s 2010 National Economic and Social Development Statistics Report. They are petroleum processing industry, coking and nuclear fuel processing industry, chemical raw materials and chemical products manufacturing industry, non-metallic mineral products industry, ferrous metal smelting and processing industry, non-ferrous metal smelting and refining industry, and electricity and heat supply industry. The data are mainly obtained from the State Intellectual Property Office, the Annual Reports of Listed Companies, the China Urban Statistical Yearbook and the China Energy Statistical Yearbook. We measure environmental protection expenditure from the Chinese Research Data Services Platform (CNRDS). The Chinese Stock Market and Accounting Research Database is used to collect additional financial data about China-listed corporations. The Socioeconomic Data and Applications Center was consulted for information on air quality. Next, we remove observations from the first-year initial public offering because a stock’s price fluctuates sharply in that year. In addition, we exclude companies receiving treatment including ST, *ST and PT. Finally, we remove companies whose total assets exceed their total assets and cases with missing variables. Our final sample consists of 425 firm-year observations. To eliminate the outlier problem, we minorize the continuous variables at the 1% and 99% levels. Table 1 shows the results of descriptive statistics of the variables. We can see that there is a huge difference in investment efficiency between high energy consuming firms. The difference in the intensity of environmental regulation and the intensity of government competition between cities is also very large. In order to better promote the sustainable development of high energy-consuming enterprises, our study is necessary.
Table 1.
Descriptive statistics
Results and Discussion
Basic Model
Table 2 shows the results of regressions examining the impact of environmental regulatory measures on investment efficiency. Column 1 does not include control variables. Column 2 does not control for year fixed effects. Column 3 is the full model. The adjusted R-square for the full model is 0.057, indicating that our regression model explains about 5.7% of the inefficiency change. The coefficients on environmental protection expenditures are all negative indicating that firms with higher environmental protection expenditures are more likely to experience higher investment efficiency in the future. The coefficient on the square of ER is negative and significant. This indicates that in the long run environmental regulation reduces the investment efficiency of high energy consuming firms. A possible reason for this is that environmental regulations can give firms an incentive to innovate in the short term. Firms faced with stringent environmental regulations will continue to improve their level of innovation in order to avoid being penalized by environmental regulations. In the long run, this puts enormous pressure on energy-intensive firms. High-energy-consuming enterprises spend more money and energy on technological innovation. At the same time, some small and medium-sized enterprises may go bankrupt due to the huge economic pressure. This is not conducive to the improvement of investment efficiency. The coefficient on LGC is positive and significant. the coefficient on the interaction term between LGC and ER is positive and significant. This suggests that environmental regulation also positively affects investment efficiency through local government competition. The means and extent of government competition, the stage and pattern of regional economic development can affect the promotional effects of environmental regulation. When the government adopts positive competition instruments, mainly through the introduction of active support policies, government competition will lead to a revitalized market. This helps to optimise financial support, diversify investment risks for firms and accelerate capital flows for R&D. This will contribute to the enforcement of environmental regulations and the investment efficiency of high energy-consuming firms.
Impact of ER on Overinvestment and Underinvestment
In the ideal case, businesses’ investment decisions should only be influenced by their investment prospects. Inefficient investment, which may be divided into two scenarios – overinvestment and underinvestment – occurs when businesses’ investment levels diverge from the ideal level. We replicate the baseline regression using overinvestment and underinvestment as the dependent variables in Equation (4), respectively. Table 3 shows the results. Column (1) shows that the coefficient of EX is negative and statistically significant at the 1% level. Its value is -0.0021 (t-value = -3.14), indicating that environmental protection expenditure would inhibit the over-investment. In Column (2), the coefficient of ER is insignificant for the Under-Invest, implying that the environmental protection expenditure has no substantial effect on the under-investment. Combining these results, stricter environmental regulations improve corporate investment efficiency by inhibiting over-investment. The probable reason is that some high energy-consuming firms aim to maximize their own interests, and they put more capital into enterprise scale-up and production. Although these excessive investments can create huge gains in the short term, they are not conducive to the improvement of investment efficiency in the long term. Environmental regulations will force firms to put more capital into technological progress and industrial upgrading.
Table 2.
Base regression results.
Endogeneity Tests
First, we alleviate the estimate bias induced by variables that were excluded by including a number of new control variables. According to previous studies the personal characteristics of the CEO or Director chairman can affect the efficiency of corporate investment [41, 42]. The CEO or chairman of the board of directors with characteristics react differently to environmental regulations, which can affect business investments. Thus, our results could be due to executive personal characteristics rather than environmental protection expenditures. To the baseline regression model, we include CEO-Chairman duality (DUALITY), independent directors (INDDIREC), gender (FEMALE), and social connections (CONNECTION) of CEO-Chairman. Table 4 summarizes the findings. The coefficient is considerably negative, indicating that after adjusting for these factors, our findings are reliable.
Finally, we perform the propensity score matching (PSM) regression to address the potential sample selection bias. The median of ER is selected as the breakpoint. The samples whose ER exceed the quantile of 50% constitute the group of while the other samples belong to the control group. The model calculates propensity scores for all control variables, and the 1 to 1 matching of the closest neighbor is used to get the final control group sample. The first-step logit regression findings are given in Column (1). We regress using the samples that were successfully matched in the second phase. Column (2) of the report the outcomes of the second stage. At the 5% level, the coefficient of ER is 0.0042, which is still highly positive and the interaction term between LGC and ER was also significantly positive. The outcomes are in accordance with the preliminary outcomes that we previously published.
Table 4.
Changing control variables.
Environmental Tax Differences
Next, we explore the differences between areas with high and low environmental protection tax. Environmental protection tax law is an essential part of environmental regulation, and environmental protection tax, as a stricter means of environmental regulation, has more vigorous legal enforcement and coercive power. However, the current tax rate of environmental protection tax in China is low overall [26]. In very few areas, instead of having an environmental protection effect, it may aggravate environmental pollution behavior. Based on the current environmental protection tax rates, China’s 31 provinces can be divided into high tax rate regions and low tax rate regions. We have divided the sample based on the region of the province where the company is based. For example, if the company is in a high tax rate region, it will be classified in the high tax rate group. The results in Table 6 show that the coefficient on ER and interaction items for ER and LGC have a significantly higher value in the high tax rate sub-sample. Taken together the significant differences in these regression results suggest that environmental regulation significantly reduces investment inefficiencies when firms are in high tax areas. The possible reason for this is that firms face greater environmental pressures in areas with high tax rates. Firms need to pay more money to the government. In order to minimize the additional expenses, firms in the region have to innovate to improve themselves. Therefore, the promotional effect of environmental regulations is more obvious in high-tax regions. The above results further support our conclusion
Table 3.
Further tests of underinvestment and overinvestment.
Table 5.
PSM regression.
Table 6.
Differences in environmental taxes.
Regional Economic Differences
Last, we explore the effect of regional economic differences on the relationship between environmental regulations, local government competition and firm investment efficiency to test whether investment inefficiencies are caused by regional economic differences. In China, the degree of marketization differs significantly between the central and western regions and the eastern regions. According to Chen et al. (2020) [33], places with a higher degree of marketization have more efficient corporate investment. The degree of economic development of each province, region, and municipality directly under the Chinese central government is split into three segments, according to the National Bureau of Statistics of China. The sample is then split into central, western, and eastern areas according to how each region is marketed. The findings in Table 8 show that for ER and interaction items for ER and LGC are statistically significant, indicating that the impact of environmental regulation and on investment efficiency is primarily felt by businesses in regions with a lower degree of marketization. Regional economic disparities have little impact on this conclusion.
Table 7.
Differences in marketability.
Threshold Model
Environmental regulation may have different effects on the investment efficiency of high energy consuming firms under different levels of local government competition. There is a ‘threshold effect’ of the level of local government competition. In this regard, the following threshold model is constructed.
Table 8.
Threshold estimates and model estimation results.
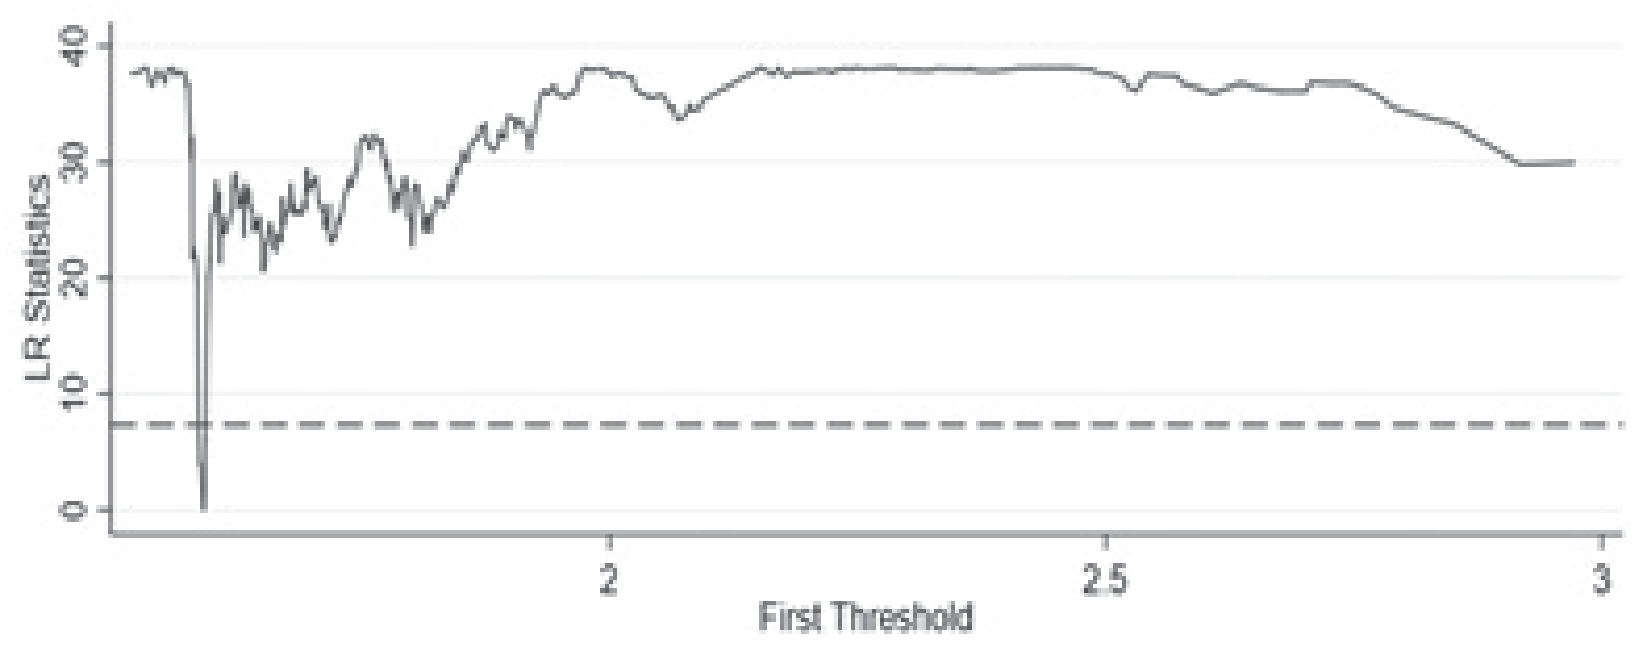
LGCi,t is the threshold variable, γ is need to be estimated, and I(⸱) is the indicative function. The results are presented in Table 8 and Fig. 4, which shows that the single threshold is significant at the 5% level, with a threshold estimate of 2.097, but the double and triple threshold tests are not significant. Therefore, there is a single threshold effect between ER and investment efficiency when local government competition is used as the threshold variable. The effect of ER on investment efficiency is different for different levels of local government competition. It is a positive contribution when the level of local government competition is less than 2.097. The coefficient for LGC becomes -0.03 when the level of LGC crosses the threshold. The possible reason for this is that when the level of local government competition is low, a rational layout of environmental regulations and local government competition can improve investment efficiency. When local government competition reaches a certain level, local governments will impose higher technological standards on energy-intensive firms. Higher standards mean more environmental expenditures. This will have a disincentive effect on firms with lower levels of knowledge. There is also the possibility of unhealthy competition such as corruption. The presence of corruption will discourage leaders from investing. At the same time, some firms may avoid the penalties of environmental regulation by taking refuge with officials. This is not conducive to the improvement of the investment efficiency of a firm.
Additional Analysis
In this section, for providing more evidence of a causal relationship between environmental regulation and business efficiency, we use the strength of regulation for additional analysis. Next, we create a difference in the difference in differences for estimate approach using the new Chinese environmental law as a quasi-natural experiment. The new Environmental Protection Law has been officially implemented on January 1, 2015. Next, the NEPL reinforces the environmental punishment for and environmental protection responsibilities of governments and further significantly increases the environmental protection cost of companies. First, companies must raise their investment in environmental protection in order to comply with environmental compliance regulations [19, 20]. In addition, the continued strengthening of the application of the daily penalty and the penalty without superior, has significantly increased the cost of business violations. Next, we use the NEPL as a quasi-natural experiment, testing the effects of environmental regulations on the efficiency of business investment. Since the NEPL is a national environmental regulation, it is difficult to identify an appropriate “monitoring group “ to conduct a DID strategy to capture variations in business investment at both in the and in the space. Consider that the efficacy of environmental legislation might differ between polluting and non-polluting industries. To address these issues, we construct a difference-in-difference-in-differences (DDD) strategy by adding a third variable, “polluting industry”, based on the principles of the DID approach. Additionally, it assisted us in overcoming the demanding conditions of the presumption of a consistent trend between the control and treatment groups. We defined three types of change. Temporal change, urban change and industrial change for the purpose of DDD model estimation. Firstly, temporal variation was defined as the change following the implementation of the National Environmental Protection Act by the central government. Second, urban variation was defined as the variance in municipal governments’ environmental enforcement vigor. Finally, industrial variation is defined as the distinction between industries with high and low levels of pollution. To develop our estimating model in accordance with the following equation.
(7)
Table 9.
Quasi-natural experiments.
Table 10.
Overinvestment and underinvestment.
Where Inefficiencyi,j,c,t is the measurement of the investment efficiency of firm i in industry j in city c in year t; Intensityc,t is the measurement of the strength of the environmental regulation in city c in year t; Postt is a dummy variable to measure the before-and-after the NEPL, and it equal to 0 before 2015 and 1 for 2015–2020; Pollutionj is another dummy variable that takes the value of 1 if the firm belongs to a polluting industry1. Controlit denotes a range of firm-level control variables that may affect investment efficiency, and all control variables are consistent with the baseline model. We also control the year-fixed and industry-fixed effects and use firm-level clustering robust standard error for estimating. The coefficient of Intensity × Pollution × Post estimated by the DDD model indicates the effect of NEPL on investment efficiency by polluting firms.
The results of the DDD regression are reported in Panel A of Table 9. In Column (1), the coefficient of Intensity × Pollution × Post is negative and significant at 10% level. This conclusion implies that the adoption of the new Environmental Protection Law has greatly boosted the investment efficiency of polluting sectors in cities with stringent regulations. Column (2) presents the result of a parallel trend test. Before the adoption of the new Environmental Protection Law, the coefficients on the interaction terms are not statistically significant, but they become negative and significant when the NEPL is implemented. Prior to the introduction of the NEPL, the findings of the parallel trend test suggest that there was no significant difference in investment efficiency between treated and matched control enterprises. In Column (3) of Panel A, we employ placebo test to rule out the possibility that the documented effect of investment efficiency is driven by spurious correlation in our sample. we randomly assign a placebo treatment group. We estimate our baseline regressions using the pseudo treatment instead of true treatment. Column (3) demonstrates that the coefficient of pseudo treatment is not statistically significant and that the amount of pseudo treatment’s influence on investment efficiency is substantially less than that in Columns (1) and (2). (1). Overall, the DDD model test findings support our premise that tight environmental legislation boosts the investment efficiency of corporations.
In the previous section we verified that ER can discourage overinvestment by firm. To verify the consistency of our conclusions under the DDD mode, in this section, we use a DDD model to verify the effect of environmental regulation on overinvestment and underinvestment among firms among polluting industries in highly regulated cities. As shown in Table 10, the coefficient of Intensity × Pollution × Post is negatively significant for Over-Invest, indicating that environmental regulation would inhibit the overinvestment. In Column (2), Intensity × Pollution × Post shows an insignificant coefficient, implying that environmental regulation has no substantial effect on the under-investment. The above series of empirical results indicate that environmental regulation can improve firm investment efficiency by discouraging over-investment, the result is consistent with our previous findings.
Table 11.
More tests.
Corporate investment efficiency may also be affected by other environmental regulation policies during the same period, which may result in an estimation bias. In Panel A of Table 11, we focus on three events: environmental protection inspection, action for prevention and treatment of air pollution, and the pilots of carbon emissions trading. First, we control for the effect of environmental protection inspection. Environmental inspections have significantly increased the pressure on firms to reduce pollutant emissions which increases firms’ compliance costs, leading to an overestimation of our estimates. Column (1) of Panel A reports the results after the control environmental protection inspection. The coefficient of Intensity × Pollution × Post remains negatively significant. Next, we consider the effect of action for the prevention and treatment of air pollution. Column (2) reports the results, the coefficient of Intensity × Pollution × Post is consistent with the previous. Finally, we test the impact of the pilots of carbon emissions trading. In 2011, China implemented carbon emission trading pilot schemes in seven areas2. As a market-oriented environmental regulatory tool, carbon emission right is considered a new type of “asset” that is directly related to the investment performance of firms and therefore may also affect our estimation results. In Column (3), we control for the impact of the pilots of carbon emissions trading, the coefficient of Intensity × Pollution × Post remains negative and significant. In Panel B of Table 10, We perform more robustness tests. Firstly, to control the municipal and provincial heteroscedasticity effects between groups and autocorrelation effects within groups on our estimates, we cluster the standard errors by city in Column (1) and by province in Column (2) of Panel B, the triple interaction terms are negative and significant at the level of 10%. Next, to exclude the effect of time-varying provincial characteristics on the results, we control province-year fixed effects in Column (3), and coefficients of the triple interaction terms remain consistent with previous regression results. The results of the various tests in Table 10 further confirm our hypothesis.
Conclusions
Using data on Chinese high energy-consuming firms from 2011 to 2020, we explore the relationship between environmental regulation, local government competition and investment efficiency. Unlike previous studies, we provide a comprehensive discussion of the relationship between the three by using threshold modeling and DDD experiments. The empirical results show that strict environmental regulation can improve firms’ investment efficiency by discouraging excessive investment behavior. Strict environmental regulation will increase the cost of environmental compliance for firms, which will lead managers to invest cautiously. As a result, firms’ over-investment behavior will be reduced. Local government competition can positively moderate the contribution of environmental regulation to investment efficiency. However, this effect is non-linear. When the level of local government competition exceeds 2.097, it has a negative impact on investment efficiency. We find that the contribution of local government competition and environmental regulation to the efficiency of business investment is more pronounced in areas with high environmental taxes and low marketisation. Finally, we treat the implementation of the new Environmental Protection Law as a quasi-natural experiment. Then, we use the difference-in-difference-in-differences model to test the investment efficiency of firms in polluting industries in highly regulated cities after the implementation of the new Environmental Protection Law. The estimation results of the DDD model provide evidence for our conclusion. However, this paper still has the following shortcomings. Environmental regulation is categorized into command-and-control environmental regulation, market incentive environmental regulation and voluntary participation environmental regulation. Different environmental regulations may have different impacts on high energy-consuming enterprises. This will be the next issue we need to explore.
Based on these findings we make the following suggestions. First, environmental regulation will have a positive impact on the investment efficiency of energy-intensive firms. China can appropriately increase the intensity of environmental regulations. However, China’s environmental regulation should focus more on measures that reduce firms’ costs. This will stimulate investment potential while regulating corporate behavior. China should avoid overly strict environmental regulations. This could discourage energy-intensive companies from investing. Second, the government should set up integration mechanisms that complement each other both horizontally and vertically. The optimization of the regional economic development model should rely on the synergistic development of economic zones. The government should fully utilize the positive effects of competition. Local governments should strengthen communication and establish mutually beneficial mechanisms for knowledge exchange and cooperation. Thirdly, China will give better play to the demonstration role of advantageous regions. High-tax regions with effective environmental regulatory policies can realize positive spatial spillover effects. This raises the level of green technology in neighboring regions. This will further encourage firms with low investment efficiency to improve together. Relevant departments should further increase publicity efforts to promote the positive development of inter-regional firms.

