

Introduction
Reducing harmful emissions, including greenhouse gases, has attracted widespread global attention. The COP28 Conference underlined the need for a gradual, just, and orderly transition away from fossil fuels, committing to tripling renewable energy capacity and doubling energy efficiency by 2030. Academic research has also focused on factors that influence the achievement of low-carbon goals, such as improved energy efficiency [1], increased consumption of renewable energy [2], use of energy-efficient products [3], eco-innovation, and political and financial stability [2]. In China, there has been increased public focus on climate change and harmful emissions. In response, the government has implemented environmental policies to combat environmental damage. Among these policies, policymakers started to introduce green finance. Banking and financial institutions are required to integrate environmental and social risks into their credit operations. Within this framework, if banks strictly consider environmental risks as an important condition for socially responsible lending, firms with high environmental risks, such as significant hazardous gas emissions, may face higher default risks due to cash flow uncertainties. Consequently, such firms may encounter rising debt financing costs and reduced access to financing, intensifying the challenges of raising capital.
This study integrates traditional neoclassical theory with agency theory and selects Chinese industrial enterprises from 2005 to 2013 as the research sample. It focuses on examining whether stakeholders in the capital market – creditors – incorporate harmful gas emission risks into their credit decision-making processes. There are three specific research questions. First, the relationship between sulfur dioxide emissions or carbon risk and the cost of debt financing is explored in the Chinese context. Second, the effects of differences in firms’ ownership structure, whether firms are in coal resource cities, and whether firms are in sulfur dioxide and acid rain control zones on the relationship between sulfur dioxide emissions and debt financing costs are also explored. Third, a channel analysis of sulfur dioxide emissions affecting the cost of debt financing is performed.
This study offers two key innovations. First, previous research often relied on carbon trading price indices from selected cities in China to estimate the country’s overall carbon risk. However, such indices fail to accurately reflect the risk levels of harmful gas emissions at the individual firm level. By using data on direct sulfur dioxide emissions from industrial firms and carbon emissions calculated based on fossil energy consumption, this study more accurately reflects environmental risk differences at the micro-firm level. Second, a three-step U-shaped test procedure is employed to verify the relationship between sulfur dioxide emission intensity and debt financing costs, enhancing the robustness of the conclusions. This study holds significant implications. It demonstrates that creditors price environmental risks to promote responsible lending by penalizing high-emission firms through higher financing costs while incentivizing green firms to preferentially use financial resources. Green credit is a market tool to encourage firms to adopt environmentally friendly practices [4]. Moreover, the findings support the government’s policy tool to promote financial institutions to incorporate environmental risks into financial resource allocation and underscore the necessity for high-emission firms to adopt active environmental risk management strategies to avoid financing challenges.
Review of Relevant Studies
Harmful Gases and Equity Market
Research on the relationship between harmful gases and capital markets can be categorized into two areas: the impact of harmful gases on the equity market and their impact on the debt market. The body of research examining harmful gases and the equity market is more extensive.
First, studies in this area primarily focus on how SO2 emissions influence equity market valuation. Hughes [5] demonstrates that higher sulfur dioxide emissions lead to lower equity market value for high-polluting electric utilities, particularly during the years surrounding the enactment of the Clean Air Amendments Act, a period associated with the highest estimated future compliance costs. Johnston et al. [6] argue that two characteristics of corporate sulfur dioxide emission allowances support their positive correlation with corporate equity market value. Firstly, emission allowance inventories have the asset value of cost reduction and resale value. Next, emission allowance inventories allow firms to defer capital investment, thereby creating real option value. In order to verify whether the above value exists, Johnston et al. [6] take U.S. electric power firms as their sample. Their findings reveal that the number of SO2 emission allowances held by firms positively affects their equity market value, confirming that the emission allowances have asset value. Whether the market prices the option value of SO2 emission allowances remains inconclusive.
Second, research on the relationship between harmful gases and the equity market has also explored whether carbon emissions and greenhouse gas emissions affect the firms’ market value. Matsumura et al. [7], using a sample of S&P 500 firms, find that higher carbon emissions are associated with lower firm value and that firms that disclose carbon emissions have a higher median value than those that choose not to disclose. Griffin et al. [8], analyzing data from S&P 500 and Toronto Stock Exchange 200 companies, find that greenhouse gas emission intensity is negatively correlated with stock prices. Additionally, they observe that greenhouse gas emission information released in company press releases or 8-K filings triggers significant price and trading reactions around the release date as investors update their expectations. Saka and Oshika [9], using data from Japanese firms, find that carbon emissions negatively impact equity market value, whereas carbon management disclosures positively influence market valuation. Similarly, Baboukardos [10], using a sample of firms listed on the London Stock Exchange, finds that a negative association between carbon emissions and market value. However, this negative correlation weakened after UK regulations mandated that listed firms report their greenhouse gas emissions. The studies collectively suggest that CO2 emissions negatively affect firms’ market value and serve as a negative valuation factor for firms’ stock prices. This view is primarily based on the notion that investors treat high greenhouse gas emissions as off-balance-sheet liabilities. These liabilities, which are not reflected in traditional accounting statements, represent investors’ evaluations of potential future costs related to climate change, including compliance, emission reduction, regulatory, and tax expenses [8].
Harmful Gases and Debt Market
Research on harmful gases and the debt market examines how carbon risk and air pollution affect the cost of debt financing. Jung et al. [11] conclude that there is a positive association between the cost of debt and carbon risk for firms failing to demonstrate carbon risk awareness. In contrast, this penalty is effectively negated for firms demonstrating stronger carbon risk awareness. Zhou et al. [12] find that there is a U-shaped relationship between corporate carbon risk and debt financing costs, with media attention playing a moderating role. Liu et al. [13] find that the cost of debt is positively correlated with a company’s carbon emission intensity in the context of the Australian government’s approval of legislation to reduce carbon emissions. It has been argued that carbon risk and social responsibility are borne by all firms in polluted areas, therefore, air pollution is positively related to firm debt financing cost [14]. Following the Paris Agreement, lenders priced carbon risk for all borrowers as a result of the government’s strong commitment to climate change mitigation, and climate-related disclosure has a negative relationship with the cost of debt [15]. The majority of existing studies conclude that higher carbon risk and greater air pollution result in increased debt financing costs for firms, supporting the idea that investors will price the climate risk of firms [16]. When lending institutions factor environmental risks into their credit decisions, firms with high carbon risks or those located in highly polluted cities face elevated environmental compliance costs. These costs negatively affect profitability, reduce cash flow available for debt servicing, and heighten default risks. Additionally, equity investors often reduce or withdraw investments from high-carbon-risk firms [17]. Consequently, lending institutions impose risk premium penalties on such firms.
However, existing research on measuring carbon risk lacks consistency. Due to the perfect disclosure of carbon emission data of foreign firms, carbon risk is usually measured by carbon intensity, calculated as a firm’s annual greenhouse gas emissions divided by its annual sales revenue. In contrast, due to limited micro-level emission data and challenges in data collection in China, scholars have adopted alternative approaches. Some measure environmental risk through penalties imposed for carbon emission violations [12] or environmental violation events [18], while others estimate annual carbon emissions indirectly [19]. Additionally, some studies use the annual average Air Quality Index (AQI) of the city where the firm is located as a proxy for air pollution [14].
Gap in the Literature
To summarize, first, compared with studies on foreign firms, research on Chinese firms tends to be more macroscopic and lacks precision in measuring carbon risk and air pollution. For example, some studies use the air pollution level of the city where a firm is located to analyze its relationship with debt financing costs. However, such macro-level measurements fail to accurately capture the differences in harmful gas emission risks at the individual firm level. Then again, measuring carbon risk solely through penalties for carbon emissions violations is not a comprehensive measure of risk, as it considers only explicit compliance risks while neglecting implicit, undetected compliance risks, as well as physical and commercial risks, which may affect the cost of debt financing for firms. Given that over 99% of carbon dioxide emissions stem from energy consumption [20], this study adopts an alternative approach. Instead of using the ratio of a firm’s annual operating cost to the industry’s annual operating cost multiplied by the industry’s annual carbon dioxide emissions, as used in previous studies [19], this article calculates carbon dioxide emissions indirectly based on fossil energy consumption data of Chinese industrial enterprises.
Second, previous studies have not employed the three-step U-shaped test procedure to verify the existence of a U-shaped relationship [12]. This study applies the three-step U-shaped test to examine the relationship between sulfur dioxide emission intensity and debt financing costs, ensuring more robust conclusions.
Lastly, while significant research has explored the impact of hazardous gases on the equity market, there is a limited investigation into their effect on the debt market, despite the importance of debt financing as a critical input to corporate business strategies [14]. Although climate risks have been extensively studied in the stock market, real estate market, and insurance market [21], the debt market deserves further academic attention. Therefore, the relatively macro-level measurement of harmful gas variables and the scarcity of research on how harmful gases affect debt financing costs in Chinese corporate contexts highlight a gap that warrants further exploration.
Table 1.
Composition of Sulfur Dioxide Emission Sources.
Theoretical Foundations and Research Hypotheses
The traditional neoclassical theory posits that emission reduction activities increase corporate expenditures and reduce the resources available for commodity production. This, in turn, raises operational costs and adversely impacts corporate profits [22]. According to this perspective, environmental management practices may impose a cost burden on business performance by consuming resources, particularly when the firm’s SO2 emission intensity is relatively low. Under such circumstances, efforts to reduce SO2 emissions may be perceived as an inefficient use of corporate resources. Lenders may interpret these expenditures as environmental costs that fail to yield sufficient benefits, leading them to raise debt financing costs to compensate for the increased business risk.
Agency theory is also the theoretical basis of this paper. Agency issues may arise when the environmental risk management goals of lenders and borrowers are inconsistent. Lenders, considering their own reputation risk and the borrowers’ default risk, prefer borrowers to comply with environmental regulations to mitigate environmental risks. In contrast, firms as borrowers may prioritize high-profit projects, even if they are pollution-intensive. Such firms might cut costs by avoiding investments in pollution-reducing equipment or environmentally friendly raw materials, thereby exposing themselves to environmental risks. If the borrowers’ exposure to environmental risks leads to a reduction in cash flow or even project failure, the lenders bear most of the principal loss and face the reputational risk for financing high environmental risk projects. On the other hand, if the project succeeds, lenders earn only a fixed interest return, while shareholders capture most of the profits. The above unequal returns exacerbate the agency’s problems. To manage these risks, lenders incorporate environmental issues [23] and carbon risk factors in their lending operations [24]. Lenders can mitigate agency problems by raising interest rates or shortening debt maturities [25]. Therefore, the agency mechanism plays a major role when firms have high SO2 emission intensity. High emissions lead to increased regulatory, mitigation, and compliance costs, which negatively impact profitability and increase the risk of debt default. In response, lenders increase the cost of debt financing to mitigate the agency problems, based on the consideration that the environmental risk increases the business risk.
In summary, in the context of China, this paper predicts that there is an “interval effect” in the impact of sulfur dioxide emission intensity on the cost of corporate debt financing, and the following hypothesis is proposed:
H1: SO2 emission intensity exhibits a U-shaped relationship with the cost of debt financing.
Materials and Methods
Sample Selection and Data Sources
The sample of this paper is Chinese industrial firms from 2005 to 2013. Data on firms’ basic and financial information is sourced from the industrial firm database of EPS Data, while data on SO2 emissions of the firms are obtained from the Green Development Database of EPS Data. The choice of industrial firms as a sample is because industrial sources are the main source of sulfur dioxide emissions in China. As shown in Table 1, industrial sources account for 80% or even 90% of national sulfur dioxide emissions, making this sample highly representative. Additionally, the industrial firm database includes almost all state-owned and non-state-owned industrial firms above a certain scale nationwide, ensuring a large sample size that minimizes estimation bias and enhances estimation efficiency. The sample period of 2005-2013 is chosen because, up to now, the period of data available from matching the industrial firm database of the EPS Data with the green development database is 1998-2013. In 2005, the Chinese government adopted stricter environmental regulations for SO2 emission reduction. Since this study does not aim to evaluate the policy effects of incorporating SO2 emission reduction into officials’ performance evaluations, selecting 2005-2013 helps control for the influence of environmental regulation levels. We unify the names and the codes of broad industry categories with reference to the 2012 National Economic Industry Classification (GB/T 4754-2011). Province-level control variables, such as the index of the development of market intermediary organizations, the legal institutional environment, and the marketization index of the financial sector, are sourced from the China Sub-Provincial Marketization Index database. Data on GDP per capita and coal consumption by industry are derived from CSMAR.
There are two reasons for choosing sulfur dioxide emissions to measure harmful gases. First, the primary reason aligns with Liu et al. [26]: sulfur dioxide was a priority pollutant for control during the sample period of this study. It is a major contributor to acid rain, and during this time, China implemented the National Acid Rain and Sulfur Dioxide Pollution Prevention and Control Eleventh Five-Year Plan, which mandated a 10% reduction in total SO2 emissions by 2010 compared to 2005, capping emissions at 22.944 million tons. By 2020, national SO2 emissions had significantly declined from 2010 levels. Second, compared to other harmful gases, firm-level data on sulfur dioxide emissions are more abundant and readily available. For instance, the industrial firm database includes annual SO2 emissions data at the micro level. Although recent years have seen increased attention to carbon dioxide emissions and their control in China, direct micro level data on CO2 emissions remain limited. Considering the shared root causes of carbon and sulfur dioxide emissions, studying the impact of SO2 emissions on the cost of corporate debt financing offers valuable insights and a reference point for future research on the relationship between CO2 emissions and debt financing costs for Chinese firms at the micro level.
The database of industrial firms encompasses a vast number of samples, necessitating extensive data cleaning and screening. This study implemented the following steps to ensure data accuracy and reliability. First, exclusion of invalid financial data: observations where paid-in capital is less than or equal to zero are removed. Second, removal of observations violating accounting principles: abnormal cases, such as total assets being less than current assets, total assets being less than the book value of fixed assets, or accumulated depreciation being less than the current year’s depreciation, are excluded. Third, elimination of cases with anomalous key indicators: observations with negative values for interest expenditures, total liabilities, or sulfur dioxide emissions are deleted. Finally, handling of missing data: all observations with missing values for key variables are excluded. Furthermore, data from 2010 is excluded due to significant missing values, with 2009 and 2011 treated as consecutive years to construct an unbalanced panel dataset. All continuous variables are Winsorized at the 1st and 99th percentiles. The final dataset consisted of 96,270 industrial firms and 274,848 observations.
Model Design
To test our main hypothesis, we estimate the following Equation:
Where i represents the firm, t represents the year; Cod is the firm’s cost of debt financing, calculated by dividing the firm’s annual interest expense by its total liabilities due to data availability. SO2 is the sulfur dioxide emission intensity, measured as the firm’s annual sulfur dioxide emissions divided by its total inflation-adjusted industrial output value. This method aligns with Liu et al. [26] and enables comparisons of relative risks across firms of varying sizes and industries. Inflation adjustment uses the Industrial Producer Price Index (PPI) from the National Bureau of Statistics, with all values adjusted to a 2005 base period (where PPI = 100). Con as control variables, this paper refers to the studies of Jung et al. [11], Zhou et al. [12], Zhu et al. [19], and Wang et al. [27], and adds firm size (Siz), leverage ratio (Lev), fixed asset ratio (Tan), return on total assets (Roa), and interest coverage multiple (Ipm) as firm-level control variables; and the development of market intermediary organizations and legal institutional environment index (Leg), the marketization index of the financial sector (Fin), and gross domestic product (Gdp) per capita as province-level control variables.
Specific variable definitions are shown in Table 2. Fir is the individual firm fixed effects; Yea is the year fixed effects, ε is the error term. β1 is the coefficient of the single term of the SO2 emission intensity; β2 is the coefficient of the quadratic term of the SO2 emission intensity; Σβ represents the coefficients of the control variables. To address potential heteroskedasticity and serial autocorrelation, standard errors are clustered at the firm level.
Table 2.
Definition of Variables.
Results and Discussion
Descriptive Statistics and Correlation Analysis
Table 3 reports the mean value of the cost of debt financing (Cod) is 0.044, which is slightly lower than the reported mean of 0.069 for listed industrial firms in China during the period 2009-2019 [19]. The mean value of sulfur dioxide emission intensity (SO2) is 0.009, indicating that, on average, the sample firms emit 0.9 kg of sulfur dioxide for every RMB 1,000 of output. This is consistent with the findings of Liu et al. [26], which report an average emission intensity of 0.880 kg of sulfur dioxide per RMB 1,000 of output for Chinese industrial firms during 2003-2012.
Table 4 shows the absolute values of correlation coefficients between the main variables, which are all below 0.8. The maximum variance inflation factor (VIF) is 3.06, significantly below the commonly accepted threshold of 10. Furthermore, the mean VIF across all variables is 1.68, well under 2. This means that no serious multicollinearity problems are found with this model.
Baseline Regression and U-Test
Column (1) of Table 5 presents the nonlinear regression results of Model (1) without including provincial-level control variables. The coefficient for SO22 is significantly positive. To account for macroeconomic factors, legal environment, and financial market development, Column (2) of Table 5 reports the nonlinear regression results of Model (1) with the inclusion of provincial-level control variables. The coefficient for SO22 remains significantly positive. Lind et al. [28] and Haans et al. [29] argue that significant quadratic term coefficients alone are insufficient to confirm a U-shaped relationship. To test for the presence of a U-shaped relationship, we follow a three-step procedure. Firstly, the quadratic coefficients are significant and consistent with expectations. Secondly, the slopes at the extreme values of the independent variable (the minimum and maximum) must be steep enough, with the slope at the minimum point being negative and significant, and the slope at the maximum point being positive and significant. Thirdly, the inflection point should lie within the data scope, with the confidence interval for the inflection point also lying within the data range. We apply this three-step U-test to the nonlinear regression results. Part A of Table 6 shows the U-shaped relationship test for the regression results in Column (1) of Table 5. The results fully satisfy the three conditions for confirming a U-shaped relationship. Firstly, the coefficient for SO22, as mentioned earlier, is significantly positive. Secondly, the slope (-0.106) at the minimum value of the explanatory variable is negative and significant, and at the maximum value of the explanatory variable, the slope (0.051) is positive and significant. Thirdly, the inflection point 0.127 lies within the data scope for the explanatory variable (0 to 0.188), and the 90% confidence interval for the inflection point (0.106 to 0.177) also lies within this range (0 to 0.188). In Part B of Table 6, we add provincial-level control variables, and the coefficient for SO22 in the regression results from Column (2) of Table 5 remains significantly positive. The results of the U-shaped relationship test also meet all three conditions. Therefore, we conclude that sulfur dioxide emission intensity (SO2) exhibits a U-shaped relationship with the cost of debt financing (Cod).
Table 3.
Results for Descriptive Statistics.
Table 4.
Pearson Correlation Coefficients.
Table 5.
Nonlinear Model Regression Results of Sulfur Dioxide Emission Intensity and Debt Financing Cost.
Indeed, Developing countries, such as China and India, have made significant contributions to global emissions, and they also have unique political systems, less developed financial markets, and management thinking that is different from that of developed countries [30]. Therefore, the empirical results of our sample of Chinese firms do not show a linear relationship, as discussed earlier, but rather a U-shaped relationship. Specifically, when firms’ SO2 emission intensity is low (<0.126), the risk of debt default due to environmental risks is low. In this case, firms’ efforts to reduce SO2 emission intensity are unnecessary, as they could lead to resource wastage, increased costs, and higher operational risks. As a result, creditors raise the cost of debt financing. However, when firms have high SO2 emission intensity (>0.126), the environmental risks, including increased regulatory, abatement, and compliance costs, raise operational risks, which, in turn, increase the risk of debt default. In such cases, creditors raise the cost of debt to penalize the firm. Previous studies have focused on factors affecting CO2 emissions and environmental quality, such as renewable energy [31], low uncertainties in geopolitics, economic policy, and climate policy [32], investments in energy efficiency R&D, and advances in information and communication technologies [33], all of which can help reduce CO2 emissions. This paper discusses the management of harmful emissions from the perspective of stakeholders, specifically creditors.
Table 6.
Results of U-test for Nonlinear Model Regression.
Endogeneity Problem-Instrumental Variable Estimation
Wang et al. [27] examine how air pollution influences the cost of debt financing and highlight the potential bidirectional causality issue. For example, debt financing impacts a firm’s performance and value, and a higher cost of debt financing inevitably increases profitability pressure, which may incentivize firms to emit more polluting gases. Similarly, Zhu et al. [19] point out that firms with lower debt costs are more likely to invest in green projects, suggesting bidirectional causality. Consistent with these findings, this paper argues that bidirectional causality exists between SO2 emission intensity and the cost of debt financing. Although our Model (1) applies a two-way fixed effects approach, it may still suffer from omitted variable bias due to unobservable factors. Therefore, to address the potential endogeneity issue, we employ instrumental variables in our analysis.
Industry coal consumption with a one-year lag is chosen as the instrumental variable based on the characteristics of the sample data, data availability, and the reasons underlying the endogeneity issue. Lagged industry coal consumption is correlated with firms’ current sulfur dioxide emissions while remaining uncorrelated with their current cost of debt financing and unobservable variables omitted in the current period. This selection satisfies both the correlation and exclusion conditions required for a valid instrumental variable.
The results of the instrumental variable method (untabulated) confirm that the necessary statistical tests are satisfied. The unidentifiability test, indicated by the Kleibergen-Paap rk LM statistic of 93.443 with a p-value of 0.000, demonstrates that the instrument is relevant. The weak instrumental variable test, with a Kleibergen-Paap rk Wald F-value of 44.678, exceeds the critical value of 7.03 for 10% bias in the Stock-Yogo weak ID test critical values, confirming the strength of the instrument. Additionally, the endogeneity test yields a p-value of 0.000, supporting the presence of endogeneity. Since the number of instrumental variables matches the number of endogenous explanatory variables, the over-identification test cannot be performed to assess the exogeneity of the instrument, which has already been qualitatively analyzed in the previous section. Table 7 shows the results of the second step of the two-stage least squares regression analysis. The squared term of SO2 emission intensity is significantly positive.
Robustness Tests
To test the robustness of our results, we consider alternative measurements for the dependent variable, firms’ cost of debt financing (Cod), as well as two other proxy variables for the independent variable, firms’ sulfur dioxide emission intensity (SO2). The results are shown in Table 8. In Column (1), we measure sulfur dioxide emission intensity (SO2) by dividing a firm’s sulfur dioxide emissions by its operating income, adjusted for inflation. Additionally, we scale the magnitude of sulfur dioxide emission intensity by a factor of 100. These results indicate that the squared term of sulfur dioxide emission intensity (SO22) remains significantly positive. It passes the U-test at the 90% confidence interval, with the confidence interval (0.117; 0.194) maintaining two decimal places, and it lies within the scope of the data for the explanatory variable (0; 0.190). In Column (2), we replace sulfur dioxide emission intensity (SO2) with a composite pollutant emission intensity variable (Pol), which is calculated as the sum of sulfur dioxide (SO2), nitrogen oxides (NOx), and soot and dust emissions, divided by the firm’s inflation-adjusted industrial output value for the year. The scale of the pollutant emission intensity is also reduced by a factor of 100. The results show that the squared term of corporate gas pollutant emissions (Pol2) remains significantly positive and passes the U-test at the 95% confidence interval. It is important to note that the number of observations in Column (1) is smaller due to missing or zero values for business income. Column (2) contains fewer observations than the baseline regression, primarily because of missing values for nitrogen oxide (NOx) and soot and dust emissions, with NOx emissions particularly lacking statistical values in 2005.
Table 7.
Second Stage Regression Results of Instrumental Variable Estimation.
Table 8.
Robustness Test – Alternative Measures of Independent Variables.
Table 9 presents the results in which the dependent variable, corporate cost of debt financing (Cod), is measured by dividing finance costs by total liabilities. The results show that the squared term of sulfur dioxide emission intensity (SO22) remains significantly positive and passes the U-test at the 95% confidence interval. The difference in the number of observations from the baseline regression is negligible, and the reduced sample size is attributed to missing values for finance costs.
Heterogeneity Analysis
Politically connected Chinese firms are known to face fewer financing constraints [34], while state-owned enterprises (SOEs) tend to receive more favorable borrowing conditions [35]. Political connections can largely protect SOEs from penalties for environmental violations when local governments impose environmental regulations [27]. It is, therefore, inferred that lending institutions are less sensitive to environmental risks and risk premium penalties when lending to SOEs with the same level of SO2 emissions as non-SOEs. Based on this, we expect the relationship between sulfur dioxide emission intensity and the cost of debt financing to differ depending on the ownership structure of the firm. In this analysis, we categorize SOEs as 1 and non-SOEs as 0 for the subsample regression. Table 10, Column (1) presents the regression results for the SOE sub-sample, where the coefficient of the squared term of SO2 emission intensity is not statistically significant at the conventional levels. Column (2) shows the results for the non-SOE subsample, where the coefficient of the squared term of sulfur dioxide emission intensity (SO22) is statistically significant and passes the U-test at the 1% level. These findings suggest that the U-shaped relationship between sulfur dioxide emission intensity and the cost of debt financing is more pronounced for non-SOEs compared to SOEs.
If a firm contributes to the development of the local economy [27] and increases local government revenues [26], it is likely to have stronger bargaining power regarding environmental regulation, potentially reducing the penalties imposed by creditors for its environmental pollution. SO2 emissions are mainly from coal consumption, and in China, coal accounts for 70% of total energy consumption. Most firms in coal-resource cities are concentrated around coal-related industries. The economy of these cities heavily depends on the coal sector. Consequently, creditors may be less sensitive to environmental pollution and may reduce penalties due to the economic contributions of industrial firms in coal resource cities. Therefore, we hypothesize that the relationship between sulfur dioxide emission intensity and the cost of debt financing will differ depending on whether the firm is located in a coal-resource city. To identify coal-resource cities, we use Li’s [36] classification, which categorizes 63 coal cities based on the type of resources. We categorize coal-resource cities as 1 and non-coal-resource cities as 0, then perform sub-sample regressions. Table 11, Column (1) presents the regression results for the subsample of coal-resource cities, where the coefficient of the squared term of SO2 emission intensity is not statistically significant at conventional levels. Column (2) shows the regression results for the subsample of non-coal resource cities, where the coefficient of the squared term of sulfur dioxide emission intensity (SO22) is statistically significant, and the U-shape relationship passes the U-test. These results indicate that the U-shaped relationship between sulfur dioxide emission intensity and the cost of debt financing is more significant for non-coal resource cities compared to coal resource cities.
Table 9.
Robustness Test – Alternative Measures of Dependent Variables.
Table 10.
H eterogeneity Analysis – Ownership Structure.
Liu et al. [26] and Chen et al. [37] both use sulfur dioxide and acid rain two control zones, as well as non-SO2 or non-acid rain control zones, defined by the Chinese government in 1998, as proxies to differentiate the level of environmental regulation. It is widely agreed that the two control zone policy became effectively enforced in 2005 when China integrated the fulfillment of sulfur dioxide emission reduction targets into the performance evaluation system for local government leaders. After 2005, firms in two control zones faced stricter SO2 reduction targets and policy measures compared to those in non-SO2 or non-acid rain control zones. These measures included the installation of desulfurization technology in thermal power plants, a reduction in the number of new thermal power plants, and the exit of high-emission industries, all of which led to greater reductions in emissions [37]. Given these stricter policies, we expect that during the sample period of this study, firms in two control zones would face more stringent sulfur dioxide abatement measures, have greater awareness of environmental risks, and implement more proactive environmental risk management strategies. Additionally, with the exit of high-emission industries from two control zones, these areas would have a higher proportion of “superior” firms with lower emissions, leading creditors to perceive the environmental risks of industrial firms in two control zones as lower. This perception, in turn, would reduce creditors’ sensitivity to environmental pollution and the associated risk premium penalties for firms in these regions. Therefore, we hypothesize that the relationship between sulfur dioxide emission intensity and the cost of debt financing will vary depending on whether a firm is located in two control zones. To test this hypothesis, we categorize two control zones as 1 and those in non-SO2 or non-acid rain control zones as 0, and perform subgroup regressions. Table 12, Column (1) presents the results for the sub-sample of firms in two control zones, where the coefficient of the squared term of sulfur dioxide emission intensity (SO22) is statistically significant. However, the results of the U-test indicate that the 90% confidence interval for the inflection point (0.109; 0.217) lies outside the range of the data for the independent variable (0; 0.188), which means the U-shaped relationship fails the U-test. Column (2) shows the results for the sub-sample of firms in non-SO2 or non-acid rain control zones, where the coefficient of the squared term of sulfur dioxide emission intensity (SO22) is statistically significant, and the U-shaped relationship passes the U-test. These findings suggest that the U-shaped relationship between sulfur dioxide emission intensity and the cost of debt financing is more pronounced for firms in non-SO2 or non-acid rain control zones compared to those in two control zones.
Table 11.
Heterogeneity Analysis – Whether the Firm Is Located in a Coal Resource City.
Table 12.
Heterogeneity Analysis - Is the Firm in Two Control Zones.
Table 13.
Difference in Mean Values of Core Variables Between Two Control Zones and Non-SO2/Acid Rain Control Zones.
Fig. 1.
Annual Average of Total Sulfur Dioxide Removal in Two Control Zones and Non-SO2/Acid Rain Control Zones.
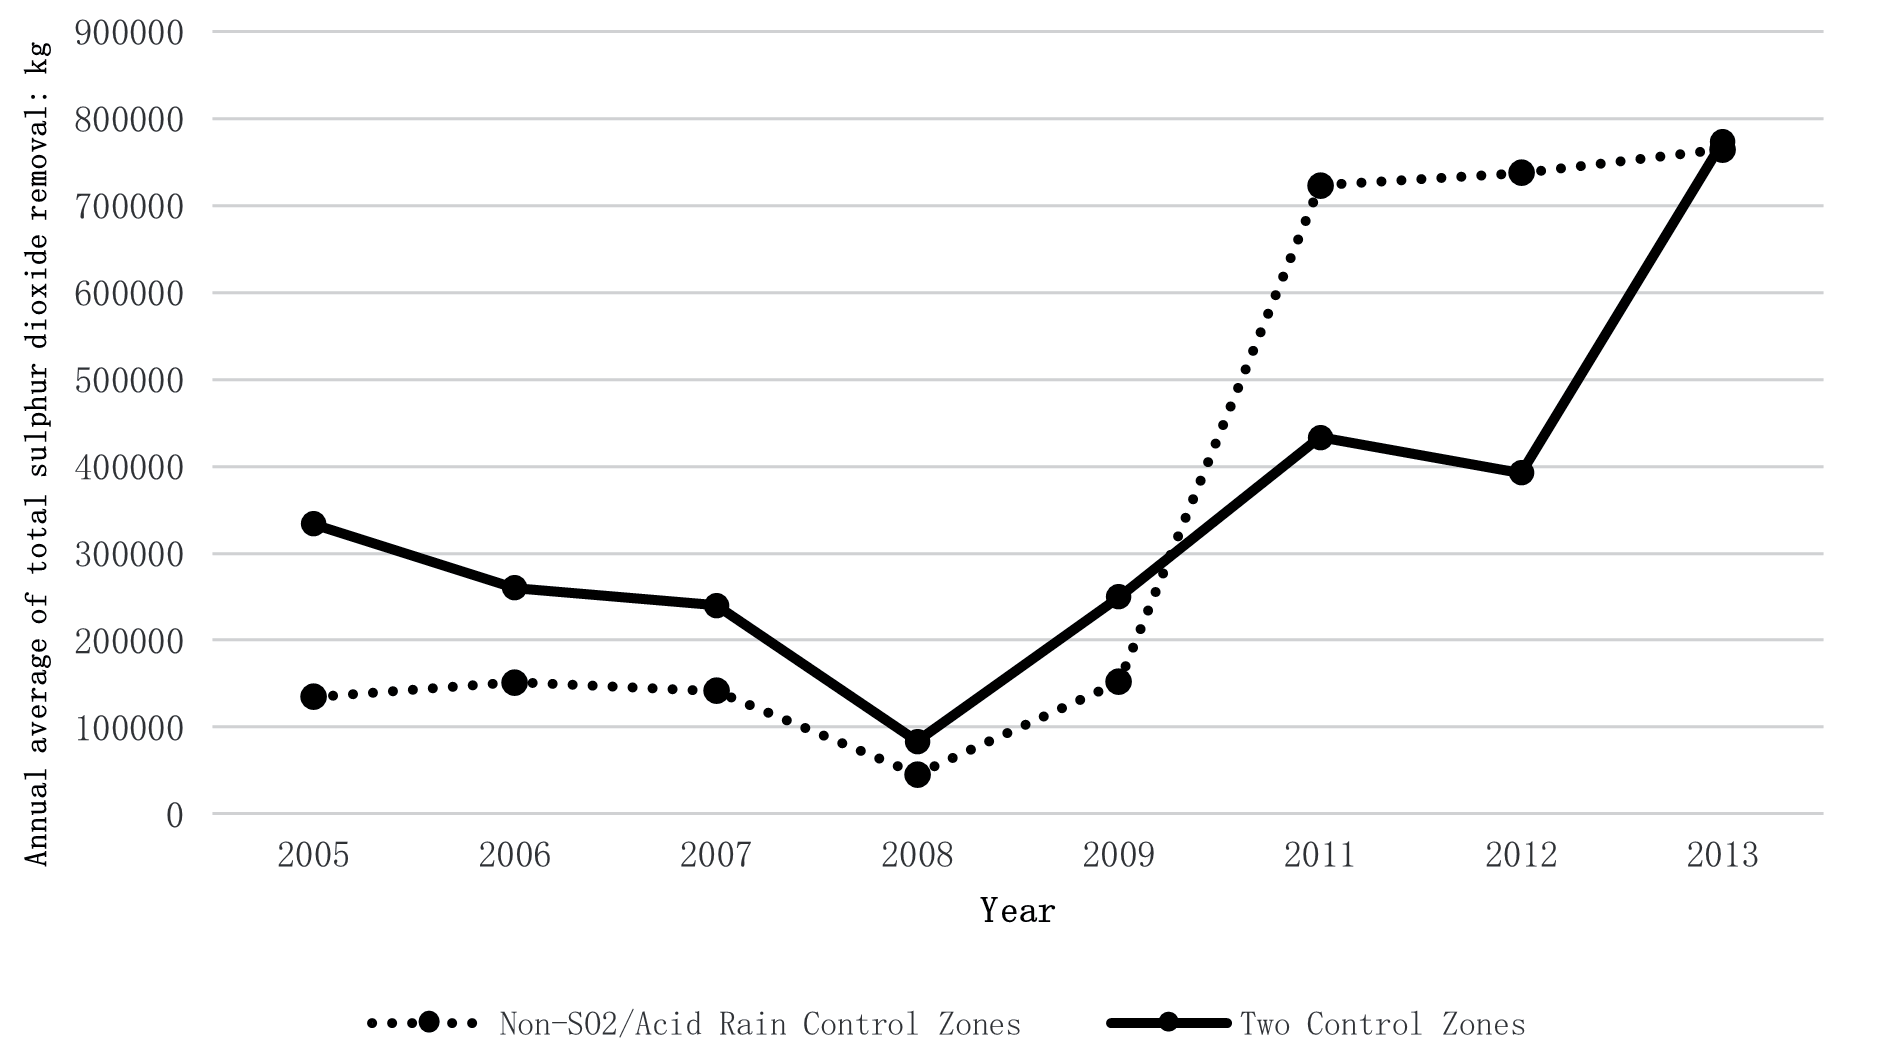
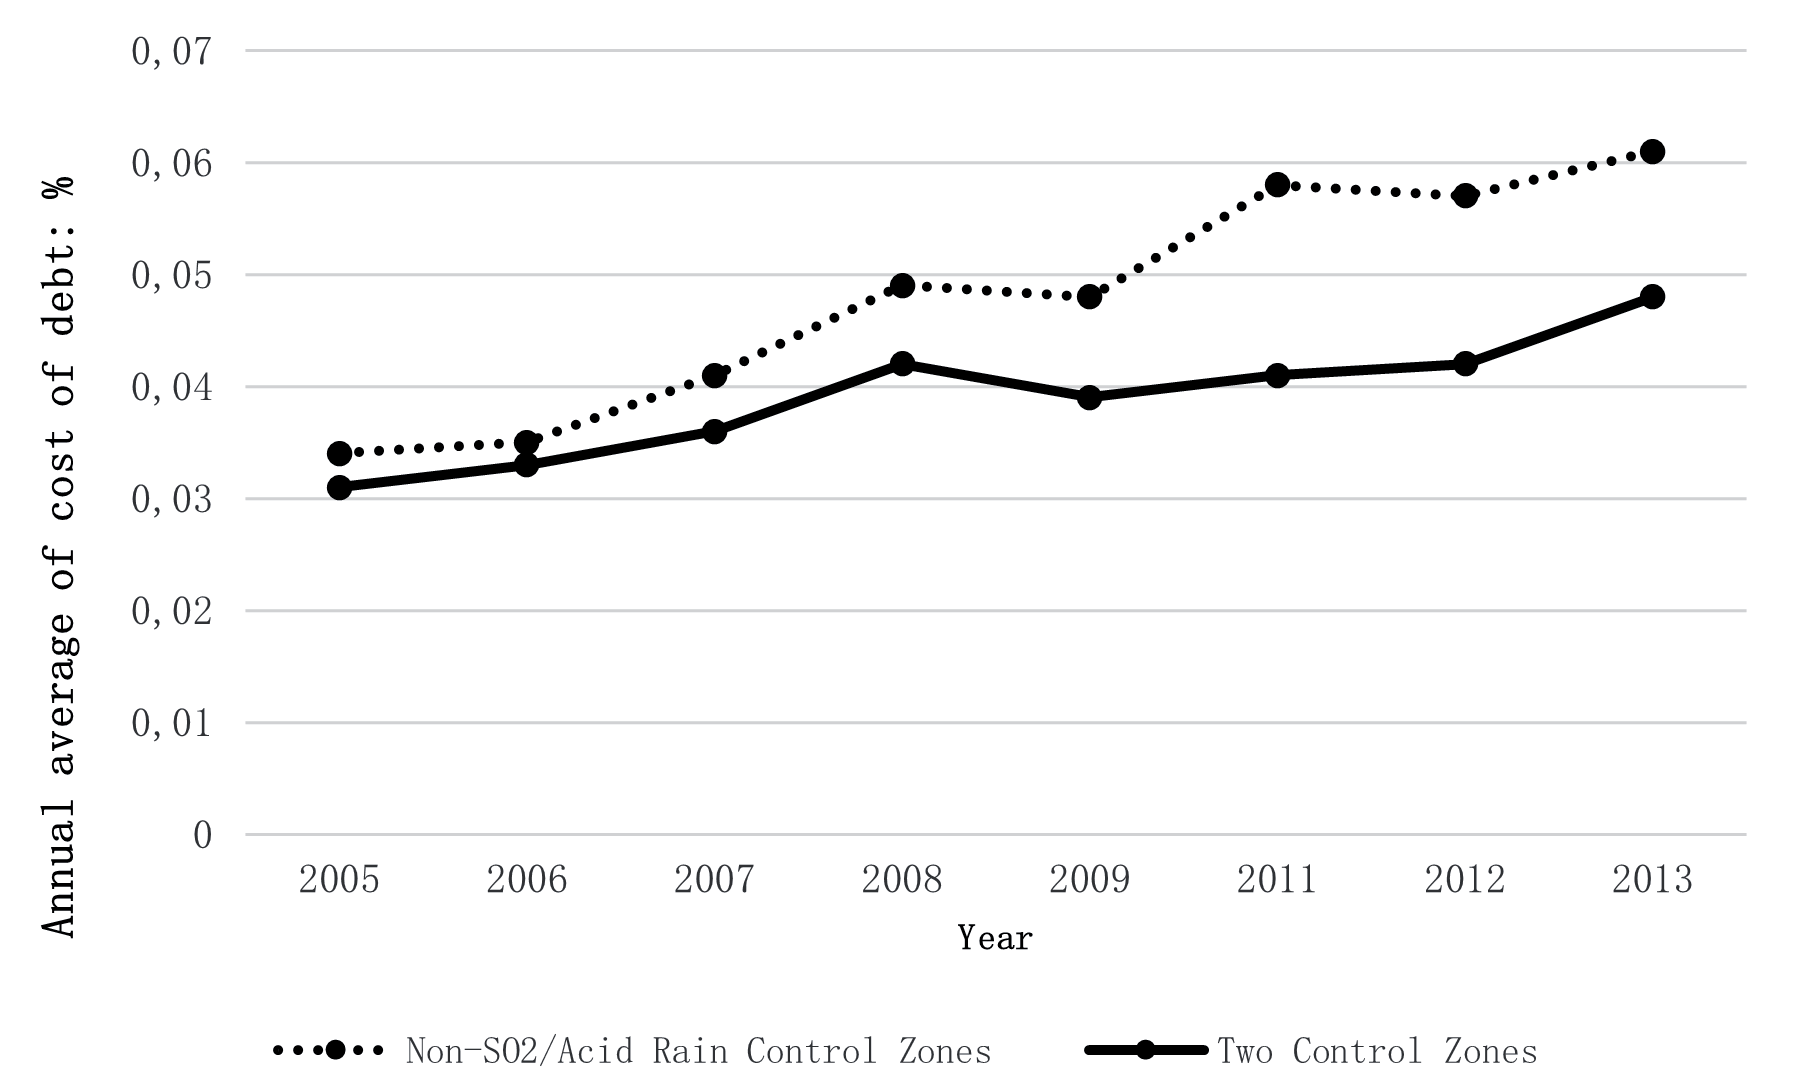
Fig. 3.
Annual average of sulfur dioxide emission intensity in Two Control Zones and Non-SO2/Acid Rain Control Zones.
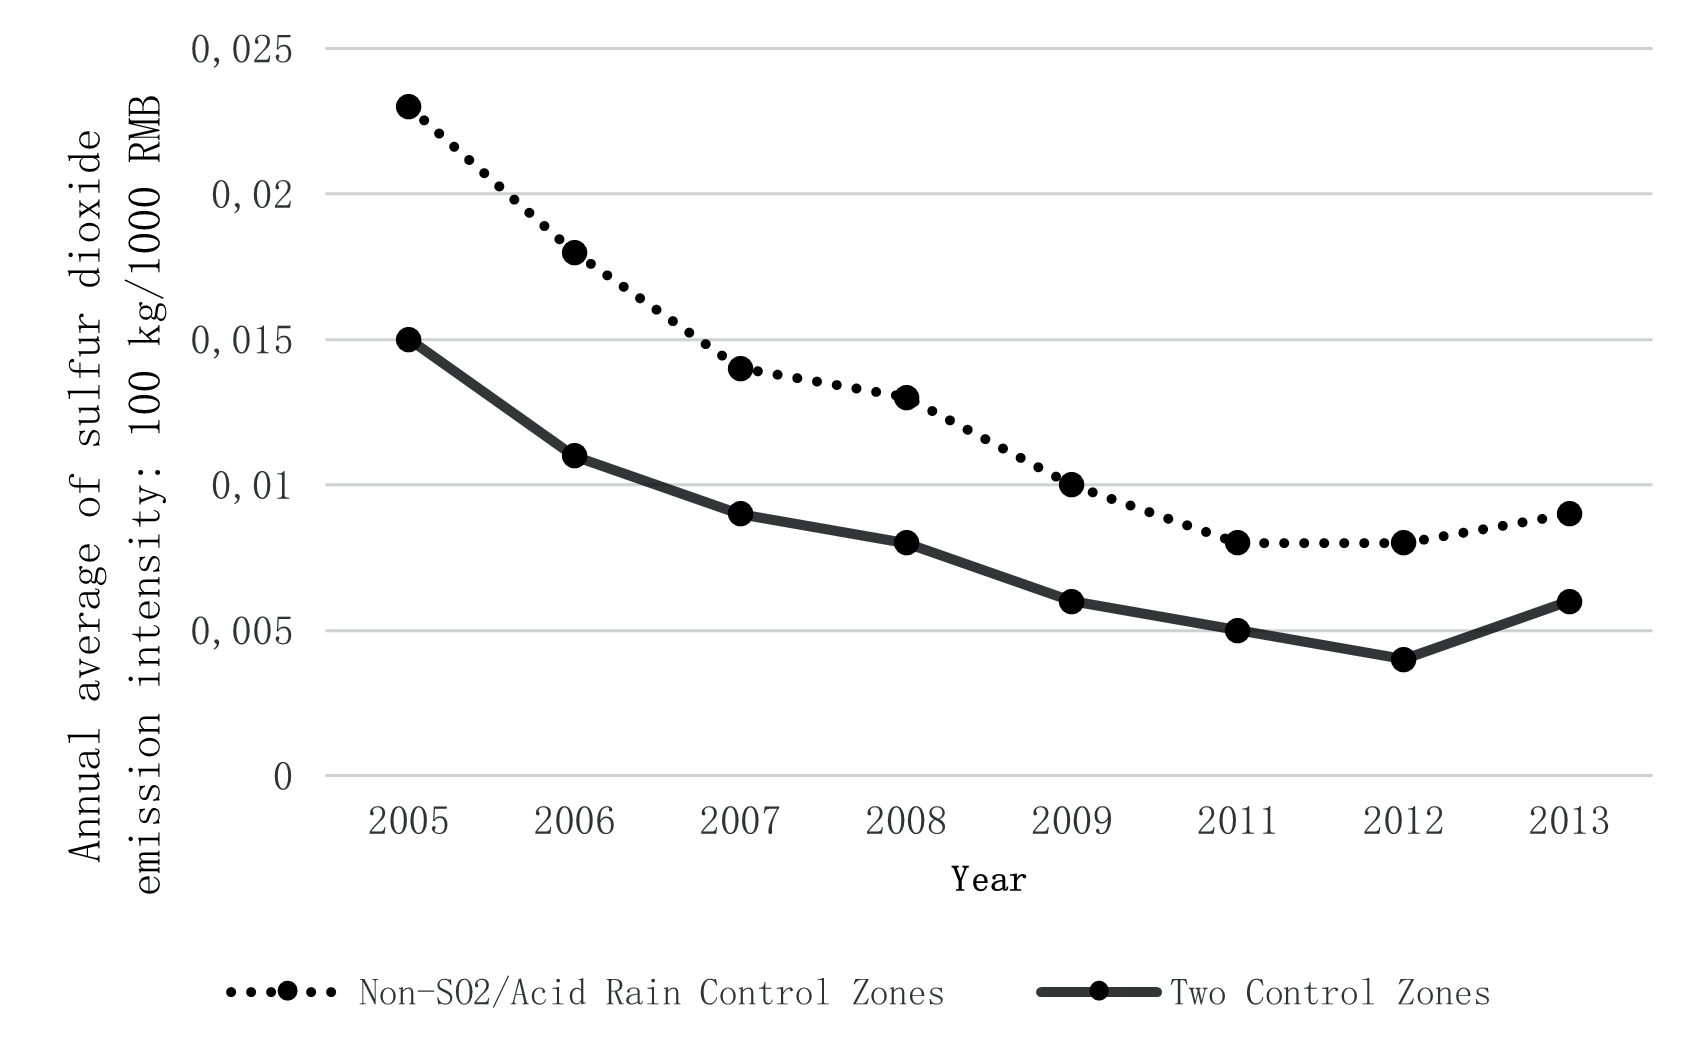
Further analysis, as shown in Table 13, reveals that the mean SO2 emission intensity for firms in non-SO2 or non-acid rain control zones (0.012) is higher than that for firms in two control zones (0.008). The difference between the two groups is statistically significant (P-value<1%). Additionally, as shown in Fig. 1, the annual total SO2 emissions reduced by firms in two control zones are higher than those in non-SO2 or non-acid rain control zones for most years, particularly during the 11th Five-Year Plan period after 2005. This suggests that emission reductions in two control zones are greater, reflecting more stringent control measures and successful implementation of those measures. Moreover, Table 13 indicates that the mean cost of corporate debt financing in non-SO2 or non-acid rain zones (0.051) is higher than in two control zones (0.039), with the difference being statistically significant (P-value<1%). Fig. 2 illustrates that the average annual cost of debt financing for firms in two control zones is consistently lower than that for firms in non-SO2 or non-acid rain zones, with the P-value of the mean difference for each year (not shown in the table) also being significant. This suggests that creditors generally perceive firms in two control zones as more “superior” in terms of sulfur dioxide emission reductions, resulting in lower debt financing cost penalties for these firms due to their better environmental performance under strict regulations. As shown in Fig. 3, the mean SO2 emission intensity for firms in two control zones is consistently lower than that of firms in non-SO2 or non-acid rain zones, with significant P-values for the differences in the mean values for each year (not tabulated). These findings support the earlier analysis, indicating that firms in two control zones face stricter SO2 reduction targets and policies compared to firms in non-SO2 or non-acid rain zones after 2005. The increased number of “top performers” in emission reductions in two control zones likely contributes to creditors reducing their sensitivity to environmental pollution risk and consequently weakening the cost of debt financing penalties. Therefore, the U-shaped relationship between sulfur dioxide emission intensity and the cost of debt financing is more pronounced for firms in non-SO2 or non-acid rain zones than for those in two control zones.
In summary, the U-shaped relationship between sulfur dioxide emission intensity and the cost of debt financing varies based on the firm’s ownership structure, whether the firm is located in a coal-resource city, and whether it operates in two control zones.
Table 16.
Results of U-test for Nonlinear Model Regression.
| Minimum value | Maximum value | |
|---|---|---|
| The range of values of the independent variable | 0.00003 | 0.436 |
| Slope | -0.068 | 0.029 |
| t-value | -4.158 | 1.676 |
| P-value | 0.00002 | 0.050 |
| Inflexion point | 0.305 | |
| 90% Confidence interval | [0.257; 0.431] |
Table 14.
Regression Results of Impact Mechanism Analysis.
Table 15.
Nonlinear Model Regression Results of Carbon Risk and Debt Financing Cost.
Analysis of Impact Mechanisms
In this section, we examine whether earnings volatility serves as a channel through which SO2 emission intensity affects the cost of corporate debt financing. Earnings volatility (Vol) is measured by the standard deviation of return on assets (ROA). To account for industry heterogeneity, the firm’s ROA for each year is adjusted by subtracting the annual industry mean ROA, and the standard deviation of the firm’s three-period rolling ROA is then calculated. For firms with only one period of data, the standard deviation of ROA is treated as a missing value.
Column (1) of Table 14 shows that when sulfur dioxide emission intensity is low, emission reduction efforts waste corporate resources, increase costs, and contribute to greater earnings volatility, thereby elevating operational risks. Once SO2 emissions surpass the inflection point, the increase in regulatory, abatement, and compliance costs further exacerbates earnings volatility, while environmental risks drive up operational risks. Column (2) of Table 14 demonstrates that after controlling for the adjusted standard deviation of the three-period rolling return on assets (Vol), the coefficient of the sulfur dioxide squared term (SO22) remains significantly positive and passes the U-test. As a result, the U-shaped relationship between sulfur dioxide emission intensity and firms’ cost of debt financing persists.
Further Analysis: Measured Corporate Carbon Risk and Cost of Debt Financing
Research on the impact of low-carbon transition risks on debt financing costs can help Chinese firms better adapt to climate and environmental policies, thereby reducing systemic financial risks [38]. In this section, we follow the approach of Lu Jing et al. [39], and measure the carbon risk of firms based on the carbon dioxide accounting methods and data provided by the National Development and Reform Commission (NDRC) in their publications: NDRC Climate [2013] No. 2526, NDRC Climate [2014] No. 2920, and NDRC Climate [2015] No. 1722. The carbon risk is measured using the following formula:
Where j is the j-th type of fossil fuel used by the firm, and n is the total number of fossil fuel types used by the firm. This measure is based on the consumption data of coal, fuel oil, diesel, and clean gas, as reported in the Green Development Database of the EPS Data. CO2 represents the carbon dioxide emissions resulting from the firm’s fossil fuel consumption, which, in the regression, is divided by the inflation-adjusted gross industrial output of the firm for the year and scaled down by a factor of 10,000. Ncv is the average low-level heating value of fossil fuels; FC is the net consumption of fossil fuels; CC is the carbon content per unit calorific value of fossil fuels; and OF is the carbon oxidation rate of fossil fuels.
The squared term of firms’ carbon dioxide emissions (CO22) is significantly positive in Table 15; Table 16 shows the relationship passes the U-test. Therefore, corporate carbon risk exhibits a U-shaped relationship with the cost of debt financing.
Conclusions
This paper empirically examines the impact of corporate sulfur dioxide (SO2) emission intensity on the cost of debt financing using a two-way fixed effects model, grounded in traditional neoclassical and agency theories, and the U-test. The study analyzes data from Chinese industrial firms between 2005 and 2013. The findings are as follows. First, there is a U-shaped relationship between firms’ SO2 emission intensity and the cost of debt financing. When SO2 emission intensity is low, according to traditional neoclassical theory, firms’ emission reduction activities increase their costs and waste resources, leading creditors to raise risk premiums due to concerns about business performance. When SO2 emission intensity is high, agency theory suggests that banks may face legitimacy and reputational risks associated with financing polluting projects. Additionally, increased regulatory compliance costs may reduce firms’ cash flow, prompting creditors to raise the cost of debt financing based on environmental concerns. A similar U-shaped relationship is also found between firms’ carbon dioxide (CO2) emissions, measured through fossil fuel consumption, and the cost of debt financing. Second, the U-shaped relationship is more pronounced among non-state-owned enterprises (non-SOEs), firms located in non-coal resource cities, and firms operating outside two control zones for sulfur dioxide and acid rain. This is attributed to the financing advantages enjoyed by state-owned enterprises (SOEs), the economic importance of industrial firms in coal resource cities, and the more stringent environmental regulations in two control zones for sulfur dioxide and acid rain. Third, earnings volatility is identified as the channel through which SO2 emission intensity influences the cost of corporate debt financing.
This thesis has the following meanings for green sustainability. First, in the context of green finance, the paper emphasizes that environmental risks are priced from the creditor’s viewpoint, raising the cost of financial resources for firms and internalizing the costs of corporate emissions. For highly polluting firms, which are most in need of transitioning to cleaner production, it becomes increasingly difficult to obtain capital, or they may face more expensive terms in the future [40]. Therefore, it is crucial for firm managers to enhance their awareness of environmental risk management, implement appropriate strategies for managing harmful gas emissions, reduce environmental risks, and thus lower the penalties by creditors. This will also reduce the likelihood of the firm falling into financial distress. Second, the study also highlights that firms facing stricter environmental regulations and higher levels of harmful emissions can implement strategies such as proactive environmental risk disclosure. By actively disclosing environmental risk information and green innovation projects, firms can respond to governmental and financial institution-led pollution reduction initiatives. This can help mitigate the risk premium penalties imposed by creditors due to information asymmetry and compliance risks and reduce the unchecked expansion of polluting projects. Third, sulfur dioxide has historically been a priority in China’s regulation of harmful emissions. Government policymakers can refer to successful sulfur dioxide emission reduction policies as a model to promote carbon emission reduction efforts. By encouraging corporate disclosure of harmful gas emissions and aligning green financial policies with officials’ environmental performance target assessments, China can further enhance green corporate governance and reduce environmental risks.
Finally, we acknowledge the limitations of our study. The official dataset for industrial firms ends in 2013, which limits our ability to test the research question using more recent data. Data on harmful gas emissions are crucial for identifying firm emission reduction opportunities and assessing the effectiveness of emission reduction policies. However, sulfur dioxide and carbon dioxide emission data, as well as management data of Chinese firms, are insufficiently disclosed. Therefore, we call for the complete, accurate, and timely disclosure of environmental information by Chinese firms. Researchers can use such data to investigate which environmental policies most effectively support emission reduction and promote sustainable development, identify sources of firm emissions, pinpoint key risk areas for emission reductions, and contribute to the long-term sustainability of firms.

