

Introduction
After decades of rapid growth in China’s economic development after the reform and opening up, people’s living standards have been greatly improved and enhanced, and they are more concerned about regional pollution conditions in their work and lives, while expecting the government to actively carry out environmental treatment and improve environmental quality to meet the public demand for having a green environment. There are many factors affecting pollution emissions, and existing studies have explored the environmental pollution problem in China from several perspectives. Based on the economic activity perspective, economic development [1], energy consumption [2, 3], FDI [4, 5], industrial agglomeration [6], and financial development [7] are considered to be influencing regional key factors of environmental quality. Economic growth can bring about environmental pollution problems, and although such studies reveal the intrinsic motives of pollution problems, they are hardly effective in improving regional environmental governance. Based on the environmental regulation perspective, most studies argue that environmental regulation can improve the level of environmental governance and regional environmental quality [8-11]. Administrative command-based environmental regulation and market-based environmental regulation have reduced pollution emissions to a certain extent, but they are still inadequate because environmental pollution management cannot rely on the government and the market alone, but requires the active participation of a wide range of the public. The prevention and control of environmental pollution is not only a practical requirement of the people, but also a realistic need for China to transform its economic development mode and achieve green and sustainable development.
In order to prevent and control environmental pollution and promote healthy and stable economic development, the Chinese government has adopted a series of pollution control measures to reduce environmental pollution to a certain extent [12, 13]. In 2007, the former State Environmental Protection Administration (now the Ministry of Ecology and Environment of the People’s Republic of China) issued Measures on Environmental Information Disclosure (for trial implementation)”. This policy has enhanced the enthusiasm of all social parties to participate in environmental pollution supervision and provided institutional safeguards to reduce regional pollution emissions, promote energy restructuring, and achieve high-quality economic development. However, there is little literature to explore its specific impact on the pollution emissions of Chinese enterprises, which is the focus of this paper.
The goal of environmental information disclosure is to reduce pollution emissions and improve environmental quality, so what is its effect on pollution reduction? Therefore, based on the implementation of environmental information disclosure policy in 2007, this paper constructs a quasi-natural experiment through the exogenous shock of the release of the Pollutant Information Disclosure Index (PITI) in 113 Chinese cities to explore its effect on the pollution emissions of enterprises, which is important to better promote policy implementation. At the same time, this paper makes use of the database of Chinese industrial enterprises and pollution emissions from 2004-2014, which makes the research results more reliable compared to urban pollution. The possible research contributions of this paper are as follows: (1) based on the data of industrial enterprises, it explores the impact of environmental information disclosure on corporate pollution emissions, which complements the related research between the two, and at the same time enriches the research on environmental economics; (2) it tests the mechanism of environmental disclosure affecting pollution emissions, and it carries out the analysis of regional heterogeneity and corporate heterogeneity; (3) it utilizes the implementation of quasi-natural experiments of environmental disclosure in 2007, and carries out an empirical test through the double-difference method to solve the difficulty of measuring the environmental disclosure and provides a new empirical methodology for the relevant research on environmental information disclosure.
Literature Review
Pollutant information disclosure has been conducted earlier in the United States, with the implementation of TRI in 1986, and since its implementation, air and water pollution levels have been significantly reduced [14-16]. García et al. [17] explored the impact of PERP on pollution emissions in Indonesia based on its policy and found that the implementation of PERP significantly reduced pollution levels and improved environmental quality, while the impact of PERP was more pronounced for firms with lower environmental ratings and for FDI firms. The GWP categorizes firms according to their environmental performance by labeling them with different colors. Green, blue, yellow, red, and black indicate environmental performance from good to poor in order, and at the same time, this information about enterprises is made public. Wang et al. [18] based on GWP policy, analyzed its implementation in Zhenjiang and Hohhot, and found that GWP can significantly reduce enterprises’ pollution emissions and improve environmental management. Powers et al. [19], based on the Green Rating Project (GRP), an empirical study using panel data from the pulp and paper industry, found that the implementation of GRP significantly and negatively affected pollution emissions. Based on the heterogeneity results, GRP was found to have a more pronounced negative impact on enterprises with poor environmental performance than on those with cleaner production, and a more pronounced negative impact on developed regions than on poor regions. However, some scholars have questioned its validity and concluded through their studies that environmental information disclosure does not necessarily reduce environmental pollution. Kathuria [20] argues that environmental information disclosure requires certain conditions to play an effective role in developing countries and that relevant, credible programs need to be developed to enable effective inspection of environmental information.
There are relatively few domestic studies on environmental information disclosure and environmental quality. Using regulatory information index and pollution emission data from 35 cities from 2011 to 2017, Zhang [21] conducted an empirical study and found that public participation can significantly reduce urban environmental pollution emissions, while regulatory information disclosure can reduce information asymmetry, make stakeholders pay attention to environmental pollution problems, and strengthen the relationship between public participation and urban pollution emissions. Using urban pollution emission data, Zhang and Sun [22] considered environmental information disclosure as an exogenous shock and constructed a DID model to conduct an empirical study, which was found to significantly reduce urban pollution emissions. Based on the mechanism analysis, it was found that information disclosure could positively promote industrial structure upgrading and technological innovation, which in turn could achieve pollution reduction goals. Based on theoretical and empirical analyses, Tian et al. [23] constructed a Logit model to explore the relationship between environmental information disclosure and residents’ health using 113 cities’ panel data and found that environmental information disclosure could positively affect residents’ health status. Mechanism analysis showed that environmental information disclosure significantly reduced urban environmental pollution and then improved health, and heterogeneity indicated the existence of regional differences. Based on provincial environmental information disclosure data, Yang and Zhao [24] measured ecological environmental quality, empirically tested the relationship between the two, and found that it significantly and positively influenced ecological environmental quality. According to regional heterogeneity, the positive relationship between the two was more significant in the eastern region and insignificant in the central and western regions. Hu and Li [25] empirically tested the effect of environmental information disclosure on urban pollution emissions by constructing a DID model using panel data from prefecture-level cities and found that it significantly reduced the level of urban pollution emissions. The mechanism analysis indicated that environmental information disclosure could promote industrial structure upgrading, improve technological innovation, and thus reduce pollution emissions, while environmental regulation could strengthen the relationship between the two. Liu and Chen [26] also empirically tested the policy effects of environmental information disclosure based on urban panel data using the double difference method and found that environmental information disclosure can significantly and negatively affect urban pollutant emissions. Meanwhile, the stronger the environmental regulation, the stronger the relationship between the two, and the pollution reduction effect of environmental information disclosure is more significant in non-resource cities. Using panel data of prefecture-level cities, Zhang and Feng [27] empirically tested the relationship between environmental information disclosure and urban carbon emissions by constructing a DID model and found a significant negative relationship between them, verifying the effectiveness of environmental information disclosure, and the heterogeneity indicated that its emission reduction effect was more obvious in the east and west regions. Some scholars’ studies have also concluded that environmental information disclosure can reduce pollution emissions [28-34].
In summary, the existing literature on the environmental effects of environmental information disclosure mainly focuses on urban pollution and lacks a comprehensive analysis of the effects of pollution emissions from industrial enterprises. Environmental information disclosure is an important part of China’s environmental pollution control process, and as a typical multi-participant environmental regulation policy implemented in China earlier, it can widely and actively mobilize multiple social actors to participate in environmental pollution control, reduce pollution control costs, and improve environmental control levels, so it is of strong academic research value and historical reference significance to study its environmental effects. It can provide a theoretical reference for the subsequent formulation of environmental information disclosure policies.
Theoretical Analysis and Hypothesis
This section draws on the relevant analyses of Hu and Li [25] and Liu and Chen [26]. With the continuous promotion of environmental information disclosure policies, the emission fees payable by firms will increase, and the abatement costs for polluting production sectors affected by environmental information disclosure will increase accordingly. Firms will adjust to reduce the output of polluting production sectors and invest more factors of production in cleaner production sectors. The factors of production in the cleaner production sector are increasing. It shows that environmental information disclosure can reduce the production of polluting products, promote the development and growth of clean production sector, expand the scale of environmental protection industry, and promote the upgrading of industrial structure; under the environmental information disclosure, all social subjects can obtain pollution information according to their own rights and increase environmental concerns, industrial enterprises are under pressure to reduce emissions, and in order to meet the relevant requirements of emission reduction, enterprises will increase pollution treatment devices or change the production method to increase the production of new products in order to improve the quality of production.
Based on this, this paper proposes hypothesis H1:
H1: Environmental information disclosure can promote industrial structure upgrading and emission reduction technology progress to reduce enterprise pollution emissions.
The high growth of China’s economy cannot be separated from the contribution of FDI, and the continuous large inflow of FDI shows the development potential of our market. In international trade, due to the strong environmental control in developed countries or regions, enterprises in developed countries or regions will move outward, however, the transferred industries are not clean and pollution-free, but mostly still industries with lower technology levels, higher pollution, and higher energy consumption because the economic development of other countries or regions is more backward, people’s income level is lower, and the expansion of industrial scale is more needed,. The inflow of these FDI will increase environmental pollution in these countries or regions. Under the implementation of environmental information disclosure, if regional environmental regulations are strengthened, FDI will consider the impact of environmental information disclosure when choosing whether to enter, and may reduce capital investment in regions with weaker environmental regulations. Meanwhile, the relevant regulations of environmental information disclosure require local governments to disclose relevant pollution penalty information, and governments will disclose environmental information cautiously to avoid controversies, and foreign risk of entry will increase due to information asymmetry [35]. Then, considering the above effects, the implementation of environmental information disclosure will reduce the inflow of regional FDI and thus reduce the pollution emissions of industrial enterprises.
Based on this, this paper proposes hypothesis H2:
H2: Environmental information disclosure can reduce FDI inflows and encourage enterprises to reduce emissions.
At present, China is actively promoting the transformation of economic development. Under the goal of pursuing high-quality economic development, it is necessary to continuously improve innovation capabilities and improve the total factor productivity of enterprises. The production and operation activities of enterprises will be affected by the intensity of local environmental regulation, and environmental regulation will have an impact on enterprise innovation [36]. According to existing research, the impact of environmental regulation on innovation is generally divided into three types: First, the Porter hypothesis is established, that is, there is a positive correlation between environmental regulation and innovation, which can improve the level of innovation and produce innovation compensation effects; Second, Porter’s hypothesis is not valid, that is, there is a negative correlation between environmental regulation and innovation, which inhibits the improvement of innovation level; third, the relationship between environmental regulation and innovation is not clear. Generally speaking, if the intensity of environmental regulation in a region is strong, the pressure on enterprises to reduce pollution will be greater, and the cost will be higher. At this time, environmental regulation may not promote the improvement of innovation capabilities, but instead create an obstacle effect. If the intensity of environmental regulation is moderate, then environmental regulation will not excessively increase the cost of pollution reduction for enterprises. At this time, it is a smarter choice for enterprises to reduce pollution emissions by increasing the level of technological innovation. Specific to this paper, environmental information disclosure is not as intensive as administrative orders, so it may increase the level of total factor productivity of enterprises.
Based on this, this paper puts forward hypothesis H3:
H3: Environmental information disclosure can improve the total factor productivity of industrial enterprises and reduce pollution emissions.
Empirical Model and Variable Definition
Empirical Model
In order to test the impact of environmental information disclosure on corporate pollution emissions, this paper uses the database of industrial enterprises and pollution emissions in China from 2004 to 2014, taking the implementation of environmental information disclosure in 2007 as the exogenous impact, and constructs the DID model through the double difference method. The benchmark model is as follows:
In the above model, the subscript i is the enterprise, c is the city, and t is the year. The explained variable Yict represents the pollution discharge of the enterprise, and the industrial wastewater discharge (lnwaterict), the industrial sulfur dioxide discharge (lnsict), and the industrial smoke and dust emissions (lndustict) are used respectively; didict = treatc × timet, treatc represents whether it belongs to a city with environmental information disclosure, and if it belongs to a city with environmental information disclosure, then the value is 1, if the city does not belong to the environmental information disclosure city, the value is 0; timet is a time dummy variable, if the city has announced the environmental information in this year, the value is 1. Otherwise, the value is 0; X'ict represents some enterprise-level control variables that affect the level of corporate pollution emissions, C'ct is a city-level control variable, and μc is a city fixed effect, which is used to control some urban factors that are not easy to quantify on corporate pollution emissions δt is the time fixed effect, controlling the factor of time and year, ϑh is the industry fixed effect, used to control the industry factor, εict is the random error term.
Variable Description and Data Source
In this paper, the explained variables, explanatory variables, and control variables are as follows:
Explained variables: Industrial pollution is the main part of environmental pollution. Considering the availability of data, the total amount of industrial wastewater discharge (lnwater), the total amount of industrial sulfur dioxide discharge (lns), and the total amount of industrial smoke and dust discharge (lndust) of industrial enterprises are used to measure enterprises. pollutant emission.
Explanatory variable: Based on the implementation of China’s environmental information disclosure in 2007, 113 cities published “PITI” and constructed a double-difference model, treatc represents whether the city belongs to the experimental group; timet represents whether the city in the experimental group disclosed environmental information in that year. The cross-term treatc × timet is an explanatory variable.
Other control variables:
Control variables at the enterprise level: use the logarithmic value of the total assets of the enterprise (lnzczj), the logarithmic value of the number of employees (lncy), the logarithmic value of the total industrial output value of the enterprise (lnzcz), and the logarithmic value of the industrial added value (lnva) as the enterprise-level control variables variable.
Control variables at the city level: Per capita national income (lnpergdp): Measured using the logarithmic value of regional per capita GDP. In order to eliminate the impact of inflation, 2004 GDP was used as the base year, and the per capita GDP was deflated and then logarithmically processed. Trade openness (lnopen): Trade openness will affect the economic growth rate of a region, and the level of economic development will affect the regional environmental quality, which is measured by the logarithmic value of the total import and export of the region. Industrialization level (indust): The higher the level of industrialization in a region, the more industrial enterprises in the region, the stronger the manufacturing capacity, and the greater the pressure on environmental protection. It is measured by the ratio of the total industrial output value of the region to GDP. Financial development level (fina): The level of regional financial development is related to the capital constraints of enterprises. The higher the level of financial development, the less difficult it is for enterprises to finance, which can save on financing costs and expand production scale. Measured as a share of GDP. Urban population level (lnpop): The larger the urban household registration population, the more energy consumption, measured by the logarithmic value of the regional urban household registration population. Medical security level (lnhsp): Measured by the logarithm of the number of regional hospitals. Degree of emphasis on education (lned): Measured by the logarithmic value of the regional government’s investment in education.
The data used in this paper mainly comes from four sources. First, China’s industrial enterprise pollution discharge database from 2004 to 2014, which is considered to be able to more accurately reflect the pollution discharge of enterprises [37]. Second, the other enterprise-level variables used come from China’s industrial enterprise database from 2004 to 2014, using the method of Brandt et al. [38] for reference, processing them, and matching the pollution emission data. Third, the economic data of prefecture-level cities comes from the “China Statistical Yearbook” and “China City Statistical Yearbook”. Fourth, the disclosure index of urban pollution source supervision information. The descriptive statistics of the variables are shown in Table 1.
Table 1.
Descriptive statistics.
Empirical Result Analysis
Overall Regression Analysis
Model (1) is estimated to analyze the impact of environmental information disclosure on corporate pollution emissions. The results are shown in Table 2. It can be found that the coefficients of did variables in columns (1), (2), and (3) are significantly negative under the fixed effect model and are significant at the 1% significance level. At the same time, the estimated coefficients of environmental information disclosure on industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions of enterprises are -0.259, -0.117, and -0.230, respectively, indicating that environmental information disclosure can significantly reduce the level of pollution emissions of enterprises, and it can reduce the emissions of three pollutants in a larger proportion, with significant emission reduction effects. This finding proves that the implementation of environmental information disclosure has achieved the expected effect of pollution reduction, probably because under the provision of environmental information disclosure, the right of all parties to be informed of environmental information can be guaranteed, and people can learn about the information of regional enterprises in terms of pollution emissions or violations, which is conducive to enhancing people’s motivation to participate in environmental protection. The enterprises’ pollution emissions will be monitored and concerned by all parties, and the enterprises will adjust the relevant production and operation methods to achieve the goal of reducing the enterprises’ pollution emissions, which in turn will improve the regional environmental quality.
Robustness Test
Parallel Trend Test
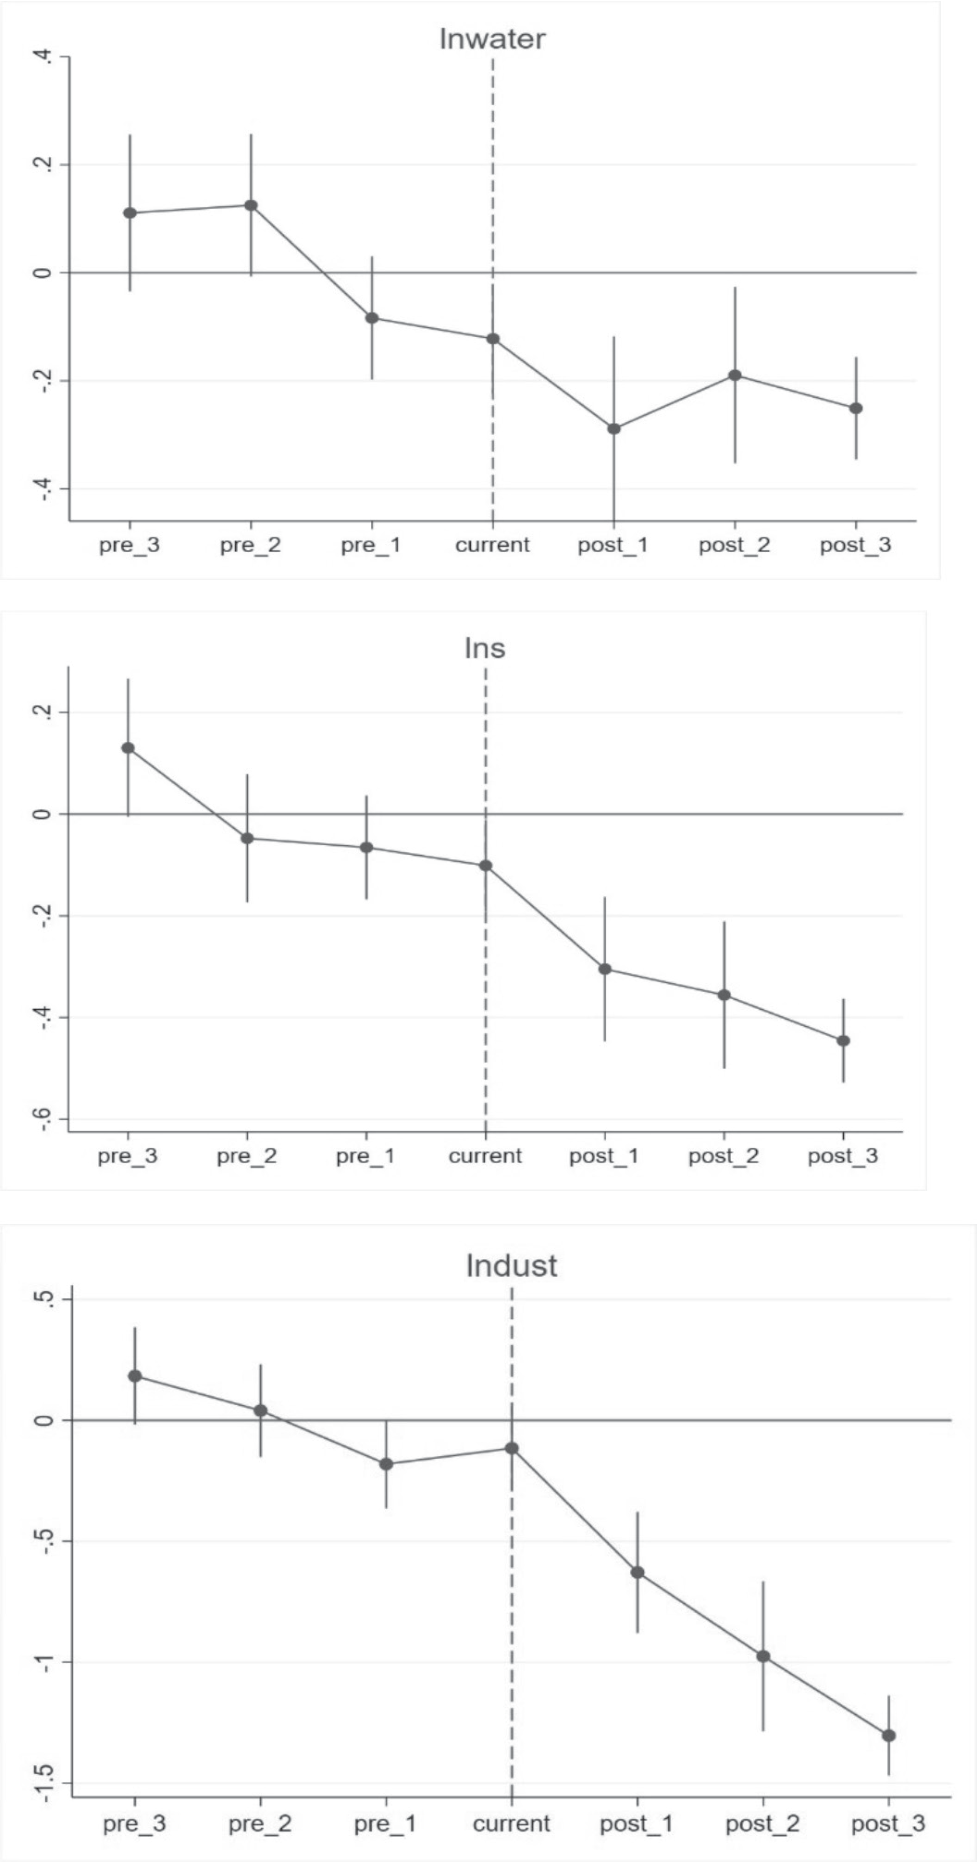
The empirical analysis in this paper uses the double difference method, and its validity is predicated on satisfying the parallel trend assumption. To test whether the research in this paper satisfies the parallel trend, this section uses the event analysis method to dynamically compare the differences in pollutant emission levels between the experimental group enterprises and the control group enterprises, and the specific results are shown in Fig. 1.
From Fig. 1, it can be seen that when the explanatory variables are lnwater, lns, and lndust, the did coefficients are relatively flat until 2007, and none of them is significant. From the dynamic changes of the did coefficients, it can be concluded that the pollution emission levels of the experimental and control groups did not differ significantly before the implementation of environmental information disclosure, which satisfies the parallel trend hypothesis. It indicates that the empirical study using the double difference method in this paper is reliable.
Placebo Test
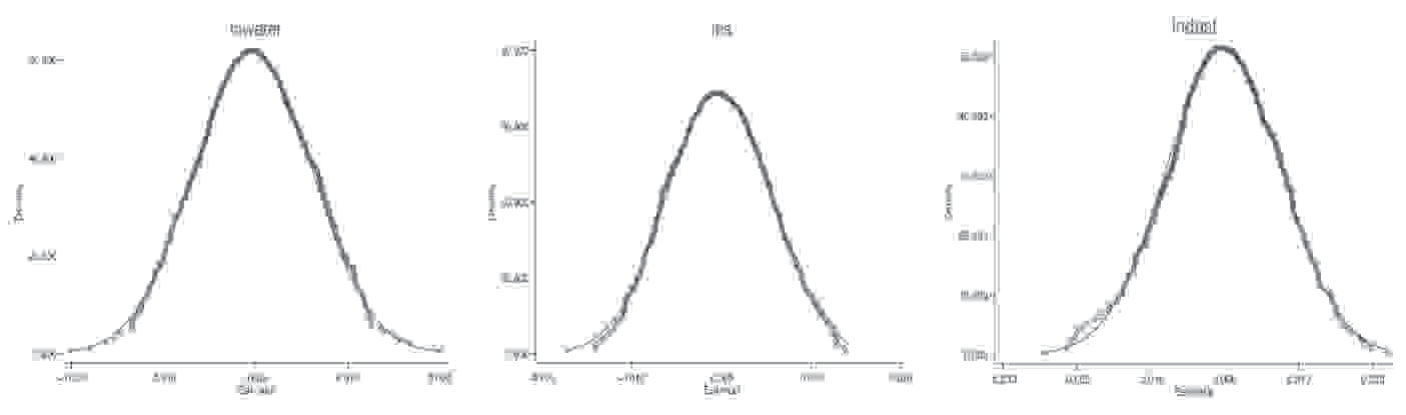
Different cities have different characteristics, and although city fixed effects are controlled for in the baseline regression model and some variables such as trade openness, degree of industrialization, and level of financial development are controlled for at the city level, this paper cannot control for all city characteristics in the study, especially those that are difficult to observe due to practical difficulties, and these difficult-to-observe ones can also affect the empirical findings. Therefore, this section conducts a placebo test to examine the effect of unobservable factors on the estimation results by conducting 500 replacement tests, the results of which are shown in Fig. 2.
It can be seen that when the explanatory variables are lnwater, lns, and lndust, their estimated coefficients are basically distributed around 0. Meanwhile, they obey a normal distribution, indicating that the unobserved factors have no influence on the empirical study results and the coefficients are unbiased.
Remove Policy Interference
In the face of increasingly serious environmental pollution, climate, environmental, and energy issues have become a global challenge. In China, in order to solve pollution emissions and improve environmental quality, some policies have been formulated to improve the pollution situation and enhance environmental management. In the baseline regression, the results show that environmental information disclosure can significantly reduce corporate pollution emissions, however, due to the complex reality, does the implementation of some other environmental protection policies affect the relationship between environmental information disclosure and corporate pollution emissions?
In view of this, some important policies are excluded in this part of the paper and then analyzed. Specifically, the 2007 sulfur dioxide emission rights paid use and trading pilot policy and the 2012 ambient air quality policy are excluded, and the pilot cities of the above policies are excluded separately, and the specific results are shown in Table 3. From them, we can see that the regression results in columns (1), (2), and (3) are the regression results of excluding the sulfur dioxide emission rights paid use and trading pilot policy. The estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (1), (2), and (3) are -0.072, -0.105, and -0.051, respectively, and the coefficients in columns (1) and (2) are significant at the 10% and 1% significance levels, respectively, and the coefficient in column (3) is significant at the 15% significance level. The coefficients of column (3) are significant at the 15% significance level, indicating that environmental information disclosure still has a significant pollution reduction effect. The regression results in column (4), column (5), and column (6) are the regression results excluding the ambient air quality pilot policy. The estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (4), (5), and (6) are -0.259, -0.117, and -0.230, respectively, and the coefficients are all significant at the 1% level of significance, indicating that environmental information disclosure can still significantly and negatively affect enterprises’ pollution emissions. In summary, after excluding the effect of policy interference, the pollution emission reduction effect of environmental information disclosure remains significant, thus supporting the findings of this paper.
Table 3.
Regression results excluding policy disturbances.
Adding Additional Covariates
To further eliminate the possible influence of area-level factors on the estimation results, this section draws on Chakraborty and Chatterjee [39] by adding the interaction term of area with the time trend primary term (γp × trend), the interaction term of area with the time trend secondary term (γp × trend2), and the area dummy variable with the interaction term of the time dummy variable (γp × γt). Considering the model degrees of freedom, this subsection examines the results from the provincial perspective, which are shown in Table 4.
It can be seen that the estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (1), (2), and (3) are -0.093, -0.062, and -0.058, respectively, and, respectively, are significant at 1%, 5%, and 10% significance levels, indicating that after adding additional covariates, the environmental information disclosure of pollution reduction effect remains significant, further verifying the robustness of the results of this paper.
Excluding New Entry and Exit of Enterprises
Since the implementation of the environmental information disclosure policy was enacted and implemented in 2007, does the entry of new firms into the market or the exit of certain firms in 2007 have an impact on the results of environmental information disclosure affecting firms’ pollution emissions? In order to investigate and examine this impact, this section excludes a sample of new and existing enterprises in 2007, respectively, for empirical testing, and the specific results are shown in Table 5.
As can be seen, the regression results in columns (1), (2), and (3) are the results of the regression excluding the new entry of enterprises. The estimated coefficients of environmental information disclosure on industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (1), (2), and (3) are -0.266, -0.117, and -0.226, respectively, and all of them are significant at the 1% significance level, indicating that environmental information disclosure still has a significant pollution reduction effect after excluding the effect of new entry of enterprises. The regression results in columns (4), (5), and (6) are the regression results excluding the effect of enterprise exit. The estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (4), (5), and (6) are -0.234, -0.007, and -0.184, respectively, and the pollution emission reduction effect of environmental information disclosure remains significant. Thus, the reliability of the conclusions in this paper is verified.
PSM-DID Test
In this section, in order to further verify the reliability of the findings in this chapter, the data were matched year by year by using the PSM-DID method and then empirically tested, and the results are shown in Table 6. It can be seen that the coefficients of the explanatory variables are all negative, and all of them are significant at the 1% significance level, indicating that the pollution abatement effect of environmental information disclosure remains significant. Thus, the robustness of the results of this paper is again verified.
Table 4.
Regression results with additional covariates.
Table 5.
Regression results excluding new entrants and exits of firms in 2007.
Endogeneity Test
The endogeneity of the information element remains by examining the effect of environmental information disclosure on corporate pollution emissions through a quasi-natural experiment, although the endogeneity problem is mitigated to some extent. Based on this, in this section, Internet penetration in prefecture-level cities is used as an instrumental variable [25], selected based on the following: First, in the information age, people learn more about current news from the internet. The more widespread the Internet penetration is, the faster and more convenient people get all kinds of information, and when pollution events occur, they will spread rapidly through the internet, increasing people’s environmental concerns, and the government, in order to maintain its reputation, is more willing to make environmental information disclosures. Second, the internet penetration rate of each prefecture-level city does not change due to changes in corporate pollution emissions, and there is no significant correlation between the two. Then, the results are verified by 2SLS, which are shown in Table 7. From which it can be seen that the estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (1), (2), and (3) are all negative, and the pollution reduction effect of environmental information disclosure remains obvious. In addition, the first-stage regression shows that the coefficient of Internet penetration is 0.011, which corresponds to a p-value of 0.000 and is significantly positively related to environmental information disclosure, while the F-value is 26.96, which is much larger than 10, rejecting the hypothesis of a “weak instrumental variable”.
Table 6.
Regression results of PSM-DID.
Mechanism Test
In this paper, the proportion of value added of tertiary industry to value added of secondary industry is used to represent industrial structure upgrading (structure), the logarithm of intermediate inputs (lnzjtr) is used to represent enterprise end pollution control, and the proportion of new product output value (xcpzb) is used to represent enterprise front-end pollution control. Drawing on the research method of Lu and Lian [40], the LP method as well as the OP method are used to measure enterprise total The LP method and the OP method were used to measure the total productivity of enterprises. Drawing on the analysis of mediating effects by Jiang [41], this section only examines the effects of environmental information disclosure on industrial structure upgrading, FDI, emission reduction technology, and total factor productivity, and the results are shown in Table 8.
It can be seen that the estimated coefficients of environmental information disclosure on industrial structure upgrading and FDI in columns (1) and (2) are 0.592 and -0.286, respectively, and all of them are significant at the 1% significance level, indicating that environmental information disclosure can significantly improve the ratio of the value added of the third and second industries and promote industrial structure upgrading; at the same time, it reduces the inflow of FDI, and the reduction of these investment activities can reduce pollution emissions and improve environmental quality to a certain extent. The estimated coefficients of environmental information disclosure on enterprises’ intermediate inputs and enterprises’ new product output value ratio in columns (3) and (4) are 0.004 and -0.007, respectively, and are significant at 10% and 1% significance levels, respectively, indicating that environmental information disclosure can positively affect enterprises’ intermediate inputs and negatively affect enterprises’ new product output value ratio, which indicates that enterprises’ pollution reduction tends to end pollution control. Columns (5) and (6) show the results of the effect of environmental information disclosure on the total factor productivity of firms measured by the LP method as well as the OP method, respectively. The estimated coefficients of environmental information disclosure on them are 0.011 and 0.015, respectively, and all of them are significant at the 1% significance level, indicating that environmental information disclosure can significantly improve the total factor productivity of enterprises, promote pollution abatement, improve the competitiveness of enterprises, and contribute to the sustainable development of enterprises. Thus, the hypothesis of this paper is verified.
Urban Heterogeneity
Resource-Based and Non-Resource-Based Cities
Each city has different resource endowments, and this paper draws on the National Sustainable Development Plan for Resource-Based Cities (2013- 2020) issued by the State Council in 2013 to classify cities into two types: one is resource-based and the other is non-resource-based. The specific impacts are then empirically tested, and the results are shown in Table 9.
As can be seen from Table 9, columns (1), (2), and (3) are the regression results for resource-based cities, and the estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (1), (2), and (3) are 0.005, -0.065, and -0.088, respectively, and they did coefficients all fail the significance test, indicating that the effect of environmental information disclosure on corporate pollution emissions is not significant in resource-based cities. Because the development of resource cities is more dependent on their own resource endowment, the industrial structure is more homogeneous, the development mode is more sloppy, and the pollution emissions are greater, they often fall into the “resource curse”, and environmental information disclosure does not have as strong a binding force as administrative command type environmental control; therefore, the effect of environmental information disclosure in resource cities is not significant. Therefore, the effect of environmental information disclosure on pollution reduction in resource-based cities is not significant. The regression results in columns (4), (5), and (6) are for non-resource-based cities. The estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (4), (5), and (6) are -0.161, -0.132, and -0.062, respectively, and the coefficients of the explanatory variables did are all negative in columns (4). The coefficients of the explanatory variables did are all negative; column (4), column (5) are all significant at the 1% level of significance, and column (6) is also significant at the 15% level of significance, indicating that the pollution reduction effect of environmental information disclosure is more significant in non-resource cities because the economic development of non-resource cities does not rely heavily on resource endowment, and under the influence of environmental information disclosure, enterprises are more likely to change their production and operation methods or improve their technology to reduce pollution emissions.
Table 8.
Mechanism test results.
Table 9.
Regression results for resource and non-resource cities.
Coastal and Non-Coastal Areas
There are significant differences in the level of economic development in China between regions; coastal areas have a high degree of marketization, economic activity, and a better business environment, and enterprises will be more willing to carry out production and investment activities, and thus the regional environmental quality decreases, while inland areas are less attractive to enterprises than coastal areas. For this reason, this section examines the differences between the impact of environmental information disclosure on corporate pollution emissions in coastal and non-coastal areas. The specific results are shown in Table 10.
Table 10.
Regression results for coastal and non-coastal areas.
As can be seen from Table 10, columns (1), (2), and (3) are the regression results for coastal areas, and the estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (1), (2), and (3) are -0.207, -0.186, and -0.214, respectively, and the coefficients of the explanatory variables did are all negative, and all of them are significant at 1% significance level, indicating that in coastal areas, environmental information disclosure can significantly reduce regional enterprises’ pollution emissions, probably because in coastal areas, the economic level is higher, people have higher requirements for environmental quality and are more concerned about enterprises’ environmental performance, and enterprises will be more proactive in disclosing environmental information to reduce their pollution emissions. Columns (4), (5), and (6) are the regression results for non-coastal areas. The estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (4), (5), and (6) are 0.053, -0.073, and 0.049, respectively, and only the coefficient in column (5) passes the significance test, probably because the economic development of non-coastal areas is more backward, the environment accommodates more absorption space, the local area pays more attention to economic development, and the people pay less attention to environmental protection; therefore, the effect of enterprise pollution reduction is not significant.
Areas with Strong and Weak Environmental Regulations
Because of the different levels of economic development and environmental pollution in each region of China, the strength of environmental regulation varies between regions. The stronger the environmental regulation, the stronger the pollution regulation, which is more helpful to pollution emission reduction, while the weaker environmental regulation does not constrain the enterprises as much as the regions with strong regulation. For this reason, this section is divided according to the regional PITI index to examine the differences in the impact of environmental information disclosure on corporate pollution emissions in regions with strong environmental regulation and those with weaker environmental regulation, and the results are shown in Table 11.
As can be seen from Table 11, columns (1), (2), and (3) are the regression results for regions with stronger environmental regulations, and the estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (1), (2), and (3) are -0.281, -0.345, and -0.206, respectively, with the coefficients of all explanatory variables being negative. Columns (1) and (2) are significant at the 1% significance level, while column (3) is not significant, indicating that environmental information disclosure can significantly reduce the pollution emissions of regional enterprises in areas with strong environmental regulations, because the more constraints the enterprises are subjected to in areas with strong environmental regulations, the more enterprises will take the initiative to reduce their pollution emissions. Columns (4), (5), and (6) are the regression results for regions with weaker environmental regulations. The estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (4), (5), and (6) are -0.056, 0.076, and -0.436, respectively, but they do not pass the significance test. This may be due to the fact that enterprises in areas with weaker environmental regulations are subject to less pollution regulation, and they do not face greater pressure to disclose environmental information and reduce pollution emissions, thus making the effect of pollution reduction by enterprises not significant.
Table 11.
Regression results for areas with strong and weak environmental regulations.
Enterprise Heterogeneity
State-Owned and Non-State-Owned Enterprises
This paper draws on Sheng and Bu [42] to classify enterprises into two categories: state-owned enterprises and non-state-owned enterprises, and the results are shown in Table 12. Columns 1, 2, and 3 are the regression results for state-owned enterprises, and columns 4, 5, and 6 are the regression results for non-state-owned enterprises. f According to the results in the table, the pollution abatement effect is greater at the level of non-SOEs, which is due to the fact that SOEs have a closer relationship with local governments, undertake economic development and employment tasks, are protected by local governments, have no incentive to take the initiative in pollution abatement, and environmental regulation has less impact.
Exporting and Non-Exporting Enterprises
This In this section, enterprises are divided into exporting and non-exporting enterprises to test whether there is a difference in the pollution reduction effect, and the results are shown in Table 13.
As can be seen from Table 13, columns (1), (2) and (3) are the regression results for exporting enterprises, and the estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions and industrial soot emissions in columns (1), (2) and (3) are -0.258, -0.100 and -0.204, respectively, and columns (1) and (3) are significant at significant at 1% significance level, column (2) is not significant; regression results for non-exporting enterprises in columns (4), (5), and (6), the estimated coefficients of environmental information disclosure on enterprises’ industrial wastewater emissions, sulfur dioxide emissions, and industrial soot emissions in columns (4), (5), and (6) are -0.211, 0.004, and -0.245, respectively. Columns (4) and (6) are significant at the 1% significance level, while column (5) is not significant. It indicates that the pollution reduction effect of environmental information disclosure is more significant among exporters.
Table 12.
Regression results for state-owned and non-state-owned enterprises.
Table 13.
Regression results for exporting and non-exporting enterprises.
Conclusions and Policy Implications
Environmental information disclosure is an important tool to carry out pollution reduction, which can promote the joint participation of multiple subjects, reduce the cost of pollution control, and improve the level of governance. This paper explores the pollution abatement effect of environmental information using the implementation of environmental disclosure as a quasi-natural experiment.
It has been found that environmental information disclosure can significantly reduce pollution emissions from industrial enterprises. The results indicate that the implementation of environmental information disclosure produces pollution abatement. Moreover, according to the mechanism analysis, environmental information disclosure can reduce pollution emissions by promoting industrial structure upgrading, technological progress in emission reduction, reducing FDI inflow, and improving the total factor productivity of enterprises. However, probably due to the fact that front-end pollution control requires more capital investment, companies will be more inclined toward end-end pollution control. The pollution reduction effect differs across city types and is more pronounced in non-resource cities, coastal areas, and regions with strong environmental regulations. It is also more pronounced in non-state owned enterprises and exporting enterprises under the distinction of enterprise heterogeneity.
Based on the empirical results of this paper, the following countermeasures are proposed; First, the government should continue to promote the process of environmental information disclosure in depth, establish unified standards and norms, disclose relevant information in a timely manner, safeguard the rights of all parties to be informed of environmental protection information, and enhance the level of environmental governance. Second, it should continue to promote supply-side structural reform, expand the scale of clean industries, reduce the proportion of polluting production, and optimize the industrial structure. At the same time, it should encourage and subsidize enterprises to strengthen scientific and technological research and development activities, so that their pollution management can be shifted from end-of-pipe pollution control to front-end pollution management, reduce energy consumption and pollution emissions, and improve the competitiveness of enterprises. Third, change the development mode of resource-oriented cities, maintain the appropriate intensity of environmental regulations, so that the production mode is cleaner, and at the same time, strengthen the supervision and incentives for the pollution emissions of state-owned enterprises, so that the state-owned enterprises have more incentives to carry out pollution reduction.
Limitations and Future Research
The limitations of this paper are that it fails to measure the extent of environmental information disclosure by each industrial enterprise and does not examine the impact of other pollutants in industrial enterprises. Also, because pollution has spillover, further consideration of spatial correlation is needed in subsequent studies. Environmental information disclosure in the implementation of the process may involve corporate resistance, public participation, and other issues. This paper will subsequently rely on this research to add relevant cases and case studies as a way to improve the value of the article.

