

Introduction
Since the reform and opening up, China’s economic prosperity has lasted for nearly four decades and made an important contribution to the world economy. However, due to the crude exploitation of the ecology by traditional development modes such as industrialization and urbanization, China is facing a critical water pollution crisis. According to the Ministry of Water Resources, China’s per capita water resources, as a basic natural resource and a strategic economic resource, are only 1/4 of the world average, and it is one of the 13 most water-poor countries in the globe. Numerous studies have shown that industrial wastewater is one of the main causes of water pollution in China [1, 2], and its massive water consumption and wastewater discharge not only pose great challenges to environmental management, but also constrain the sustainable development of China’s economy. In accordance with the principle “Whoever pollutes is responsible”, industrial enterprises should actively carry out their ecological construction responsibilities and reduce pollutant emissions. However, the negative externality of environmental pollution does not give enterprises enough incentive to participate in [3]. Therefore, in the face of the market failure in environmental protection, the government needs to intervene appropriately.
Taxes are an effective method for the government to adjust the market and play a fundamental role in national governance. In order to force enterprises to strictly abide by the principle of “polluter pays” and promote the scientific distribution of ecological resources in production, China officially implemented the “Environmental Protection Tax Law of the People’s Republic of China” (hereinafter referred to as environmental tax) in 2018. Compared with the previous discharge fee system, which belonged to administrative regulations, the environmental tax is both stricter and more flexible. It is not only significantly better than the discharge fee in the law enforcement and supervision systems, but also more reasonable and rational designs in terms of tax rate standards and emission reduction discounts, which is a milestone for China’s construction of an ecological society.
As one of the main approaches to environmental protection, environmental taxation has been widely implemented in developed countries [4]. Scholars have affirmed its contribution to innovation development, ecological protection, and other aspects [5-10]. However, for the green dividend of environmental tax, the previous studies mainly focused on the effects, such as atmospheric or overall green governance, and little research has been conducted on industrial water pollution. Therefore, as the first tax law in China to promote the construction of an ecological society, can the environmental tax effectively reduce industrial water pollution to achieve its purpose? And does the effect have any difference among different regions? If so, what is the mechanism behind it? Answering these questions is crucial for unraveling the causal link between environmental tax and water ecology and can provide a policy reference for China to further optimize and adjust its green tax system.
Based on the above analysis, the study first analyzes the theoretical framework, and then, we take environmental tax reform as a quasi-natural experiment to construct a DID model. Using panel data from 274 cities for the period from 2012 to 2020, we systematically examined the causal relationship between environmental tax and industrial water pollution. Secondly, on the basis of the parallel trend test, a series of robustness tests such as propensity score matching and placebo tests are used to alleviate the endogeneity problem in the model. Finally, this paper constructs a DDD model to reveal the channels between environmental tax and industrial water pollution. According to the existing studies, our possible contributions can be summarized as follows: Firstly, most prior literature examines the impact of environmental tax from perspectives such as air pollution control, regional development efficiency, enterprise performance, and technological innovation, but these studies still lack sufficient discussion on the impact of environmental tax on industrial water pollution. Therefore, based on prefecture-city data, this study identifies the causal relationship between environmental tax and industrial water pollution, providing rational empirical support for more precise green tax tools. Secondly, as the executor of environmental tax, the local government’s law enforcement rigidity will directly affect the realization of the environmental tax “double dividend”. Meanwhile, technological innovation, as one of the costs that must be considered in production and operation, will also further superimpose or weaken the policy effect of environmental tax. Therefore, this paper incorporates law enforcement rigidity and green innovation into a unified empirical framework, striving to reveal more comprehensively and systematically the mechanism of environmental tax on industrial water pollution from multiple dimensions.
The rest of our study is structured as follows: The second section provides a brief review and summary of related literature. The third section presents the research hypotheses of this study, which are based on policy evolution and related theories. The fourth section is the research design, including method selection and model construction, data sources, and variable settings. The fifth and sixth sections present empirical results analysis and mechanism discussion. The final section is the summary of this study.
Literature Review
The causal relationship between environmental regulations and industrial pollution reduction has always been a topic of academic research. This study mainly reviews and summarizes the relevant literature on aspects of the influence factors of industrial water pollution and the economic results of environmental tax.
Due to the influence of geographical location, resource endowment, and other factors, there is a geospatial agglomeration effect among industrial enterprises, and their by-product of industrial wastewater also has the same characteristics subsequently [11]. Hu et al. [12] constructed the spatial model, resulting in the intensity of industrial wastewater presenting a pattern of “high in the west and low in the east”, and they believed that the Hu Huanyong Line could be roughly used as a dividing line between high and low industrial wastewater discharge. According to Li et al. [13], population size and water pollution show a dynamic and positive relationship. Population and economic agglomeration are often accompanied by the expansion of industrial scale in developing countries, and factors such as industrial development and structure also affect the discharge of industrial wastewater [14– 16]. And Deng et al. [17] empirically explored that foreign investment has a significant “pollution halo” effect on industrial wastewater from the perspective of industrial agglomeration. From a micro perspective, industrial wastewater discharge is essentially caused by the backward technology level and inefficient resource utilization of polluting enterprises, which is manifested by low total factor productivity, relying on high consumption of resources, and excessive discharge of pollution to maintain survival and production. Therefore, industrial enterprises should accelerate the innovation of energy consumption structure [18], promote the improvement of green innovation, use the scale effect of enterprise agglomeration to enhance market competitiveness [19, 20], and achieve pollution control and reduction of industrial wastewater.
Another major factor in industrial wastewater is environmental regulations. Guo et al. [21] and Pan et al. [22] found that heterogeneous environmental regulations, including command-and-control, market-based, and public participation, have a significant effect on industrial water pollution management. Specifically, the command-and-control environmental regulation “10-Point Water Plan” issued by the Chinese government in 2015 was able to increase the water information disclosure of water-polluting enterprise [23] and trigger the Porter effect to improve the sewage disposal system [24]. For market-based environmental regulations, most scholars have focused on the water tax reform [25], which was explored as a quasi-natural experiment and found that it was able to raise the water conservation awareness of agriculture and promote the utilization efficiency of water [26]. Shen et al. [27], on the other hand, studied from the perspective of public participation and willingness and found that urban residents mainly influence the ecological status of urban water environments by raising public awareness of environmental responsibility.
Environmental tax, as a very important and fundamental type of market-based environmental regulation [28], was first mentioned in Pigou’s “Welfare Economics”. It believes that the use of tax can regulate the negative externalities of enterprise, which is the theoretical basis of the “double dividend” effect. Tullock [29], who studied the impact of environmental tax on water resources in developed countries, argued that they could decrease pollutant emissions while avoiding the distortionary effects of other taxes and promoting economic growth. Pearce [30] believed that environmental tax could not only reduce environmental pollution, but also promote innovation in clean technology, thus creating a “double dividend” effect. Existing studies generally agree on the significant achievements of environmental tax in air pollution management [31], which can eliminate backward production capacity to achieve regional industrial upgrading [32], and thus improve regional green total factor productivity [33]. At the same time, according to Porter’s hypothesis theory, a reasonably designed and strictly enforced environmental regulation can force enterprises to increase green investment [34–36], increase financial support for promoting green technology innovation, help enterprises achieve their green transformation, and ultimately improve enterprise ESG [37, 38]. However, the “green dividend” of environmental tax on water pollution has not yet reached a unified conclusion in academia. Yu et al. [39] used the total amount of local pollution discharge fee to construct panel data for discussion and concluded that the increase of the fee standard can reduce industrial wastewater emissions and effectively improve the water environment, while Lu et al. [40] argued that, due to the “incomplete implementation” of environmental regulation and the low tax rate of water pollutants, there was no negative effect on industrial water pollution emissions from environmental tax.
Overall, the existing literature helps us to explore the economic benefits and environmental effects of environmental tax, which provides a solid foundation for this study, but there are still some shortcomings: (1) The existing research on environmental regulation in industrial water utilization mostly explores production inputs such as water consumption and green factor productivity, but less the outputs, especially the non-expected outputs aspect of water pollution, for deeper quantification analysis. (2) In the area of environmental tax, most of the literature has focused on its effect on overall environmental or air pollution protection, and only a few have examined the effect on industrial water pollution based on the total amount of pollution discharge fee. However, it is difficult to avoid the endogeneity problem that the higher the pollution, the higher the fee charges, which could not accurately identify the causal link between them, nor can it separate the effect of other socio-economic factors.
(3) Most of the research on industrial water pollution has mostly focused on the provincial or regional level, ignoring the possible individual differences among cities within provinces.
Policy Evolution and Research Hypothesis
Policy Evolution
As a policy approach based on price modulation in environmental governance, China’s exploration of the environmental tax system can be generally divided into three stages: the construction and full implementation stage of the pollution discharge fee system (1979-2002); the total amount adjusting stage of the pollution fee (2003-2017); and the formal implementation stage of environmental tax (2018-present).
The pollution discharge fee system was one of the longest-implemented market-incentive environmental regulations in China. In 1979, the official promulgation of the “Environmental Protection Law (Trial)” set the legal status of the pollution discharge fee system. In 1993, the “Notice on the Collection of Pollution Discharge Fee” first reflected the idea of total control: the fees were charged for pollution that did not exceed the standard. Back in 2003, China changed the basis, scope, and standards of the fee system according to a series of laws and regulations. It could be noticed that the fee was not charged by single-factor concentration but by multi-factor total charges. Also, the charge standards were appropriately increased, and the objects of the collection were expanded from enterprises and institutions to all units and individual industries. This marked the completion of the most critical reform in the history of China’s pollution discharge fee system.
With the implementation of the “Environmental Tax Law” on January 1, 2018, China’s pollution discharge fee system, which has been in place for more than 30 years, has been succeeded by the environmental tax. To ensure a smooth transition from the fee system to the tax system, there are no significant differences between them in terms of collection standards, objects, and scope. However, to solve the problem of compulsory and enforcement problems that were criticized during the pollution discharge fee period and to better exert the double dividend effect of environmental tax, there are still some differences between the two systems: First, the legislation for the environmental tax. The execution of environmental tax is strengthened to improve the collection rate. For a long time, the central government continuously formulated and adjusted the fee system to better control pollutant emissions. Nevertheless, existing research believed that the expectation of a fee system had not been achieved due to the phenomenon of “incomplete enforcement” [41]. Compared with the fee system, the collection behavior of the environmental tax is guaranteed by legal obligation, and the legal effect is stronger. Second, by increasing the tax rate, the emission reduction of the polluting units is promoted. Another reason why the fee system failed to achieve the goal of enterprise pollutant reduction is that the collection standard was still too low compared with the cost of pollution control, and the economic stimulus for enterprise emission reduction behavior was insufficient. Hence, after the formal imposition of environmental tax laws, some regions have taken the initiative to raise the tax rate to stimulate enterprise adjustment behavior, consciously control pollution, and internalize environmental externalities. Third, through the reform of the environmental tax, the tax system is greened. The inclusion of the pollution discharge fee in the tax system is undoubtedly a significant step. The greening of the tax system mainly refers to the adjustment and use of tax revenue and the overall structure. The reform transforms the tax burden of labor factors into other production factors to reduce distortion of existing taxes in capital and labor factors, create more employment opportunities, and thus play the double dividend effect of environmental tax.
Research Hypothesis
In theory, an environmental tax refers to a series of taxes that are conducive to pollution control and reduction, environmental protection, etc. It can increase the cost of per unit pollutant emission by levying a tax, making the private marginal cost of pollution behavior consistent with the social marginal cost. Eventually, the tax will internalize the negative externality of enterprises and force enterprises to control pollution while pursuing economic benefits. However, if the environmental tax rate is set too high, it will heavily increase the tax burden on polluting enterprises, making output more oriented towards consumption and inhibiting regional economic development. Conversely, if the tax rate is set too low, it will not be able to motivate enterprises to increase capital investment in pollution prevention, resulting in enterprises paying for pollutant emissions.
In reality, as a market-based environmental policy tool, the original pollution discharge fee mainly relies on administrative rules, which are not included in the tax system. Although it has internalized the pollution costs of polluted enterprises and stimulated their willingness to reduce and control pollution [41], local governments still have the tendency to “sacrifice the environment for the economy” in the phenomenon of “promotion tournaments”. In addition, the fee collection standard is lower than the enterprise’s pollution control cost, which has greatly reduced the policy implementation effect. Unlike the former, environmental tax not only sets up the compulsory levy through legislation, but also effectively stops administrative intervention and the enterprise’s rent-seeking behavior by changing the main body and mode of levy and management. Therefore, the strength of enforcement is much higher than the pollution discharge fee. Moreover, after the formal implementation of environmental tax, each province has the right to determine the tax rate according to its own economic development level and environmental carrying capacity within the statutory range. The increase in tax rates will directly increase the enterprise tax burden, which will force rational producers to use renewable, clean energy, improve production processes, or optimize emission equipment through green technology innovation, which will lead to a reduction in pollutant emissions. Based on this, this study proposes the following research hypothesis:
Hypothesis 1: The implementation of an environmental tax can effectively decrease industrial water pollution emissions.
The actual environmental tax burden borne by enterprises is jointly determined by the statutory tax rate and tax compliance. Legitimacy theory holds that environmental regulation is equivalent to a mandatory requirement for enterprises, guiding them to engage in environmental management. When the government’s environmental protection authorities have the power to punish or even force the closure of polluting enterprises, enterprises can only reduce pollution emissions in order to obtain legitimacy and recognition. Nevertheless, the legitimacy theory requires strong support from regional collection efficiency. During the period of pollution discharge fees, local economic growth had a much higher priority than environmental protection, and there was a lot of flexibility in the collection of fees, which ultimately made it a “blank check”. Unlike the former, environmental tax not only improves the legal rigidity of tax collection, but also helps to reduce the information asymmetry between the collection agency and polluting enterprises in terms of collection subject and mode. The two measures together have improved the efficiency of tax collection and management; secondly, the change in fund management form cuts off the direct connection between the local government’s income and expenditure on environmental matters, and the central-local income sharing turns to the local government’s income sharing. Both measures urge local governments to increase their tax efforts and improve their collection efficiency; thirdly, positive incentives such as discounts for taxpayers and negative constraints such as penalties are conducive to improving taxpayers’ voluntary compliance with environmental tax, thus curbing water pollutant emissions at the source. Therefore, this study puts forward the following hypothesis:
Hypothesis 2: In areas with poor law enforcement, environmental protection tax has a more significant inhibitory effect on industrial water pollution emissions.
Lots of studies have shown that the implementation of environmental tax can stimulate enterprises to engage in green technology innovation [42]. According to the Porter hypothesis, reasonable and strict environmental regulation can give enterprises a greater incentive to phase out existing high-pollution production processes and turn to greener production in order to face environmental enforcement pressure. Based on green technology innovation, enterprises innovate energy use technology and clean production technology at the input to reduce the generation of pollutants; at the output, they reduce pollutant emissions by installing and improving pollutant treatment equipment, thus achieving an overall decline in enterprise pollutant emissions [43]. However, the cost of the compliance hypothesis suggests that when the environmental tax rate exceeds a certain level, the excessive tax burden increases the green compliance cost of enterprises, which will crowd out part of the green capital and lead to lower productivity in enterprises. However, according to the existing literature, China’s environmental tax rate is still at a low level, and there is still an “incremental effect” on the reduction of pollutants. Based on this, this study proposes the following hypothesis:
Hypothesis 3: In areas with low levels of technological innovation, environmental protection tax can play a greater role in curbing industrial water pollution emissions.
Materials and Methods
Model Selection
The focus of this study is on the effect of environmental tax on industrial water pollution. Therefore, we use the standard of whether cities raise the tax rate before and after the implementation of environmental tax for grouping and use the DID method for causal identification. The control group is the 154 prefecture-level cities that consistent the tax rate with pollution discharge fee after the implementation of environmental tax, and the treatment group is the 120 prefecture-level cities that raised the environmental tax rate. The green effect of the environmental protection tax on water resources was evaluated by comparing the water pollution intensity between the control group and the treatment group. The specific model is constructed as follows:
Where i represents city; t represents year; α0 is the intercept term; Treat is the regional dummy variable; Time is the time dummy variable; X indicates a series of control variables; φi represents individual city fixed effect; γt represents time fixed effect; and ε represents the error term. Also, to deal with autocorrelation, all regression equations use city-level clustered standard errors.
Variables Selection
Explained Variable
Water pollution intensity (Pollution): At present, industrial water pollution discharge is a serious threat to China’s water environment. Referring to Zhou et al. [24], we use industrial wastewater discharge per unit GDP as a proxy variable for industrial water pollution. Currently, China is in a critical period of economic development transformation, and development based on GDP is no longer the only goal; the realization of ecological civilization in economic growth is the ultimate destination of development, so it is more reasonable to adopt pollution emission intensity for the evaluation of the actual environmental pollution status.
Explanatory Variables
Regional dummy variable (Treat): In the process of environmental tax reform, the central government only sets the upper and lower limits of the environmental tax rate, while local governments determine the specific tax rate according to their economy and environmental conditions. For some provinces, the tax rate was unchanged, which is consistent with the pollution discharge fee. But the other 12 provinces, including Beijing, Hunan, and Hainan, chose to increase the tax rate. Therefore, this study sets the grouping variable. If the environmental tax rate of the provinces was raised, Treat – 1; otherwise Treat – 0.
Time dummy variable (After): The “Environmental Tax Law of the People’s Republic of China” was officially implemented on January 1, 2018. Therefore, this study sets the time dummy variable. After – 1 represents the period after the official implementation; After – 0 represents the period before the official implementation.
Control Variables
To precisely identify the environmental effect of environmental tax on industrial water pollution, based on existing studies, this study controls the following variables at the prefecture-level city level: (1) Degree of industrialization. It is measured by the proportion of the city’s secondary industry output to the current year’s GDP. Pollution emission is closely related to industrial structure, especially the higher the industrial output value, the greater the dependence on industrial development, and the more industrial pollutants are emitted. (2) Urban greening rate. It is expressed as the green area rate of the built-up area. A higher urban greening rate helps to reduce the concentration of water pollution and thus improve environmental quality.
(3) Water endowment. Measured by the total urban water supply. The water resource endowment of a region will limit the amount of water used in that region. (4) Science expenditure. This is represented by the government’s total year-end science expenditures. Generally speaking, the larger the expenditure on science, the faster the technology development, the more efficient the water pollution control, and the greater the impact on the water environment. (5) Population size. Measured by the total population of the city at the end of the year. In general, the size of the population has a more direct impact on the quality of the water environment. The larger the population, the better the degree of industrialization and urbanization, and the higher the water pollution emissions. (6) The level of government intervention. Expressed in terms of the city’s budget expenditure as a proportion of the year’s gross domestic product.
Data Description
This study selects the annual panel data of 274 prefecture-level cities from 2012-2020 as the research sample to examine the impact of environmental tax on industrial water pollution intensity. Limited by the availability of data, some municipal data, such as Tibet, Haidong, and Bijie, are removed from this study. All data in this article are obtained from the China Urban Statistical Yearbook, China Statistical Yearbook, China Industrial Statistical Yearbook, and the information from municipal statistical yearbooks, and the missing data is supplemented by the linear interpolation method.
The results of the descriptive statistics for the main variables are shown in Table 1. The mean value of industrial water pollution intensity (Pollution) is 2.591, the standard deviation is 2.67, the maximum value is 43.717, and the minimum value is 0.016, indicating strong individual heterogeneity of industrial water pollution intensity among cities. The control variables are basically consistent with existing studies.
Results and Discussion
Results of DID
The difference in tax rates between different provinces provides an opportunity for the DID method. Table 2 shows the regression results of model (1). Column (1) is the estimation result without control variables. It shows that the regression coefficient of Treati × Aftert variable is negative and passes the 5% significance test, indicating that the areas where the environmental tax rate was raised significantly suppress the intensity of industrial water pollution, which in turn improves the regional water quality. Columns (2) - (7) are the results of adding relevant control variables. It can be seen that the absolute value of the Treati × Aftert variable becomes larger, and the R-squared is better than that without the inclusion of control variables. This indicates that after controlling other influencing factors, the implementation of environmental tax has enhanced the effect of reducing industrial water pollution intensity, which verifies hypothesis 1. Specifically, among the control variables, the urban greening rate is negative at the 5% significance level, indicating that a region’s green space coverage can effectively suppress regional water pollution. While technological progress is significantly positive, a possible explanation is that government science expenditure has not been converted into technological innovation, but instead has inhibited technological innovation due to potential reasons such as collusion between government and enterprises. In addition, the estimated coefficient of water resource endowment is significantly positive, which may be because water-rich areas have lower sensitivity to water scarcity and are unwilling to invest a lot of resources to develop water-saving and water-treatment technologies, and local residents have generally weak water-saving awareness.
Table 1.
Descriptive statistics of variables.
Table 2.
DID regression results.
Robustness Tests
Parallel Trend Test
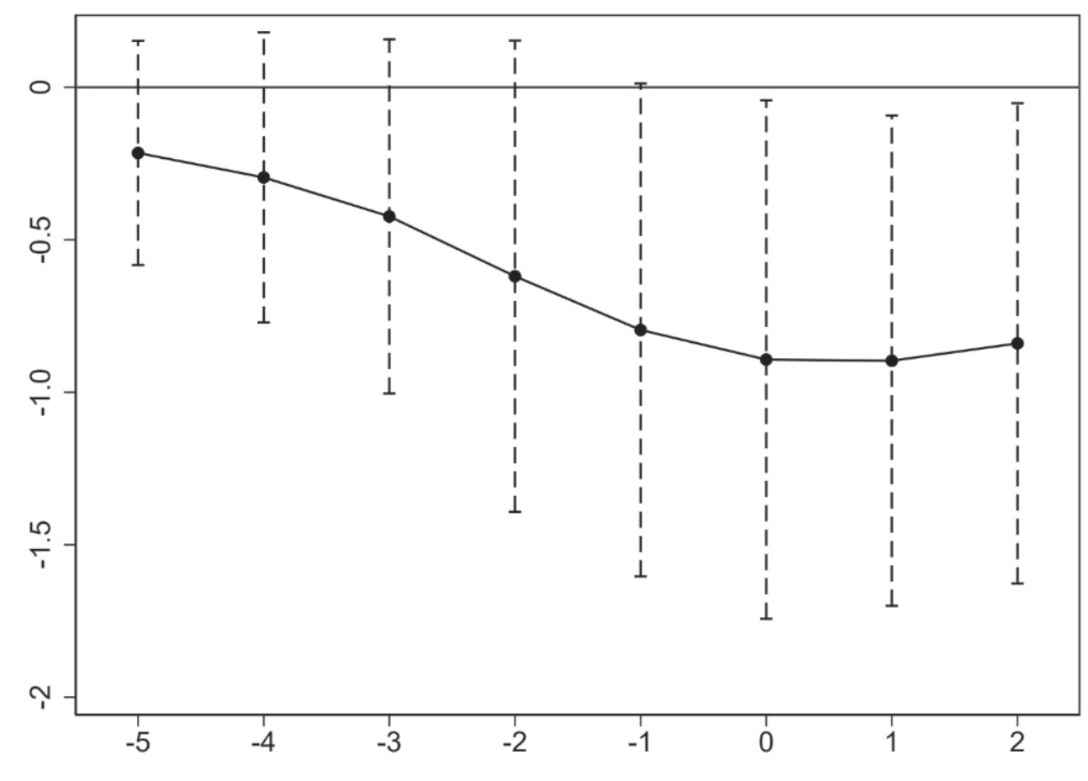
The essential prerequisite for effective estimation by the DID method is to satisfy the parallel trend test, which requires that the control and treatment groups maintain the same or similar trends in their outcome variables before the policy shock. Referring to Jacobson et al. [44], this study uses the event analysis method to conduct the parallel trend test. To avoid the problem of collinearity, the first year of the sample period is used as the reference year for regression. The specific model is constructed as follows:
where Year is a time dummy variable that takes 1 when the observation year is in year t, and otherwise, the value is 0. Other variables are defined in the same way as in the regression model (1). β1 represents the policy effect in the observation year. Fig. 1 shows the annual development effects of the coefficient and the 95% confidence intervals for 2012 and 2020.
The regression results show that before the implementation of the environmental tax, β1 is not significant, indicating that there is no significant difference between the industrial water pollution intensity of the treatment and control groups; however, after the implementation of the environmental tax, β1 is negative at the 95% significance level, indicating that the industrial water pollution intensity of the treatment group decreases after the policy shock and the policy effect continues to be effective. The estimation results not only verify the parallel trend hypothesis, but also indicate the continuity of the policy effect.
Placebo Test
To rule out the interference of other unobservable variables, such as major national economic, political, and environmental events, on the baseline regression, this study refers to Guo et al. [45] and adopts the placebo test to re-measure the baseline regression. Specifically, we use the bootstrap method to randomly select 120 cities from 274 city samples as the false treatment group and perform regression according to model (1). Then, in order to enhance the persuasiveness of the random results, we repeat this process five hundred times. Fig. 2 draws the kernel density distribution of the random results, where the black dots are the estimated coefficient of the false treatment group, the horizontal line is the 10% significance level line, and the vertical line is the estimated coefficient of baseline regression (i.e., α1 – 0.496). Observing Fig. 2, it can be found that the coefficients of randomly selected treatment groups are mainly distributed around 0 and are close to normal distribution. Most of the estimated values do not pass the significance test at the 10% level, and the regression coefficient value of the baseline regression result falls at the end of the distribution line, meaning its absolute value was much larger than that of the false estimate. This indicates that other unobservable factors have little impact on the basic result of this study and the conclusion that environmental tax inhibits industrial water pollution remains a concern.
PSM-DID
Using whether the tax rate is raised or not as the standard for dividing the treatment group and the control group may not ensure the randomness of the quasi-natural experiment. In order to eliminate the impact of sample selection bias on the results of the baseline regression, we further employ the PSM-DID method to conduct robustness tests. This study uses the control variables of model (1) as matching covariates to build a logit model and uses 1:2 nearest neighbor matching method to perform matching. After this, the matched samples are used to re-regress the model (1). Column (1) in Table 3 shows the results of PSM-DID. The estimation result of Treati × Aftert variable is still significantly negative at the 5% level, indicating that the regression result of this paper is robust.
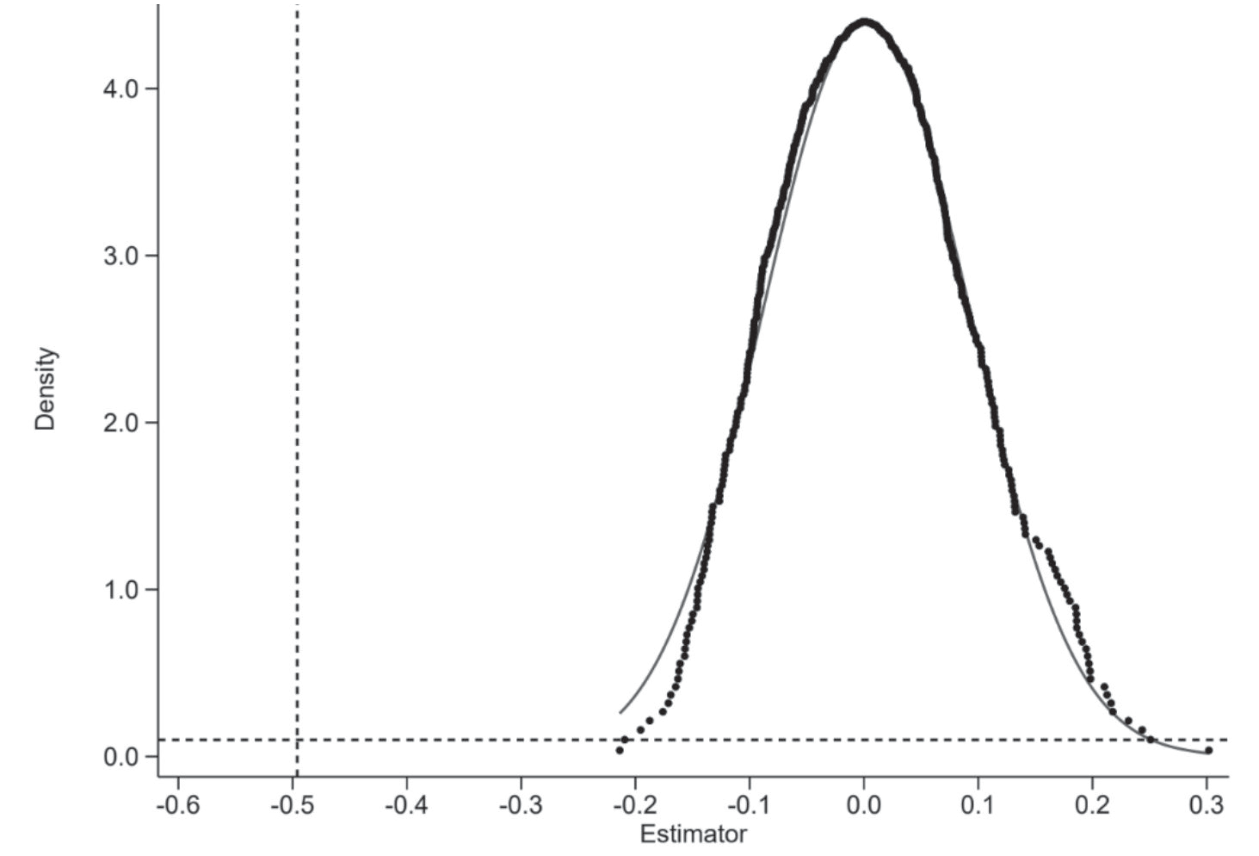
Table 3.
Results of robustness.
Other Robustness Tests
To further verify the robustness of the basic result, other robustness tests conducted by this study include: first, double-sided trimming of continuous variables, aiming to eliminate the interference of possible outliers, and the result shows that the coefficient of the explanatory variable is still significantly negative, indicating that the baseline result is credible; second, excluding city samples such as municipalities directly under the central government and provincial capital cities, in order to eliminate the interference of the differences between central cities and other cities in political and economic aspects on the baseline results, this study excludes central city sample data and then re-estimates using the model (1). The results show that after excluding central city samples, the interaction coefficient is still significantly negative, indicating that the estimation result of this paper is robust.
Further Analysis
Regional Heterogeneity
Due to the vast territory and different natural endowments of China, there are obvious discrepancies between regions in natural resources, production methods, and so on. It will lead to differences in economic models and industrial structures, causing different levels of pollution, which may cause different effects of environmental tax on industrial water pollution. To test this possibility, the study divides China into three parts: east, central, and west, and conducts empirical analysis by sub-region samples.
The regression results by sub-region samples show that Treati × Aftert coefficients of the central and western regions are both significantly negative, while the coefficient of the eastern region does not pass the significance test. These results demonstrate that the conclusion of baseline regression is more significant in the central and western regions. The reason for these results may be that, compared with the other two regions, enterprises in the eastern region paid more attention to environmental problems in their daily production, and the intensity of industrial water pollution in the eastern region is relatively stable. So, the sensitivity to environmental policy shocks is low. On the contrary, while the central and western regions are in the stage of accelerated economic development, the priority of regional economic growth is still greater than environmental protection. Some high-pollution industries in the eastern region are gradually transferred to the central-western regions, resulting in the accelerated “westward migration” of industrial pollution. Therefore, environmental tax has a stronger impact on industrial water pollution in the central and western regions.
Mechanism Test
Enforcement Rigidity
Local governments are the main carriers of environmental regulation and the guarantee of environmental protection. There are obvious differences in the legal system conditions among regions in China. In regions with poor legal systems, phenomena such as rent-seeking or collusion between the government and enterprises are more frequent. In results, the execution ability of regulations is relatively inefficient. Moreover, the enforcement of the pollution discharge fee itself is weak, resulting in a small restrictive effect on industrial pollution behavior. Conversely, the implementation of environment tax is supported by the tax law, and the enforcement rigidity is greatly improved compared with the former, which can more significantly restrict enterprise pollution behavior and inhibit industrial water pollution. In regions with strong legal systems, regulations are executed efficiently, which can offset the shortcomings of pollution discharge fees, so the space for environmental “fee-to-tax” to inhibit industrial water pollution is small. So, if the mechanism of enhancing enforcement rigidity is theoretically right, in regions with poor legal environment conditions, environmental tax should play a greater role in inhibiting industrial water pollution.
Table 4.
Regional heterogeneity.
This study uses the “Legal System Condition Index” as the proxy variable for legal system condition. Then, according to the median of this index, we set the dummy variable of Law. When the city’s legal condition is lower than the median, it takes a value of 1, otherwise it takes 0. We add Law and Treati × Aftert to the model (1) for the DDD test [46]. The results in columns (1) and (2) of Table 5 shows that the coefficient of Law × Treati × Aftert variable is significantly negative at least at the 5% level, which indicates that environmental tax reform can reduce industrial water pollution intensity by enhancing enforcement rigidity, and the mechanism of enhancing enforcement rigidity is verified.
Green Innovation
According to the Porter hypothesis, if the government strictly levies an appropriate environment tax, enterprises will have the motivation to improve green production technologies in order to obtain the “first-mover” advantage, which helps enterprises reduce the cost of environmental compliance and improve their competitiveness. For regions with high green innovation levels, the original innovation funds of enterprises have already occupied a high proportion of their production costs, and the marginal cost of expanding innovation capacity will be high, so whether environmental tax is levied or not, it has little impact on green innovation. In regions with low innovation levels, due to the disadvantages of the pollution discharge fee, the pollution cost of enterprises is far lower than their pollution control cost, resulting in a lack of motivation to carry out technological innovation. After the implementation of environmental tax, the tax rate has been raised significantly. Rational entrepreneurs will innovate energy-saving technology and pollution control technology to reduce pollutant emissions. Therefore, environmental protection tax should have a stronger effect on regions with low innovation levels.
This paper selects the number of green patents at the prefecture level as a proxy variable for green technological innovation to test the mechanism. According to the median of the variables, dummy variable Invest is set. When the regional green innovation number is lower than the median, Invest takes 1, otherwise it takes 0. This study adds Invest and Treati × Aftert to the model (1) for the DID method. The results in columns (3) and (4) of Table 5 show that Invest × Treati × Aftert coefficient is significantly negative, at least at the 10% level. This indicates that the mechanism of environmental tax inhibiting industrial water pollution by improving green technology innovation is verified.
Conclusions
Based on the theoretical analysis of the environmental tax on industrial water pollution, this study takes the implementation of the environmental tax as a quasi-natural experiment to construct the DID model. And using 274 city sample data from 2012 to 2020 in China to quantitatively analyze the causal relationship and mechanism of environmental tax on industrial water pollution. The main research results are as follows: First, the strict establishment of the “Environmental Tax Law” has a significant inhibitory effect on industrial water pollution. Specifically, the implementation of an environmental tax can curb 49.6% of industrial wastewater compared with the period of the discharge fee system. And after adopting a series of robustness tests, such as the placebo test and the PSM-DID, this conclusion still holds. Second, after further considering the regional heterogeneity of cities, it was found that environmental tax has a stronger inhibitory effect on industrial water pollution in central and western China. Third, this study explores the mechanism based on the perspectives of enforcement rigidity and the Porter hypothesis and finds that the inhibitory effect of environmental tax on industrial water pollution is achieved through mechanisms such as the enhancement of enforcement rigidity and the improvement of green innovation.
Policy Recommendations
According to the above research conclusion, this study puts forward the following policy recommendations: First, on the road of “cleaning up fee instead of environmental tax.” An environmental tax effectively solves the “incomplete implementation” of pollution discharge fee systems and significantly enhances the ecological protection awareness of industrial enterprises. The government should continue to improve the coordinated governance system between environmental protection departments and tax authorities, appropriately increase the environmental tax rate, expand the scope of taxes, and consider the inclusion of general pollution emissions and carbon dioxide emissions into the collection scope in the future. Second, to reduce the asymmetric effect of policy effect, local governments should adapt to local conditions, seek a balance point between economic growth and environmental protection goals, formulate targeted, differentiated environmental measures, strengthen policy incentives for industrial enterprises in central and western regions, and avoid their negative emergency behaviors, such as reducing production. Third, enterprises should increase their green innovation efforts, establish external environmental protection safeguards that are linked with environmental tax, enhance their initiative to obtain differentiated competitive advantages, and achieve green transformation.

