

Introduction
In recent years, the issue of global warming caused by carbon emissions has aroused widespread concern from all walks of life. From the signing of the Kyoto Protocol to the Paris Climate Conference, it has become a widespread consensus in the international community to work together to tackle global warming. China, as an important participant and practitioner in addressing climate change, has proposed a “double carbon” target at the UN Climate Ambition Summit 2020, including carbon peaking and carbon neutrality, and promoting the “double carbon” target will bring about a broad and profound economic and social change. This will bring about a broad and profound systemic change in the economy and society. As an internationally recognized market-based means of reducing emissions, the carbon tax is an important means of achieving the ‘double carbon’ target.
Currently, western countries such as Denmark and Finland have established a relatively comprehensive carbon tax system, which levies a carbon tax at a certain rate on the fossil energy consumed by enterprises in the production process [1]. Under the carbon tax policy, in order to reduce the cost of carbon tax, enterprises will try their best to reduce the carbon emissions generated by energy consumption and turn to low-carbon production. With the wide application of distributed low-carbon energy such as photovoltaic, more and more enterprises are using distributed energy equipment to provide energy for production activities. However, distributed energy equipment will be limited by the external natural environment and the constraints of the enterprise’s own energy demand response, and energy supply will appear idle and redundant within a certain time range [2]. Industrial cluster is the spatial aggregation of upstream and downstream enterprises in supply chain with production relations, which has the characteristics of large energy consumption and diverse energy use. The use of microgrid and other technical means in industrial clusters to realize the synergy and complementarity of distributed energy can improve the efficiency of energy utilization and reduce the carbon emissions of the industrial chain [3]. At present, some industrial park enterprises have realized the practical application of distributed energy sharing by establishing distributed energy systems such as rooftop photovoltaic. However, it is worth noting that distributed low-carbon energy is often costly, and the benefits under carbon tax policies are highly uncertain. If the actual benefits are lower than expected, it will trigger disappointment among decision-makers and cause disappointment aversion behavior, which will have a significant impact on the energy sharing decisions of industrial clusters. Therefore, it is of practical significance to explore the distributed energy sharing equilibrium strategy under the carbon tax policy, taking into account the disappointment aversion behavior of industrial cluster members.
In summary, this paper needs to address the following questions:
(1) Which industrial cluster distributed energy sharing decision-making model is the best under the carbon tax policy, and whether there is an equilibrium strategy?
(2) Under what conditions can cluster companies enter into cost-sharing contracts? Can cost-sharing contracts increase the level of energy sharing among cluster companies?
(3) What is the impact of member disappointment aversion behavior and carbon tax policy on the energy sharing equilibrium strategy of cluster enterprises?
The main contributions of this paper are as follows:
(1) We explore the distributed energy sharing decision and coordination mechanism in a dynamic framework. Based on optimal control theory, disappointment theory and differential game theory, we construct enterprise distributed energy sharing income models under different decision models, and analyze the optimal low carbon level of energy, optimal trajectory of energy sharing synergies and profits of enterprises.
(2) The research perspective of distributed energy sharing decision making is extended to the behavioral characteristics of decision makers. The influence of disappointment aversion behavior on energy sharing decision-making is investigated to enrich the literature on the impact of irrational behavior on distributed energy sharing decision making. (3) The external variable of carbon tax policy is incorporated into the consideration of distributed energy sharing decision-making. The impact of carbon tax rate changes on energy sharing decision-making is analyzed, enriching the research on distributed energy sharing decision-making under a low-carbon framework, which provides reference for enterprises and governments to make decisions.
The remainder of the paper is organized as follows. Section 2 is literature review. Section 3 describes the problem and presents the model assumptions. Section 4 constructs and solves the differential game model of energy sharing in industrial clusters under different decision models in a dynamic framework. Section 5 analyzes the equilibrium results of the model and discusses the impact of the member disappointment aversion and the carbon tax rate on the decision outcomes. Section 6 conducts numerical simulation analysis. Section 7 draws conclusions.
Literature Review
Although carbon tax policies have been widely implemented to reduce emissions, charging enterprises with carbon taxes while increasing their costs has been controversial in recent years [4]. Cao et al. conducted a multi-model comparison of China’s carbon tax policies to explore the conditions for achieving carbon neutrality goals with carbon tax rates [5]. Haoran et al. believe that the application of carbon tax and carbon emission reduction subsidy policies can reduce carbon emissions and improve environmental quality [6]. Hu et al. traded off carbon taxes with cap-and-trade based on a closed-loop supply chain model, and demonstrated that “cap-and-trade” is more appropriate for remanufacturing [7]. Sun et al. studied the carbon reduction decisions of two competing manufacturers based on carbon taxes and carbon trading in the context of consumer environmental awareness (CEA) and showed that cap-and-trade policies are more sensitive to CEA than carbon tax policies [8]. The relative efficiency of carbon taxes is higher than that of carbon trading, and the advantage increases over time [9]. Some scholars have also studied the impact of carbon taxes on supply chain operational decisions [10], examining the production decisions of cooperative supply chains [11], dual-channel supply chains [12], and hybrid supply chains [13] under carbon tax policies. Zhang et al. show that if the government appropriately increases the carbon tax and cut-off values in progressive carbon tax policies, manufacturers can be motivated to increase their emission reduction levels [14]. Zhang et al. constructed an evolutionary game model to analyze the joint effect of carbon taxes and innovation subsidies on the choice of green innovation models by producers and demonstrated that carbon taxes are more effective than innovation subsidies at later stages [15].
In the context of distributed energy sharing research, Lyaskovskaya et al. argue that the sharing economy has an important impact on sustainable development [16]. Petri et al. argue that decentralization of energy supply and demand can avoid transmission and distribution losses by consuming power near the source [17]. Liu et al. argue that energy sharing between neighboring PV producers is a more efficient way to increase economic efficiency than the independent operation of each distributed PV producer [18]. Xu et al. combine a location-allocation model for residential distributed PV installations with an energy sharing mechanism to increase the economic efficiency of PV producers while promoting the rational installation of residential PV [19]. Quddus et al. considered the uncertainty of electricity demand and used a two-stage stochastic programming model to optimize commercial buildings and electric vehicle charging stations [20]. Cui et al. developed a robust two-tier energy sharing model to provide producers and consumers and retailers with robust energy sharing plans to overcome market price and renewable energy uncertainties [21]. Liu et al. proposed a hybrid energy sharing framework for CHP and demand response in an integrated grid [22]. Recently, P2P energy sharing has become a hot topic of research. P2P energy sharing has the potential to promote local energy balance and self-sufficiency [23], allowing surplus energy from distributed energy sources to be traded between producers in community microgrids, which is more attractive than traditional point-to-grid (P2G) trading [24]. Chen et al. proposed an P2P energy sharing framework that considers both technical and sociological aspects based on prospect theory and stochastic game theory [25]. In terms of energy sharing research under low-carbon policies. Fu et al. established a differential game model of energy sharing in industrial clusters under cap-and-trade mechanism [26]. Xu et al. studied the value of energy supply contracts in a two-step supply chain consisting of one supplier and two financially asymmetrical producers [27]. Li et al. proposed a energy sharing mechanism between communities of distributed energy systems under a carbon tax policy and explored the impact of heterogeneous carbon liability on the economic and environmental benefits of shared communities [28].
A review of the existing literature shows that although there has been a large amount of research on energy sharing, most of the research has focused on the design of energy sharing mechanisms and scheduling optimization, without considering the impact of carbon tax policies on distributed energy sharing decisions in industrial clusters. Distributed energy is subject to fluctuations in carbon tax policies as well as natural conditions, supply and demand matching and other factors, and there is a large degree of uncertainty in the benefits. When making energy sharing decisions under such uncertainty, decision-makers are not entirely rational, may show different behavioral preferences. Therefore, obtaining the equilibrium strategy for distributed energy sharing in industrial clusters under the carbon tax policy, taking into account the behavioral preferences of decision makers, is the issue should be addressed in this paper. Most existing studies on decision makers' behavioral factors focus on fairness concerns of green supply chain [29] and closed-loop supply chain [30], loss aversion [31], risk aversion of sharing economy [32] and supply chain [33]. However, disappointment aversion, as a typical psychological behavior, also has an important impact on decision-making under uncertainty [34]. In addition, most of the research has focused on static decision making. But the distributed energy sharing is a long-term process based on cooperative emission reduction in industrial chains, and the synergy effect of energy sharing will also decay as time goes on and with technological progress, and is characterized by dynamic changes. Therefore, it is more meaningful to explore the distributed energy sharing decision and coordination mechanism of industrial clusters in a dynamic framework. Differential game is a dynamic model that can study the decision-making of two parties in continuous time. By constructing differential equation, it can better describe the process of energy sharing synergies changing with time, and provide support for solving the distributed energy sharing strategy problem of industrial clusters under dynamic conditions [35].
Based on this, this paper constructs a distributed energy sharing differential game model composed of a core enterprise and a supporting enterprise in the industrial cluster. Considering the synergistic effect of energy sharing, the dynamic decision-making problem of distributed energy sharing in industrial clusters is studied under the premise of income uncertainty. The study explores the impact of the degree of disappointment aversion and changes in carbon tax policy on the energy sharing decision and overall performance of industry clusters. On this basis, a cost-sharing contract is proposed to improve the overall performance of industry cluster members through Pareto, to coordinate the distributed energy sharing strategies of industry clusters.
Material and Methods
Description of the Problem
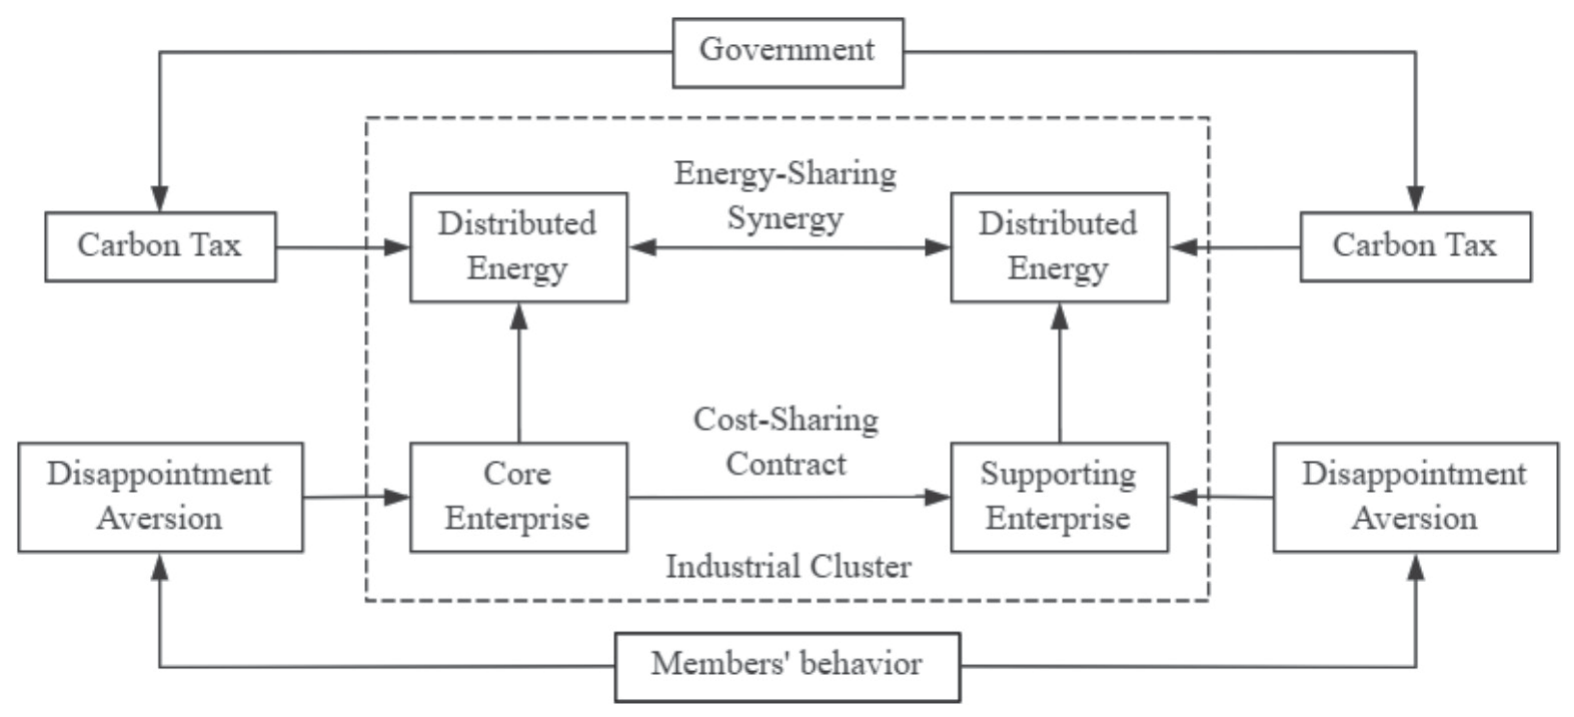
In the process of industrial cluster development, it will gradually form a network structure composed of core enterprises with resources and technical advantages and a number of supporting enterprises. Under the carbon tax policy, we focuses on the core and supporting enterprises in industrial clusters, and considers the members’ disappointment aversion characteristics, studies the differential game strategy of distributed energy sharing. Cluster enterprises achieve optimal utilization of energy and reduce carbon emissions through distributed energy sharing. This reduces energy costs and carbon tax costs and increases revenue. Under the Stackelberg game, in order to encourage supporting enterprises to share energy, core enterprises share some low-carbon energy costs to supporting enterprises through cost sharing contracts. As shown in Fig. 1.
Model Assumptions
Assumption 1: In distributed energy sharing, cluster enterprises decide their own low carbon level of energy. The energy low carbon level of the core enterprise is DX(t). The energy low carbon level of the supporting enterprise is DY(t). Referring to the assumptions of Xia et al. on low carbon costs [36], the cost of low carbon distributed energy at moment t is
Where ri is the low-carbon distributed energy cost coefficient of cluster enterprise i.
Assumption 2: The energy sharing synergy effect is the overall low-carbon level of distributed energy obtained by optimizing the allocation of distributed low carbon energy in the sharing process. Assume that at time t, the synergy effect generated by distributed energy sharing is K(t), which is positively correlated with the low carbon level of both parties’ energy. In the long time range, the energy sharing synergies decay with time. Referring to the assumptions of Wang et al. on knowledge sharing [37], the energy sharing synergy effect satisfies the following differential equation regarding time:
Where, K(0) = K0≥0; λi is the effect coefficient of low energy carbon level of industrial enterprises i on the energy sharing synergy effect, δ is the natural decay rate.
Assumption 3: Referring the portrayal of the benefits of sharing with Kong et al. [38], the total profits of industrial enterprises are
Where, S0(S0≥0) is the initial profits. β is the effect coefficient of energy sharing synergies on the initial revenue, let β∈[A, B] be a non-negative continuous random variable.
Fig. 1.
Distributed energy sharing decisions in industrial clusters considering members’ disappointment aversion under carbon tax policies.
Assumption 4: Under a carbon tax policy, a enterprise’s initial carbon emissions are Gi, and the government collects a carbon tax at a certain rate based on the enterprise's final carbon emissions TC. Then the cost of the carbon tax to both enterprises is
Where μi is the influence coefficient of energy sharing synergy effect on the carbon reduction emissions of cluster enterprise i.
Assumption 5: The profits generated by energy sharing in industrial clusters will be distributed to participating enterprises in a certain proportion. The proportion of the core enterprises is α, α∈(0,1), the proportion of the supporting enterprises is 1 – α. The proportion of profit distribution shall be determined by both parties through negotiation, and the profit function of both parties:
Assumption 6: In the energy sharing decision-making process in industrial clusters, both parties involved in energy sharing are characterized by disappointment aversion, with decision-makers comparing expected outcomes with internal reference outcomes and feeling pleasure when the expected outcome is greater than the reference outcome, and disappointment when the expected outcome is less than the reference outcome. This psychology can have an impact and, drawing on Bell et al.’s research on disappointment aversion [39], it can be described as
Where Πi is the total utility of energy sharing participant i under the expected profit πi(i = X, Y), πi0 is the inner reference profit of participant i, ui≥0 is the sensitivity of participant i to pleasure and vi≥0 is the sensitivity of participant i to disappointment.
The reference profit πi0 is equal to the random profit expectation E(πi), i.e:
Let β̄ = E(β) = ∫ABβg(β)dβ, satisfy πi (β̄) = πi0 . According to disappointment theory, the objective function for both parties when considering disappointment aversion is
Then the objective function for an energy sharing participant with disappointment aversion characteristics is
Where, ωi = ui – vi, when ωi>0, decision makers are more sensitive to disappointment brought about by negative deviations; conversely, they are more sensitive to pleasure brought about by positive deviations; when ωi = 0, it indicates that decision-makers are more rational. Existing research shows that decision-makers tend to be more sensitive to disappointment, so this paper assumes that the disappointment aversion coefficient ωi>0 and the value of ωi are positively related to the level of disappointment of decision-makers.
Assumption 7: Energy-sharing enterprises have the same discount factor at any point in time over an infinite time horizon ρ, and ρ>0.
For ease of writing, t is omitted below.
Results and Discussion
Centralized Decision-Making
Centralized decision making emphasizes the profit maximization of the decision maker as a whole, which is represented by the upper corner mark U. In this decision-making mode, cluster enterprises take the overall profit maximization as the goal, and cooperate to determine the level of low-carbon energy, so as to enhance the competitiveness of the industrial cluster as a whole. In this case, the objective function of the decision is:
(14)
Proposition 1: The optimal equilibrium strategy for enterprises under centralized decision-making is as follows:
The optimal low carbon level of energy are:
Of which
The optimal energy sharing synergy is:
Of which
The optimal value for the total profit of the system is:
Of which
Proof:
Under centralized decision-making, note that after moment t, the objective function of the long-term optimal utility value of both core enterprises and supporting enterprises in industrial clusters is: JSU = e–ρtVSU(K). According to optimal control theory, VSU(K) For all K≥0, the Hamilton-Jacobi-Bellman equation (HJB equation) must be satisfied:
(19)
Take the derivative of Equations (19). From the first derivative equal to 0, the optimal strategy of both sides can be obtained:
Substituting Equations (20) (21) into Equation (22) gives
By analyzing the order characteristics of Equation (22), it can be seen that the analytic formula of the optimal value function with respect to K has the following form: VSU(K) = s1K + s2, where s1 and s2 are constants, substituting Equation (22) and sorting it out can be obtained:
(24)
Substituting Equation (23) into Equation (20) Equation (21) to obtain Equation (15) Equation (16); then substituting Equation (15) Equation (16) into Equation (3) to obtain the Equation (17); finally substituting Equation (23) Equation (24) into VSU(K) = s1K + s2, and then substituting the result into JSU = e–ρtVSU(K), the total system profit can be further found as in Equation (18).
Proof complete.
Decentralized Decision-Making
Decentralized decision making emphasizes the maximization of the respective interests of the decision-makers, which is represented by the superscript L. At this time, the cluster enterprises have equal status and can determine their low-carbon level of energy by themselves. The decision objective function is:
Proposition 2: The optimal equilibrium strategy for enterprises under decentralized decision-making is as follows:
The optimal low carbon level of energy are:
Of which
The optimal energy sharing synergy is:
Of which
The optimal value for the profits of core enterprise, supporting enterprise and total profit of the system are:
Of which
Proof:
Under decentralized decision-making, note that after moment t, the objective function of the long-term optimal utility value of core enterprises and supporting enterprises in industrial clusters are: JXL = e–ρtVXL(K), JYL = e–ρtVYL(K). According to optimal control theory, VXL(K) and VXL(K) for all K≥0, the Hamilton-Jacobi-Bellman equation (HJB equation) must be satisfied:
Solving Equations (33) and (34) for the first order derivatives with respect to DX and DY and letting them be zero, we obtain
Substituting Equations (35) and (36) into Equations (33) and (34), we obtain
By analyzing the order characteristics of Equation (37) and (38), it can be seen that the analytic formula of the optimal value function with respect to K has the following form: VXL(K) = m1K + m2, VYL(K) = n1K + n2, where m1, m2, n1, n2 are constants, substituting Equation (33) (34) and sorting it out can be obtained:
(42)
Substituting Equations (40) and (41) into Equations (35) and (36), can obtain Equations (27) (28); the results are then brought into Equation (3) to obtain Equation (29); finally, substituting Equations (39) (40) (41) (42) into VXL(K) = m1K + m2, VYL(K) = n1K + n2, then substituting the result VXL(K) and VYL(K) into JXL = e–ρtVXL(K) and JYL = e–ρtVYL(K) to obtain the profit of each party and the total profit of the system, as in Equations (30) (31) (32).
Proof complete.
Stackelberg Game with the Introduction of Cost-Sharing Contracts
It can be seen from Proposition 2 that the optimal equilibrium strategies under decentralized decision-making are all lower than those under centralized decision-making, indicating the existence of double marginal effect. Based on this, this paper introduces cost sharing contract. Assume that in the Stackelberg master-slave game, the core enterprise is the leader of energy sharing and the supporting enterprise is the follower. Under this assumption, the core enterprise first decides low carbon level of energy and cost sharing ratio φ(0≤φ≤1), and the supporting enterprise makes the following decision according to its own will after obtaining the decision information of the core enterprise. In this case, the core enterprise can effectively anticipate the following decision of the supporting enterprise before making the decision.The Stackelberg game is represented by the upper corner marker R. According to the inverse induction method, the decision objective functions are:
Proposition 3: The optimal equilibrium strategy for enterprises under the Stackelberg game scenario is as follows:
The optimal low carbon level of energy and cost sharing ratio are:
(47)
Of which
The optimal energy sharing synergy is:
Of which
The optimal value for the profits of core enterprise, supporting enterprise and total profit of the system are:
Of which
Proof:
Using the inverse induction method for analytical solution, the problem is first transformed into a unilateral optimal control problem for the supporting enterprise. The optimal value function of the long-term utility of the supporting enterprise after moment t is written as: JYR = e–ρtVYR(K), according to the optimal control theory, VYR(K) for all K≥0, the Hamilton-Jacobi-Bellman equation ( HJB equation) needs to be satisfied:
(52)
Solving Equations (52) for the first order derivatives with respect to DY and letting them be zero, we obtain
The core firm chooses its optimal strategy based on the optimal response function of the supporting firms to satisfy its own utility maximization objective. Similarly, the optimal value of the long-term utility function of the core firm after t hours is JXR = e–ρtVXR(K). According to the optimal control theory, VXR(K) for all K≥0, the Hamilton-Jacobi-Bellman equation (HJB equation) needs to be satisfied:
Substituting Equation (53) into Equation (54) and solving Equations (54) for the first order derivatives with respect to DX and φ and letting them be zero, we obtain
Substituting Equations (53), (55) and (56) into Equations (52) and (54), it can be seen that the analytic formula of the optimal value function with respect to K has the following form: VXR(K) = p1K + p2, VYR(K) = q1K + q2, where p1 , p2 , q1 , q2 are constants, leads to
(60)
Substituting Equations (57) and (59) into Equations (53), (55) and (56), we can find the equilibrium strategies (DX, DY ) and the proportion of costs shared φ, as in Equations (45) (46) (47); then bringing the results into Equation (3), we get the energy sharing synergy effect as Equation (48); finally, Equations (57) (58) (59) (60) are taken into VXR(K) = p1K + p2 and VYR(K) = q1K + q2, and take the results of VXR(K), VYR(K) into JXR = e–ρtVXR(K) and JYR = e–ρtVYR(K) to obtain the profit of each party and the total profit of the system in Equation (49) (50) (51).
Proof complete.
Result Comparison
Corollary 1: Optimal low-carbon levels of energy for both sides of energy sharing under three decision scenarios: DXU>DXL = DXR, DYU>DYR>DYL; energy sharing synergy: KU>KR>KL; the profits of core enterprise, supporting enterprise and total profit of the system: JXR>JXL, JYR>JYL, JSU>JSR>JSL.
Corollary 1 shows that compared to decentralized decision-making and the Stackelberg game, centralized decision-making is the optimal decision-making model. It increases the total system profit and the energy sharing synergy, and improves the incentive of energy sharing of enterprises. However, in order to make centralized decisions on cluster enterprise resources, negotiations between enterprises are also necessary. The introduction of a Stackelberg game with cost-sharing contracts can create incentives for both parties to coordinate decentralized decision-making and increase energy-sharing synergies and total system profits.
The proof is omitted and can be obtained by observing Equation (15)-(18), Equation (27)-(32), Equation (45)-(51).
Corollary 2: Under the carbon tax policy, the low-carbon energy level of core enterprises and supporting enterprises and the synergy effect of energy sharing will increase with the increase of carbon tax rate. When the initial emission is less than a certain limit value, the profits of both parties and the total profits of the system also increase with the increase of the carbon tax rate. However, when the initial emission is greater than this limit value, with the increase of the carbon tax rate, the profits of both parties and the total profits of the system will first decrease and then increase. The value of this limit is negatively correlated with the disappointment aversion coefficient.
Corollary 2 suggests that under certain conditions, an increase in carbon tax rates can significantly improve the low-carbon energy level of enterprises, promote their participation in distributed energy sharing, and increase profits. This has a positive effect on reducing the carbon emissions of industrial clusters. However, when initial emissions are large, an increase in the carbon tax rate will have a dampening effect on energy sharing at a certain stage, which can be moderated by adjusting the psychology of disappointment aversion.
Proof:
As an example of a centralized decision, according to Equations (15), (16) and (17) on the first-order conditions of TC
It can be seen that the low carbon level of both energy sources and the energy sharing synergy increase with the increase in the carbon tax rate TC.
Based on the total system profit function in Equation (18), Solving for the first order and second order derivatives of the carbon tax rate TC as:
And
From
Since the carbon tax rate TC≥0, the initial carbon emissions when TC* >0, i.e:
When
As the carbon tax rate TC increases, the total system profit decreases and then increases.
When TC* ≤0 , i.e. initial carbon emissions:
The total system profit increases with the carbon tax rate TC.
As can be seen from
Proof complete.
Corollary 3: The optimal low-carbon level of energy, the optimal energy sharing synergies, the optimal total system profits are inversely proportional to the degree of disappointment aversion in all three decision scenarios. And there exists a threshold ω̅ i for core and supporting enterprises to participate in energy sharing in an industry cluster when and only when ωi<ω̅ i and the threshold ω̅ i is proportional to the carbon tax rate TC.
Corollary 3 shows that the degree of disappointment aversion of industry cluster members has a significant impact on their energy sharing decisions, and that disappointment aversion has a disincentive effect on the motivation to share energy; the more disappointed and avoidant a member is, the less willing he or she is to participate in energy sharing. Both parties will choose to cooperate in energy sharing if, and only if, their disappointment aversion coefficient does not exceed a certain threshold. This limit increases as the carbon tax rate increases, suggesting that a higher carbon tax rate can increase the limit of disappointment aversion behavior of both parties, which is conducive to the realization of energy sharing cooperation in industrial clusters.
Proof:
Taking decentralized decision-making as an example, according to Equations (27) and (28), it can be seen that in order to realize distributed energy sharing of industrial clusters, the energy low-carbon level of both parties needs to be satisfied to be greater than zero, i.e:
Then the disappointment aversion coefficient can be obtained which needs to be less than a certain limit ωi<ω̅ i, where
By its first order condition on TC:
It can be seen that the limit value of the disappointment aversion coefficient for both sides is proportional to the carbon tax rate.
Proof complete.
Corollary 4: In the Stackelberg game with the introduction of cost-sharing contracts, when the profit distribution ratio meets the following conditions:
Core enterprises bear part of the low-carbon energy costs for supporting enterprises. The cost sharing ratio φ is positively proportional to the proportion of revenue obtained by core enterprises α and the disappointment aversion coefficient of supporting enterprises ωY, and inversely proportional to the proportion of revenue obtained by supporting enterprises 1 – α and the disappointment aversion coefficient of core enterprises ωX.
Corollary 4 shows that in the case of Stackelberg game, in order for core enterprises to reach cost sharing contracts with supporting enterprises, certain conditions must be met. Only when the income distribution ratio is within a certain range, can the contract be reached. This range is directly influenced by the disappointment aversion coefficient of both parties. The amount of cost sharing is related to income distribution rate and disappointment aversion coefficient. When the profit ratio of the core enterprise is within a certain range, the higher the income of the core enterprise or the weaker the aversion to disappointment, the core enterprise will increase its cost sharing rate. When the income distribution of supporting enterprises is less or they are more sensitive to disappointment aversion, core enterprises will also increase their cost sharing rate.
The proof is omitted and can be obtained by observing Equation (47).
Numerical Simulation Analysis
In order to illustrate the impact of enterprises’ disappointment aversion behavior on energy sharing decisions in industrial clusters under carbon tax policies and to observe the decision results under different models more intuitively, numerical simulations are carried out in this paper by MATLAB software. Based on the assumptions on the relevant parameters and research of Wang et al. [40], the parameters were assigned the following values: rX = 15, rY = 12, ωX = 0.1, ωY = 0.1, λX = 0.6, λY = 0.3, μX = 0.8, μY = 0.6, αX = 0.6, δ = 0.1, ρ = 0.8, t = 1, GX = 20, GY = 10, S0 = 20, TC = 1, β serving the uniform distribution of U~(0,40). The above parameters were brought into the above model to obtain the simulation results as shown in Table 1.
Table 1.
Equilibrium results of the game.
| Projects | Centralized | Decentralized | Stackelberg game |
|---|---|---|---|
| DX | 0.9067 | 0.5422 | 0.5422 |
| DY | 0.5667 | 0.2278 | 0.4528 |
| K | 3.9318 | 2.1678 | 2.5359 |
| φ | - | - | 0.5159 |
| JX | - | 23.3000 | 28.7183 |
| JY | - | 21.3454 | 25.1164 |
| JS | 86.7356 | 44.6455 | 53.8348 |
Table 1 shows that compared to the centralized decision, the low carbon level of energy and profits from core enterprise and supporting enterprise have decreased under decentralized decision-making, and the energy sharing synergies and total system profits have also decreased. It shows that decentralized decision-making limits the enthusiasm of distributed energy sharing in industrial clusters. After the introduction of the cost-sharing contract, the low carbon level of energy, the energy sharing synergy, the profit of enterprises and the total profit of the system have increased, which is closer to the centralized decision, indicating that cost-sharing contracts can effectively coordinate the decentralized decision.
Fig. 2 shows the curve of energy sharing synergy effect of three decision model over time. Fig. 3 shows the variation of the total profit of the system over time. It can be seen from the figure that the energy sharing synergy and the total profit of the system gradually increase as time goes on and eventually stabilize. Energy sharing synergy and total system profits also increase in decentralized decision-making, but the increase is small, and the increase is the largest under centralized decision-making. Stackelberg game is superior to distributed decision making, which shows that the cost-sharing contract between the core firm and the supporting firm can effectively improve the equilibrium result under distributed decision making. This is consistent with the conclusion of Corollary 1.
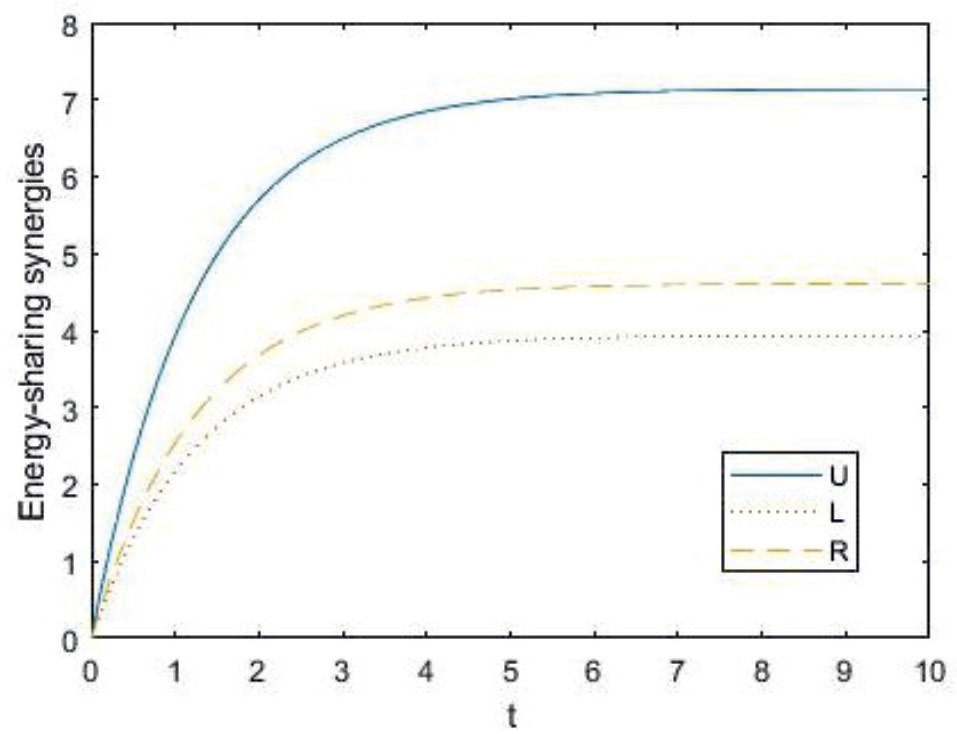
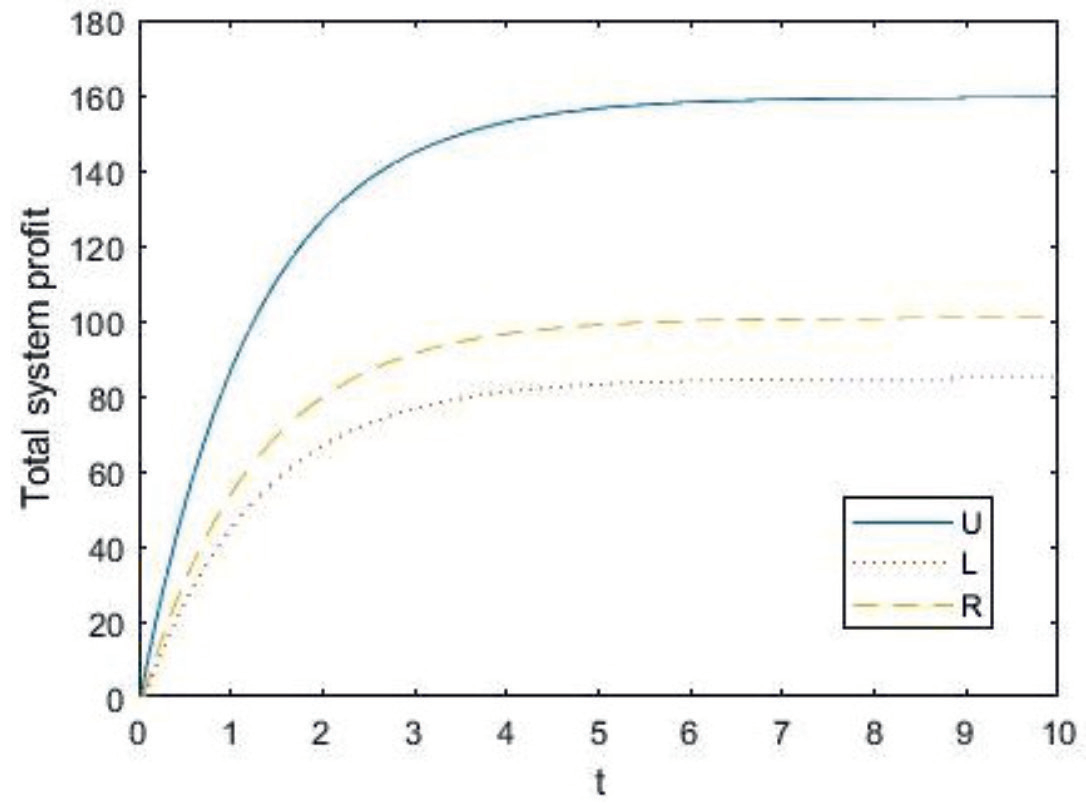
Fig. 4 depicts the synergistic effect of energy sharing under centralized decision-making as a function of carbon tax rates. Fig. 5 depicts the variation of the total profit of the system with the carbon tax rate. As shown in Fig. 4, the energy sharing synergy of industry clusters increases with the carbon tax rate at any time horizon. This indicates that a higher carbon tax rate can increase the enthusiasm for energy sharing in industry clusters, which in turn increases the energy sharing synergy effect. Fig. 5 shows that when the initial carbon emissions of enterprises are low, the total profit increases with the increase of the carbon tax rate, and when the initial emissions of enterprises are higher than a certain limit, the total profit of the system decreases and then increases with the increase of the carbon tax rate. This indicates that when an enterprise’s initial carbon emissions are low, increasing the carbon tax rate can increase the enterprise’s profit and promote energy sharing, while when the enterprise’s initial carbon emissions are high, increasing the carbon tax rate may reduce the enterprise’s profit at a certain stage, and enterprises should choose appropriate distributed energy sharing strategies according to their initial carbon emission levels and changes in carbon tax rates. This is consistent with the conclusion of Corollary 2.
Fig. 6 depicts the variation of total system profit with the two-party disappointment aversion coefficient under centralized decision-making. The figure shows that the degree of disappointment aversion by both parties is negatively related to total system profit, i.e. the greater the degree of disappointment aversion, the lower the total system profit. This indicates that the disappointment aversion behavior of enterprise is not conducive to energy sharing motivation and profitability, and plays a negative role in energy sharing decision making behavior, and enterprises should appropriately adjust their disappointment aversion psychology. This is consistent with the findings of Corollary 3.
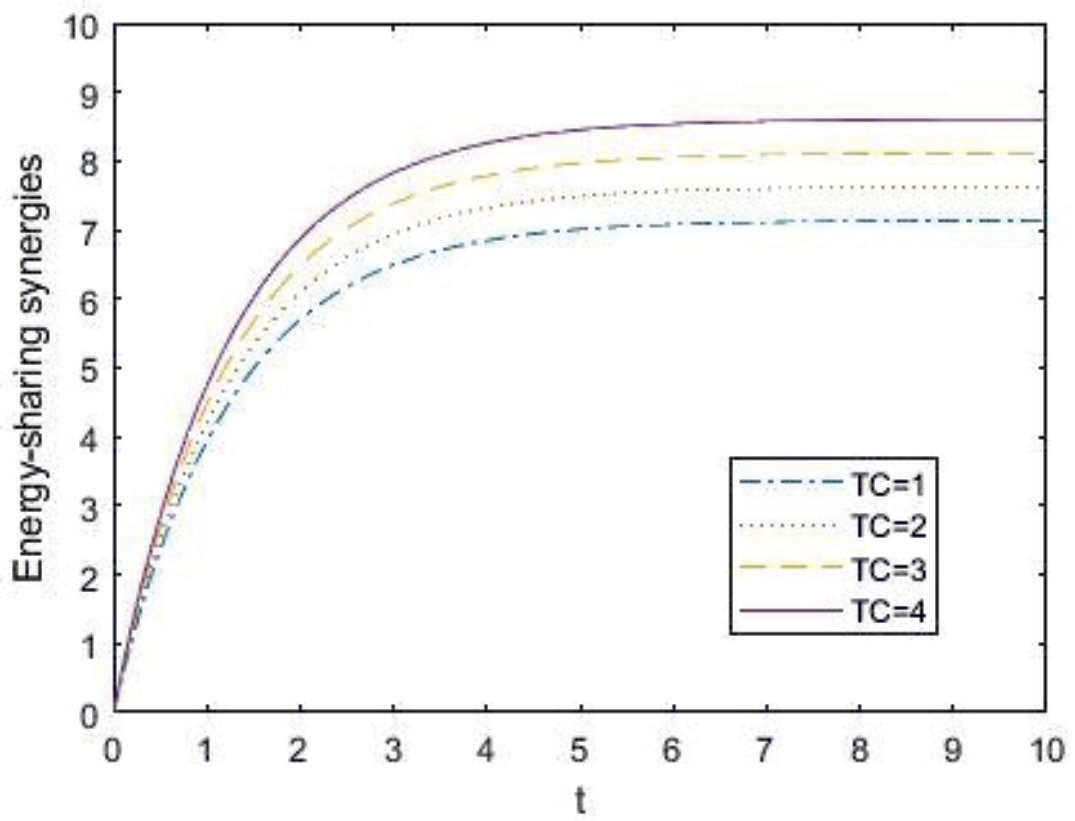
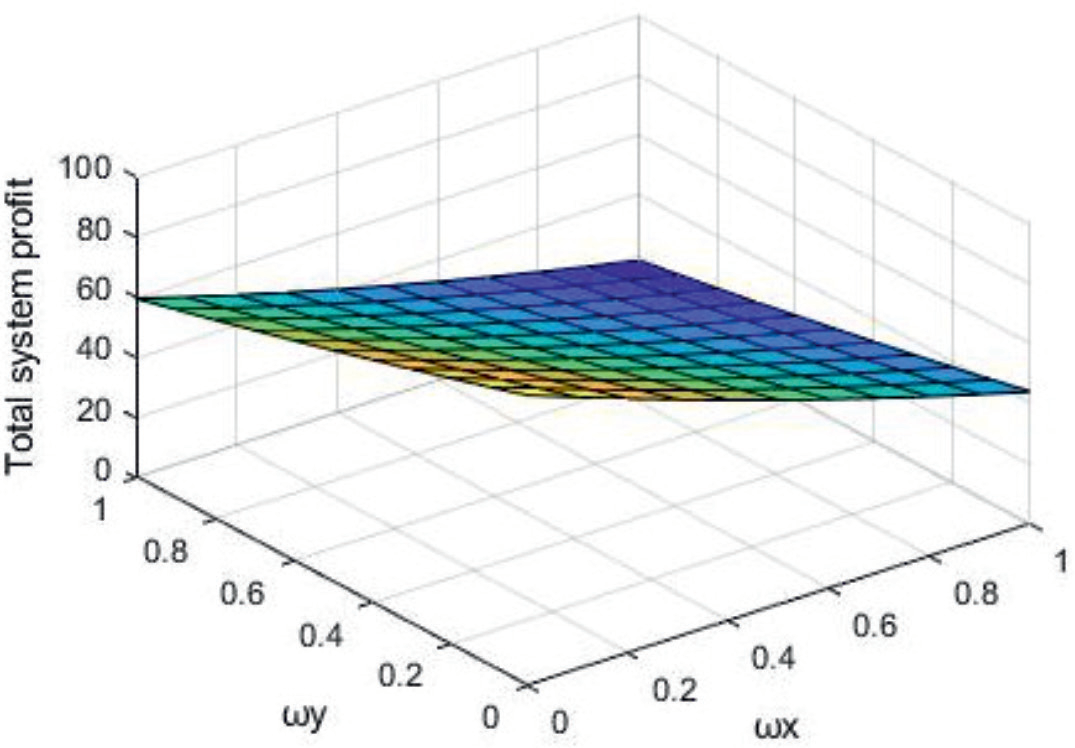
Fig. 5.
Effect of the carbon tax rate and enterprise's initial carbon emissions on total system profit.
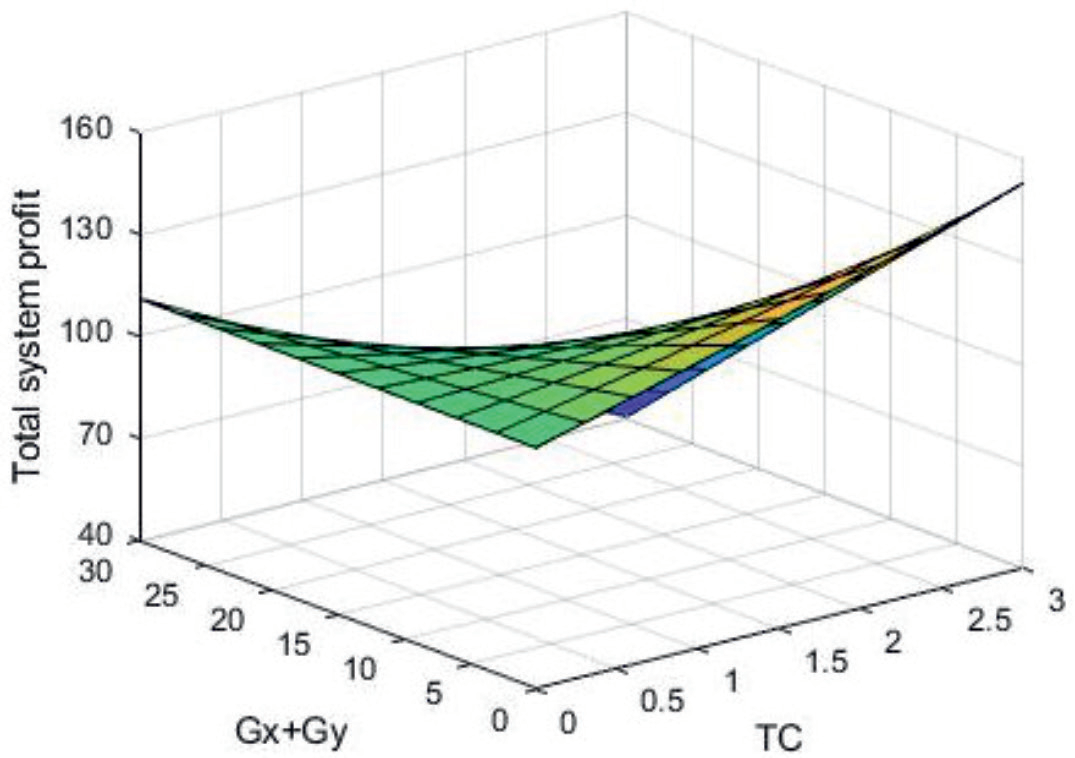
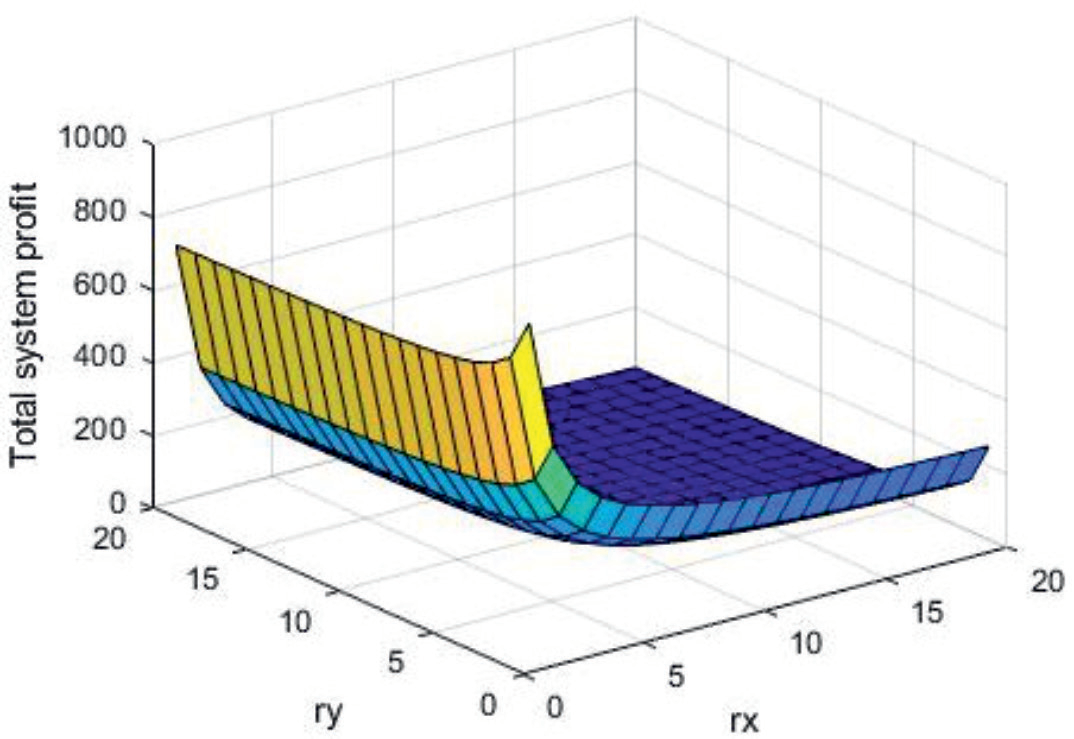
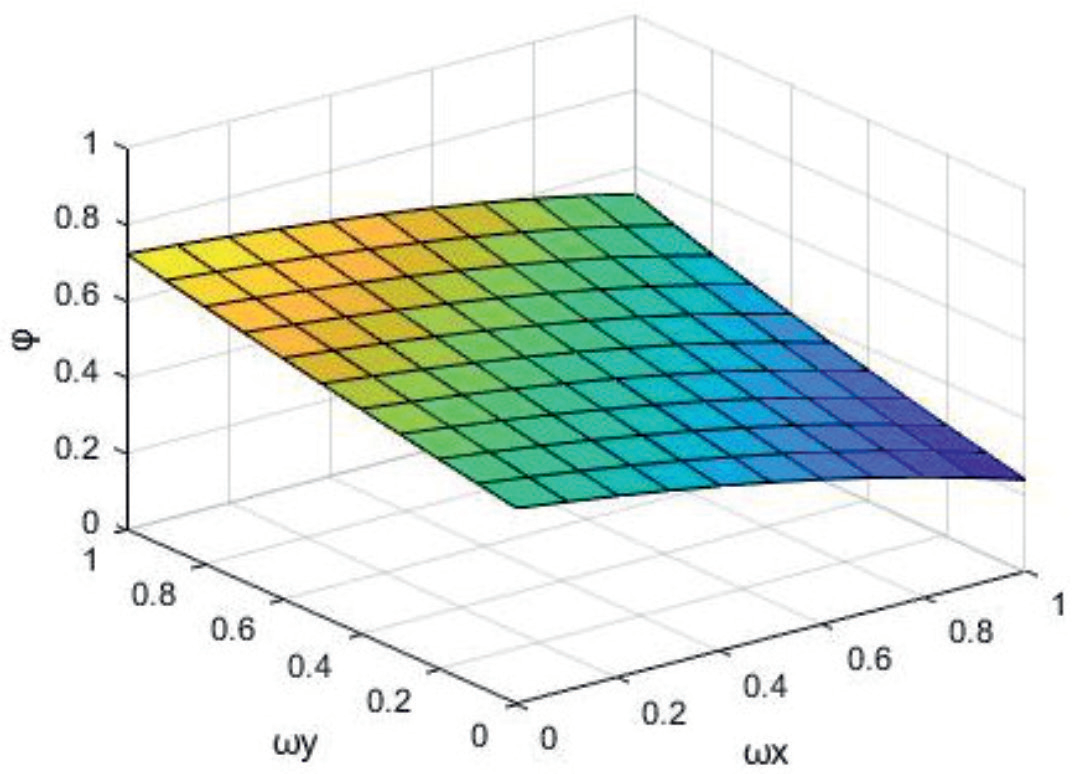
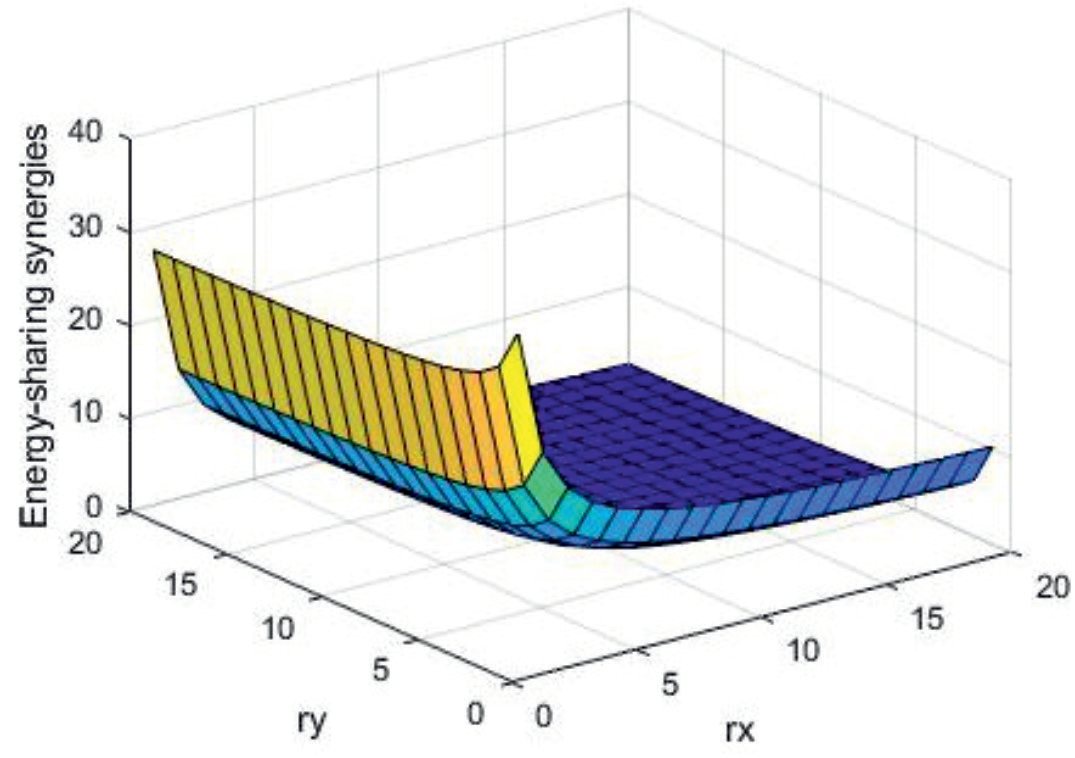
Fig. 7 depicts the variation of the cost sharing ratio with the disappointment aversion coefficient in the Stackelberg game scenario. The figure shows that cost sharing ratio decreases as the core enterprise’s disappointment aversion coefficient increases and increases as the supporting enterprise’s disappointment aversion coefficient increases. This indicates that when faced with uncertainty about the benefits of energy sharing, the less fearful of disappointment core enterprises are the more willing they are to share the low-carbon costs of energy from supporting enterprises and incentivize them to share energy, and the higher the disappointment level of supporting enterprises, the higher the proportion of core enterprises sharing costs for them. This is consistent with the findings of Corollary 4.
Fig. 8 and Fig. 9 depict the variation of energy sharing synergy and total system profit with the cost coefficients of both parties in the Stackelberg game scenario, respectively. It can be seen from the figures that with the increase in the cost coefficient of both parties, energy sharing synergy is decreasing, and the total profit of the system is also decreasing. This indicates that the energy low carbon cost coefficient has a suppressive effect on energy sharing in industrial clusters. Cluster enterprises should reduce energy low-carbon costs from various aspects, such as rational allocation of energy storage resources, the establishment of integrated energy service systems and cooperation with professional energy service providers.
Conclusion
This paper takes the core enterprises and supporting enterprises participating in distributed energy sharing in industrial clusters as the research object, and studies the dynamic coordination of energy sharing in industrial clusters considering carbon tax policy and members’ disappointment aversion behavior. We apply differential game theory and take energy sharing synergy as the state variable to construct differential game models under centralized decision making and decentralized decision making, and introduce cost sharing contract for coordination. Then, we discuss the optimal equilibrium strategies of both firms, energy sharing synergies, profits of both firms and total system profits under the three decision scenarios, and analysis the equilibrium results. We explore the effects of the carbon tax rate and the degree of member disappointment aversion on the energy sharing decision of the industry cluster. Finally, we analyze and validate the impact of dynamic equilibrium strategies of both parties and related parameters on the decision through numerical simulation. The main conclusions are as follows:
(1) Under centralized decision-making, the optimal energy low-carbon level, energy sharing synergies and total system profits of the core enterprises and supporting enterprises of industrial clusters are the highest, and the equilibrium results under Stackelberg game are higher than those under decentralized decision-making. It shows that centralized decision making is the optimal decision mode, and it reaches Pareto optimization. However, if the centralized decision is to be implemented voluntarily by the energy-sharing parties, there is a need for joint negotiation and other means. The Stackelberg game with the introduction of cost-sharing contracts improves the decentralized decision-making results by providing an incentive for the core enterprise to bear part of the low carbon cost of energy for the supporting enterprise.
(2) Under the carbon tax policy, with the increase of the carbon tax rate, the low carbon level of energy of core enterprises and supporting enterprises and the energy sharing synergy effect have been improved. This shows that increasing the carbon tax rate is conducive to improving the low-carbon energy level of enterprises and the synergy effect of energy sharing. However, when the initial carbon emissions of enterprises are above a certain limit, raising the carbon tax rate within a certain range will reduce the profits of both parties and the total profits of the system, which will have a dampening effect on the energy sharing of the industry cluster, and this limit is negatively related to the disappointment aversion coefficient. This suggests that the government should set a reasonable carbon tax rate considering the initial carbon emissions of enterprises, and enterprises should also adjust their disappointment aversion mentality according to the changes in the carbon tax rate.
(3) The degree of frustration aversion of industry cluster members has an important influence on their energy sharing decisions, and both parties will choose to cooperate in energy sharing if and only if their frustration aversion coefficients do not exceed a certain limit. This limit increases as the carbon tax rate increases, suggesting that a higher carbon tax rate can raise the limit of disappointment aversion for both parties, which is conducive to the realization of energy sharing cooperation in industrial clusters. The optimal low-carbon level of energy, the energy sharing synergy effect, the profit of both parties are all inversely proportional to the degree of disappointment and aversion, and the higher the level of disappointment aversion, the lower the willingness to participate in energy sharing.
(4) In the Stackelberg master-slave game, the cost-sharing ratio is related to the benefit-sharing ratio and disappointment aversion coefficient between the two parties. When the core enterprise obtains the proportion of benefits within a certain range, the core enterprise’s cost-sharing proportion to the supporting enterprise will increase as the disappointment aversion psychology decreases or the proportion of benefits to the core enterprise increases. The core enterprises will also increase their cost-sharing ratio when the supporting enterprises’ benefit is less or their disappointment aversion is stronger. This indicates that the greater the proportion of benefits for core enterprises, the weaker the disappointment-aversion psychology, and the more obvious the improvement of cost sharing contract, the more active industrial cluster distributed energy sharing.
This paper analyzes the distributed energy sharing decision of industry clusters from a dynamic perspective under carbon tax policies, taking into account the disappointing aversion behavior of cluster members in the face of uncertainty. However, this paper does not include the government as a decision maker on the carbon tax rate, which could be further explored in the future. At the same time, in a market environment where there are low-carbon preferences of consumers, it is also important to investigate the influence of other behavioral factors on the distributed energy sharing decisions of industrial clusters.

