

Introduction
Climate change is exerting a pervasive influence on every nation, characterized by the escalating frequency of extreme meteorological events. The economic losses attributed to these disasters amount to 1.5% of China’s GDP and 0.7% of global GDP, quantifiably highlighting the imperative for urgent climate policy responses. To address this challenge, nations embraced the Paris Agreement in 2016, committing to limiting global temperature rise to within 2ºC. As natural ecosystems and biodiversity face severe threats, the United Nations Environment Program (UNEP) is leading efforts to protect biodiversity, restore damaged ecosystems, and ensure the sustainable utilization of natural resources. The 2021 report Making Peace with Nature calls for countries to improve environmental governance, redirect financial flows toward ecosystem restoration projects, and incorporate natural capital into the evaluation framework of economic performance and decision-making processes. These efforts align closely with the 2030 Sustainable Development Agenda, which underscores global cooperation in tackling climate change (SDG 13), protecting terrestrial and marine ecosystems (SDG 14 and SDG 15), and promoting sustainable consumption and production patterns (SDG 12).
China faces unprecedented pressure in green governance and has set ambitious targets to peak carbon emissions by 2030 and achieve carbon neutrality by 2060 ‒ a vision encapsulated in the “dual carbon” goals. Against this backdrop, China’s departure audit on natural resource assets has emerged as a new environmental regulatory tool. A departure audit is a comprehensive review of the performance of government officials during their term of office. This tool aims to evaluate and supervise how leading cadres manage and use natural resources during their tenure, as well as the impact of their actions on the environment. This audit not only pertains to the personal responsibility of leaders but also is significant in constructing a national ecological civilization and global green development. Following the rollout of the "dual carbon" goals, China has imposed new requirements for building up a green and low-carbon society. The 14th Five-Year Plan emphasizes that to actively respond to climate change and achieve these goals, the country must implement a system that prioritizes carbon intensity control while integrating total carbon emissions control. It also urges better alignment between the dual control policy on energy consumption and the dual carbon targets, gradually shifting from mere energy consumption control to a dual control system for carbon emissions. The realization of the dual carbon goals lies in balancing carbon sinks and carbon sources [1]. Increasing carbon sinks depends mainly on ecological protection and restoration, while controlling carbon sources hinges on the research, development, and application of green technologies, as well as corporate structural adjustments to boost green transformation and upgrading. Moreover, reaching the dual carbon goals entails not only the demand for advanced low-carbon and zero-carbon energy technologies but also the pressure to formulate and implement supportive macroeconomic policies [2]. As a pivotal strategic decision made by the Central Committee of the Communist Party of China, the dual carbon goals rely heavily on the government officials’ leadership, which is essential for the effective implementation and vigorous enforcement of policies. By studying the role of government officials in achieving carbon balance, we can broaden the perspective of government auditing research and provide new insights into the external governance function of such audits globally, ultimately aiding in advancing global sustainable development.
Since the 18th CPC National Congress, targeted policy documents have been issued to reform the assessment of officials’ performance, aiming to shift away from the growth-at-all-costs mindset and reinforce government accountability for environmental protection and governance. In China, the 18th Central Committee Third Plenary Session explicitly stated: “Explore the compilation of natural resource asset balance sheets and implement natural resource asset departure audits of leading cadres”. In 2015, 162 cities nationwide initiated pilot programs for these audits. In 2017, the CPC General Office, along with the State Council General Office, jointly issued the Regulations on Natural Resource Assets Departure Audit of Leading Cadres (Trial) (hereinafter referred to as the Audit Regulations), standing for the formal establishment of this routine audit system, which was fully rolled out in 2018.
Subsequently, the highly feasible implementation of the departure audit system has piqued the interest and commandeered the attention of the academic community, leading scholars to explore whether this system can effectively ensure that leading cadres always scrupulously abide by the responsibilities for natural resource assets and environmental protection, thus backing up the enhancement and promotion of environmental management. This process reflects not only the importance we attach to nature conservation but also our strong commitment to green development goals. We are moving towards a more just and effective environmental governance system by strengthening policymaking, promoting rational use of resources, and encouraging public participation. Existing studies have primarily focused on two aspects: direct environmental governance effects [3], the reduction of pollution levels due to this audit implementation [4], and indirect environmental governance effects, where this audit system promotes regional environmental governance by fostering local green innovation [5-9]. However, current research on the environmental governance effects of the departure audit system remains insufficient, and the mechanisms by which this system ensures that leading cadres better fulfill their environmental protection responsibilities are still poorly understood.
In the current ecological situation, this study examines the environmental governance capacity and mechanisms of the departure audit system from the perspective of carbon balance, using the nationwide pilot program from 2010 to 2020 as a quasi-natural experiment. Quasi-natural experiments attempt to simulate the real world, for example, control variables, to ensure that the results are consistent with those of the natural environment. Experiments, providing a solid empirical foundation, allow researchers to evaluate more precisely the effects of a particular phenomenon or pattern of behaviors in different environments. Meanwhile, a distinctive difference-in-differences (DID) model with multiple periods is constructed for this analysis. Accordingly, marginal study contributions are made. Firstly, it addresses the limitation of a single perspective in research concerning the environmental governance effects of the natural resource assets departure audit system. Previous studies have often predominantly focused on the inevitable impact of these audits solely from the standpoint of carbon emissions or have concentrated on empirical research related to enterprises, the economy, and government, or they have analyzed the effects of these audits from a purely normative standpoint. Instead, this study perceives from a unique angle by considering both the impact of these audits on carbon emissions and carbon sinks, thereby diversifying the research perspective on the natural resource assets departure audit. Secondly, this study unveils a new dimension of empirical data, which paves the way for a more comprehensive analysis. By clarifying the logical relationship between these audits and carbon balance, it delves into how the audits influence carbon balance through the dual pathways of industrial structure optimization and green innovation, uncovering the internal mechanisms at play and validating the role of the audit pilot in enhancing government-led carbon balance efforts. Thirdly, this study selects carbon balance as the explained variable, as it provides a more comprehensive reflection of the net environmental impact of human activities. The carbon balance metric effectively integrates both emission and absorption dimensions, offering a holistic assessment of policy effectiveness. This approach overcomes the limitations of using carbon emission indicators alone, which tend to be partial and one-sided.
Literature Review
Environmental Governance Effects of Natural Resource Assets Departure Audit of Leading Cadres
Since implementing the departure audit in China, academic attention has focused on both regional and enterprise levels. At the regional level, research primarily explores whether the audits improve regional environmental quality [10-13]. For instance, Xiong et al. [14] found that the departure audit can significantly reduce carbon emissions, thus improving environmental conditions. Besides, Chen et al. [5] suggested that the audit system does not directly enhance air and water quality but exerts a long-term effect on environmental governance through significant increases in regional green innovation, encompassing all aspects of production processes, social structure, and supply chain management. Li and Li [15] argued that the departure audit could significantly improve environmental governance efficiency by promoting environmental institution-building [16-20], strengthening regulatory capabilities, and increasing investment in environmental governance. On the enterprise level, Sun et al. [21], using a DID model, examined the outcomes of corporate environmental responsibility and found that audits effectively promote corporate environmental responsibility, especially in non-state-owned enterprises and those not previously recognized for environmental excellence. Zhang and Wu [22] discovered that audits significantly enhance corporate environmental protection responsibility. Regarding spillover effects [23-25], existing studies have focused on the non-environmental governance impacts of the system on heavily polluting enterprises in pilot areas. Jiang and Sun [26] found that increased regulatory penalties for heavily polluting enterprises help curb tax avoidance behavior. Nie et al. [27] studied the impact on total factor productivity in enterprises, revealing that the audits boost total factor productivity in resource-intensive and heavily polluting publicly listed companies, thereby promoting revenue growth [28]. Quan et al. [29] found that implementing the departure audit leads to higher equity capital costs for resource-intensive and heavily polluting companies. However, political connections can mitigate this effect.
Research on the Impact of Environmental Regulation on Carbon Governance
In late 18th-century England, industrial production began to sprout and develop rapidly. This period saw the early days of the Industrial Revolution. Naturally, Britain became one of the key drivers of global economic growth. With innovations in textiles, coal mining, and metallurgy, these advances have not only changed the face of local society but also had a profound impact on Europe and the world. Environmental problems have followed, especially global warming. Carbon emissions are the prime culprit in global warming. Scholars from Western developed countries were the first to conduct empirical research into the influence of environmental regulation on carbon emissions. With the increasing prominence of climate issues, scholars from other countries have also entered this research field. Existing literature mainly explored the “green paradox” and has formed three representative views. Namely, the majority of scholars believed that environmental regulation effectively curtailed corporate carbon emissions [30-32]. Shapiro and Walker [33] studied the U.S. manufacturing industry’s output and air pollutant emissions from 1990 to 2008, finding that the decline in air pollution emissions was mainly due to stricter environmental regulations. Han et al. [34] discovered that locally binding targets for emission reduction effectively pushed enterprises to cut carbon emissions, mainly because of resource reallocation among enterprises rather than market entry and exit. However, some scholars remain skeptical of the effectiveness of environmental regulation. Wang et al. [35] evaluated the impact of the “Three Rivers and Three Lakes” policy (namely, the Huai, Hai, and Liao Rivers and Tai, Chao, and Dianchi Lakes). Lakes and rivers, just like Mother Earth's heart and blood circulation, flow across the Earth, nourishing life and maintaining ecological balance. These key water bodies are critical for water pollution control efforts that impact the socio-economic development of nearly half of China’s provinces, as well as the life quality of enterprises’ chemical oxygen demand (COD) emissions. They found that while many small polluting enterprises exited the market, the policy did not significantly affect the COD emissions of operating enterprises. Using the DID method, Bao et al. [36] analyzed the local environmental legislation and found that they did not effectively curb local carbon emissions. By contrast, in areas with vigorous law enforcement, the government adopted a series of tough laws to cut carbon emissions. Not only did they have stringent emission and environmental standards, but they also imposed economic sanctions on polluters and encouraged them to invest in green technologies. The noticeable environmental improvement came true. Li and Shen [37], using cross-provincial industrial pollution data, studied the carbon reduction effects of different regulatory tools, concluding that pollution charges significantly impacted carbon reduction, whereas subsidy and green loan programs were less effective. Some scholars argued that the impact was uncertain. China’s current environmental regulatory tools have not shown significant effects in forcing carbon reduction through technological innovation [38, 39]. Under new technological constraints, an inverted U-shaped relationship exists between formal and informal environmental regulation and unit carbon emission intensity. Specifically, both formal and informal environmental policies may play a positive role in reducing carbon emissions at an early stage. Over time, however, the effects of these controls began to weaken as people adapted to and became accustomed to stringent environmental standards, which bottlenecked their efforts and led to a rebound in unit carbon intensity to higher levels. Furthermore, the synergistic effect of both types of regulation followed a V-shaped pattern. Yang et al. [40] extended this by examining the aforementioned inverted U-shaped relationship. While loose regulations can pressure enterprises into “innovation compensation,” improving carbon productivity, stringent regulations can “crowd out” technological innovation, hindering progress.
Comments from Literature
In conclusion, while research on carbon governance and the natural resource assets departure audit is abundant, most of the literature focuses solely on the environmental performance effects of these audits [41- 45], with only a few addressing their carbon reduction impact. In existing research, few scholars can integrate the two aspects of carbon emission and carbon sequestration into a unified analytical framework. This integration is critical to the conduct of the departure audit, as it requires us not only to understand the production and absorption of greenhouse gases but also to explore their complex and dynamic interactions. Such a comprehensive analysis would enable us to better understand the environmental impacts of climate change and the strategies needed to implement measures to mitigate and adapt to them. However, current research tends to focus on a single indicator, ignoring the more complex ecosystem processes behind global warming, which can lead to misjudgments about the real situation and thus affect the effectiveness of policymaking and resource allocation. This paper uses the pilot implementation of the departure audit system, a uniquely Chinese environmental regulation, as the research context to investigate whether and how this system affects regional carbon balance. This study uses the ratio of carbon sinks (CA) to energy consumption carbon emissions (CE) as the carbon balance metric and employs the departure audit system as a quasi-natural experimental condition. In this study, by using a multi-stage dual differential (DID) model, the policy effects and transmission mechanisms of these audits on carbon balance are discussed. We aim to provide more solid empirical evidence for achieving China’s “dual carbon” goal through further empirical data analysis and deepen our understanding of the effectiveness of these audits. Through careful data collection and rigorous statistical methods, this study attempts to reveal how such audits directly or indirectly affect the relationship between economic activities and the environment. In addition, this study will evaluate the adaptability and persistence of the audit in different industries, regions, and time dimensions to comprehensively evaluate its feasibility and impact scope.
Theoretical Analysis and Research Hypotheses
Departure Audit of Leading Cadres on Natural Resource Assets and Carbon Balance
According to public choice theory, as rational economic agents, local government officials are driven to maximize their political accomplishments during their tenure to enhance their personal values and standing. Under the previous GDP-centric performance evaluation system, officials often prioritized short-term economic growth at the expense of environmental resources, which contradicted the tenets of sustainable development. The departure audit of leading cadres on natural resource assets serves as both a state audit policy tool and an indispensable environmental regulatory measure. Its primary function is to rectify officials’ performance-related behaviors and reshape local governments’ strategic decisions, ultimately contributing to carbon reduction, increasing carbon sinks, and fostering carbon balance. Consequently, this audit mechanism influences local governments’ decision-making regarding resource and environmental policies, encouraging officials to self-regulate, manage natural resources scientifically and rationally, and harmonize ecological civilization with economic development. These audits leverage independent and professional supervisory functions to ensure leaders fulfill their fiduciary responsibilities, implement environmental policies effectively, and appropriately allocate environmental governance funds [46]. This leads to an increase in urban green space and restoration of arable land, enhancing carbon sink capacity [47]. They also encourage local resource-intensive and heavily polluting enterprises to adopt a green development mindset and accelerate green technological innovations, promoting energy saving and emission reduction [5]. The following hypothesis is proposed:
H1: The departure audit can promote regional carbon balance.
Natural Resource Assets Departure Audit of Leading Cadres, Green Innovation, and Carbon Balance
The analysis of the impact of government environmental regulations on green innovation is largely based on the Porter Hypothesis, which suggests that appropriate environmental regulations can positively stimulate corporate innovation, enhance production efficiency, and ultimately relieve the financial burden of environmental protection. As an empowered environmental regulatory tool, the departure audit of leading cadres on natural resource assets imposes significant pressure on resource-intensive and high-pollution enterprises, compelling them to expedite their green technology innovation and contribute to the attainment of carbon neutrality.
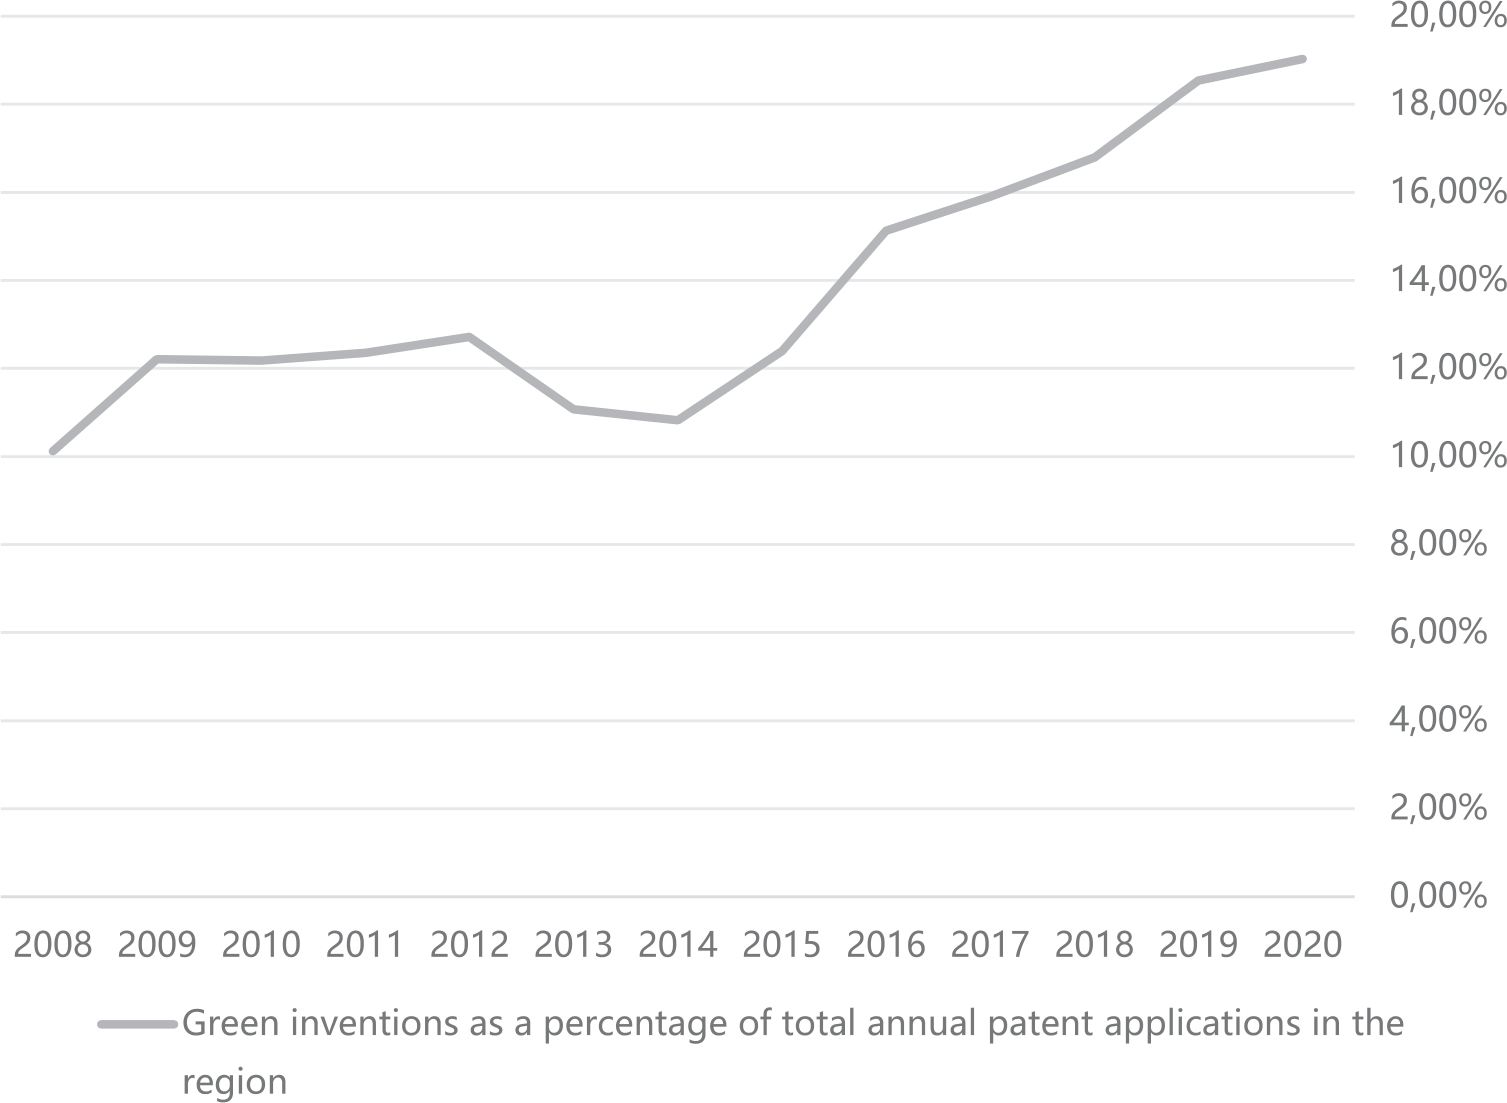
Specifically, when local enterprises’ high-carbon emissions are subject to government regulatory constraints, industrial enterprises must gradually adopt green production methods through technological innovation to avoid legal sanctions and financial penalties, effectively reducing industrial carbon emission intensity [48]. For example, in Tianjin, since the implementation of the departure audit in 2015, there has been a notable rise in the percentage of green innovation patents held by local enterprises. (as shown in Fig. 1). According to the Tianjin Municipal Bureau of Planning and Natural Resources, by 2020, the city’s total energy consumption had decreased by over 2 million tons of standard coal compared to 2015, and energy consumption per unit of GDP had declined by 19.1%. Additionally, the annual average PM2.5 concentration had dropped from 70 µg/m³ at the end of the 12th Five-Year Plan to 48 µg/m³. These figures indicate that the departure audit system has indeed played a significant role in promoting corporate green transformation and carbon emission control.
Implementing the departure audit system exerts dual regulatory effects, directly intensifying environmental compliance pressures on enterprises while concurrently reshaping the incentive structures of local governance actors, thereby generating secondary influences on corporate environmental strategic choices. Research shows that after the enactment of the departure audit, corporate environmental awareness and motivation significantly increased, leading to a substantial rise in environmental investments [49]. In the short term, enterprises facing environmental regulatory pressure may passively take measures such as production halts or output reductions to meet carbon reduction targets. However, in the long run, green technology innovations and introducing clean production equipment are more reasonable options to enhance energy efficiency and reduce CO2 emissions [50, 51]. Furthermore, the departure audit system prompts local governments to prioritize clean industry development and offer policy incentives ‒ such as tax breaks and government subsidies ‒ to enterprises with strong green innovation capabilities [52, 53]. These measures drive companies toward adopting zero-carbon energy technologies and clean production processes ‒ key drivers of regional decarbonization [54].
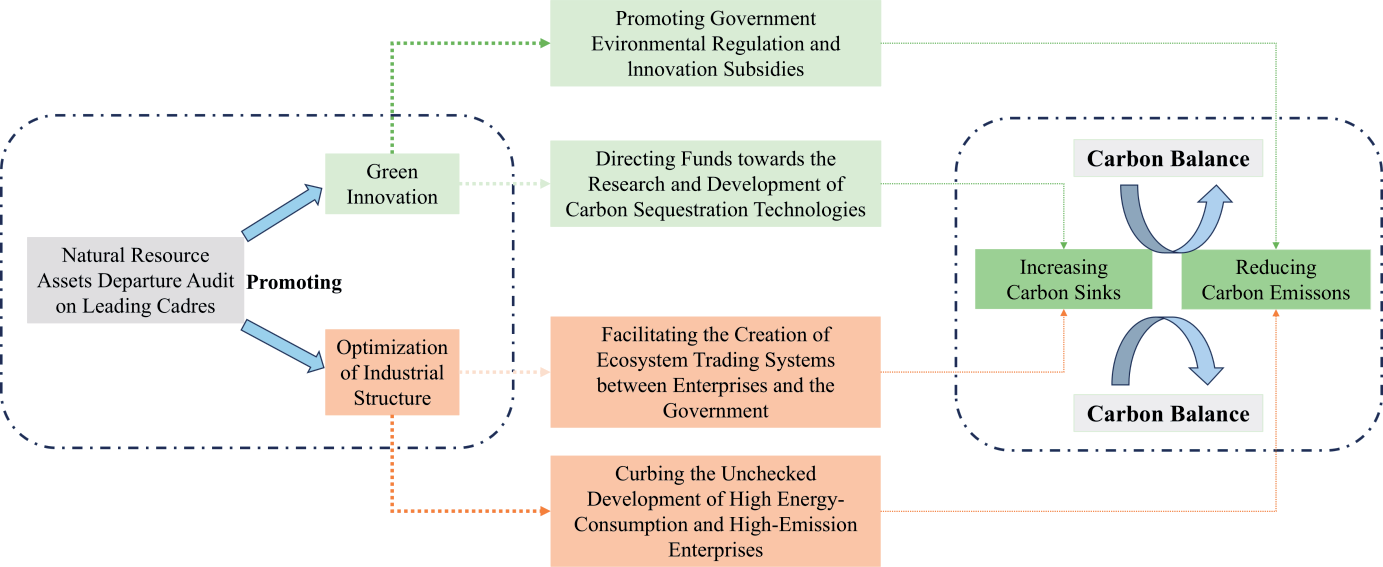
At the same time, enterprises actively explore carbon sink solutions to add economic value to ecological policies and products. For instance, Rizhao City employs ultra-high-temperature aerobic fermentation technology to manage waste and build carbon sink demonstration parks. By adopting green planting and production methods, besides ecological value, tea plantations and fruit orchards have also brought economic benefits. In turn, the increase in economic benefits offers financial support to enhance carbon sink capacity. In particular, the departure audit system encourages governments to increase investments in carbon sequestration and sink enhancement technologies. In Dadonggang Township, Xishuangbanna, Yunnan Province, research on the impact of distinct iron oxides on soil organic carbon accumulation has facilitated the advancement of iron oxide-based soil carbon sequestration technology. This method leverages alternating wet-dry cycles in soil conditions to promote nanomagnetite precipitation, significantly boosting soil carbon sequestration potential. Meanwhile, ongoing green agriculture and forestry projects further enhance terrestrial carbon sinks, contributing to regional carbon balance. These practices demonstrate that the departure audit system not only fosters technological innovation in emission reduction but also promotes the construction of carbon sink capacity.
It is thus proposed Hypothesis 2.
H2: The departure audit can promote carbon balance through green technological innovation.
Natural Resource Assets Departure Audit of Leading Cadres, Industrial Structure, and Carbon Balance
Institutional economics emphasizes the crucial role of institutions in shaping economic behavior. As a result, the formation of a region's industrial structure largely depends on the economic decisions made by the local government. Governments, driven by competitive pressures for economic growth and the motive to maximize tax revenue, often prioritize rapid GDP growth over low-carbon development and environmental governance. This results in the introduction of large-scale, capital-intensive industries to achieve quick economic growth, leading to an unbalanced industrial structure, severe environmental pollution, and increased carbon emissions [55]. Conversely, local governments that strive for high-quality economic growth with high-level environmental protection tend to have a more balanced industrial structure and foster greener, low-carbon economic development. The departure audit focuses on assessing party and government officials’ green performance and holds officials accountable for fulfilling their environmental fiduciary duties throughout their lifetime [56]. This can significantly influence leadership economic decision-making, shifting their focus from “prioritizing economic development and neglecting environmental governance” to promoting a green, low-carbon industrial structure. It encourages the collaboration between enterprises and governments to develop carbon market systems and carbon benefit-sharing ecosystems that complement each other, expanding ecological carbon sink channels and absorption capacity, thereby increasing ecosystem carbon sink increments.
Implementing this audit system creates a “crowding-out effect” on enterprises in heavily polluting and high-carbon industries [57, 58]. According to the “pollution haven hypothesis”, companies choose their location based on regional environmental regulation strength, which raises the “environmental barrier” of a region, making it difficult for high-pollution, high-carbon industries to enter the local market. Therefore, the implementation of this audit system can lead to the “exit” or “restricted entry” of such enterprises, which supports the growth of green, low-carbon industries and facilitates the optimization besides the upgrading of the industries [59]. In addition, these initiatives have helped to enhance corporate competitiveness, attract more investment, and create jobs, further cementing our leadership in the global economy.
H3: The departure audit can facilitate carbon balance through the effect of industrial structure optimization. (as depicted in Fig. 2)
Materials and Methods
Sample Selection and Data Sources
We selected 277 prefecture-level administrative regions in China from 2010 to 2020 as the research samples, excluding cities lacking crucial data, resulting in a total of 3,066 observations. Among these sample cities, 162 conducted pilot programs for the departure audit of leading cadres, with pilot information obtained from the websites of local audit agencies, the China Audit Yearbook, and related media reports. The baseline year for policy implementation is 2014. Furthermore, the number of cities conducting audit pilots from 2015 to 2017 was 19, 81, and 62, respectively. From 2018 onward, the audit system entered its nationwide promotion phase. Data on green innovation were collected from the green patents published by the China National Intellectual Property Administration; the data pertaining to industrial structure optimization were sourced from the China Statistical Yearbook; the Chinese Academy of Sciences provided net primary productivity (NPP) of vegetation data; and other control variables were sourced from the CSMAR database and the EPS Regional Economic Database.
Dependent Variable: Measurement of Carbon Balance
(A) Measurement of Carbon Emissions. Carbon emissions data for China are calculated using the latest accounting standards for three-scope emissions, which are defined as follows: Scope 1 is in reference to all direct emissions within a city’s jurisdiction, pertaining to those from transportation, buildings, industrial manufacturing, changes in land use in agriculture and forestry, and waste treatment activities. Scope 2 means energy-related indirect emissions outside the city’s jurisdiction mainly come from heating, cooling, and purchased electricity to meet urban consumption needs. Scope 3 indicates other indirect emissions from city activities that occur outside the jurisdiction except those mentioned in Scope 2, such as greenhouse gas emissions outside the jurisdiction.
(B) Measurement of Carbon Sinks. The carbon substance approximately accounts for forty-five percent of one plant’s dry matter unit, which can absorb about 1.62 units of carbon dioxide. Specifically, each plant can absorb about 1.62 carbon dioxide molecules per unit of dry matter, a number crucial to global climate change’s impact. By photosynthesis, plants not only provide themselves with the necessary nutrients and energy but also significantly reduce carbon emissions from the environment. Therefore, the carbon sequestration of vegetation CAi can be expressed as:
Where NPPi represents the net primary productivity of vegetation per unit area in region i, and Si represents the area of region i. The net primary productivity was estimated using the CASA model, integrating meteorological and remote sensing data [60].
(C) Measurement of Carbon Balance. Carbon balance serves as the dependent variable, which is specified as the ratio of vegetation carbon sinks (CA) to energy consumption carbon emissions (CE). This balance reflects the proportion of carbon dioxide (CE) produced by the absorption of carbon dioxide (CA) by vegetation through photosynthesis to the carbon dioxide (CE) produced by the release of carbon compounds from human activities. This ratio is a key barometer of ecosystem health, reflecting nature’s response to greenhouse gas emissions. In the context of global warming, accurate assessment and control of this ratio has become an important way to mitigate the impact. Therefore, an in-depth analysis of carbon balance is of irreplaceable importance for maintaining ecological balance, protecting biodiversity, and promoting green and low-carbon economic transition. This measure can better reflect the progress of regional carbon neutrality compared to individual carbon emission and carbon sequestration figures [61, 62]. Considering carbon emissions from human activities and the level of vegetation carbon sequestration, and referring to Han et al. and Ma et al. [63, 64], the carbon balance index (CBI) is defined as:
In Equation (3), CAi,t represents the carbon sequestration of vegetation in region i during year t, and CEi,t represents the carbon emissions attributed to energy consumption in region i during year t. Meanwhile, the carbon balance index can be categorized into three states:
When CBIi,t = 1, the region is in a state of carbon balance, indicating equal carbon emissions and absorption levels.
When CBIi,t<1, the region has excessive carbon emissions and insufficient carbon sequestration, indicating a carbon deficit.
When CBIi,t>1, the region’s carbon emissions are within the ecosystem’s capacity, indicating a carbon surplus.
Independent Variable
The independent variable is the departure audit. In 2014, the National Audit Office arranged for provincial auditors to carry out pilot projects for the departure audit. From 2014 to 2017, a total of 180 cities carried out pilot programs: 14 in 2014, 21 in 2015, 82 in 2016, and 63 in 2017. In the pilot cities, the value of Audit will be set to 1 for the pilot year and the following years. Otherwise, the value of Audit will be set to 0.
(A) Control Variables. This study also draws on related research [65] to control for other variables that may affect carbon balance, considering aspects such as macroeconomic characteristics, population and education characteristics, and fiscal characteristics of the cities. The macroeconomic characteristics include the status of the economy, the degree of financial development, and the openness level. Population and education characteristics include population size, technological level, and education standard. Additionally, the characteristics of local governments include the level of urbanization and the degree of government intervention.
(B) Mediating Variables. The green patents proportion in the total annual patent applications assesses the green innovation indicator. This figure not only mirrors the extent of emphasis enterprises or research institutions place on innovation within the domains of environmental protection and sustainable development but also constitutes a significant dimension for gauging their technological innovation prowess and market competitiveness. The industrial structure optimization indicator is obtained by calculating the difference in shares between the tertiary and the secondary industries in GDP. This method reflects the soundness of the industrial structure, furnishing policymakers with vital information concerning how to adjust and stimulate economic growth. Precisely measuring this proportion makes it possible to evaluate whether a country or region has accomplished industrial upgrading or is still entrenched in traditional manufacturing and resource-intensive sectors. Additionally, it can disclose which fields demand more investment, thereby driving the entire economy toward a more balanced and sustainable path. The specific definitions and measurement methods of the variables are detailed in Table 1.
Model Construction
Difference-in-Differences (DID) Model
The phased and incremental pilot implementation of the Natural Resource Asset Departure Audit provides a natural "quasi-experiment" for this study. Employing the difference-in-differences (DID) method, this paper conducts a causal inference analysis of the relevant changes during the pilot phase of the departure audit. This approach facilitates an objective evaluation of the policy’s governance effects on regional carbon balance and its underlying mechanisms. The model is specified as follows in Equation (4):
Table 1.
Variable definitions.
Table 2.
Descriptive statistics.
Where Controls represent the group of control variables, among which k means the number of control variables, i, representing the city, signifies the local-level variable. Similarly, t denotes the time or duration of the measurement. ε, on the other hand, denotes the random error term, indicating any unmeasured or inherent error within the model that might introduce an inconsistent result from its predictions. The city fixed effect u is associated with the fixed impact factor for city characteristics. Likewise, the time fixed effect λ represents the fixed impact factor for time considerations.
Mediating Effect Model
To verify the mediating role of green innovation conjoined with industrial structure optimization, we adopt the mediating effect test method outlined by Chen et al. [5]. This leads to the following mediating effect models: Mit represents the mediating variable indicating green innovation and industrial structure optimization. The other notations have the same meanings as previously described.
Table 3.
Baseline regression results.
Results and Discussion
Descriptive Statistics
Table 2 lists the descriptive statistics of the main variables. In general, the mean and median values of the dependent variable carbon balance (CBI) are 4.333 and 2.301, respectively, with a value ranging from 0.007 to 236.929, indicating significant differences in carbon balance across Chinese cities, attributable to varying levels of economic development, geographical distribution, and uneven distribution of carbon sink resources. The mean value of Audit is 0.221, suggesting that about 22.1% of the sample was affected by the pilot program during the study period. Additionally, the descriptive statistics for other variables fall within reasonable ranges.
Baseline Regression Analysis
Regression analysis was performed by employing model (4) to test the previously proposed hypotheses. Results are in Table 3. Evidently, applying CBI as the dependent variable, the coefficient for the departure audit is incredibly positive, indicating that regions implementing the audit achieve more effective carbon balance compared to those that do not. Columns (1) and (2) respectively present the regression results of the departure audit on leading cadres’ accountability for the pilot areas and the full dataset after controlling for related variables. The regression coefficient of the departure audit on the carbon balance (CBI) for the full dataset is 2.552, which is relatively significant at the 1% level. Overall, the audits can effectively enhance regional carbon balance. These results confirm H1 of this study.
Robustness Tests
Parallel Trend Test
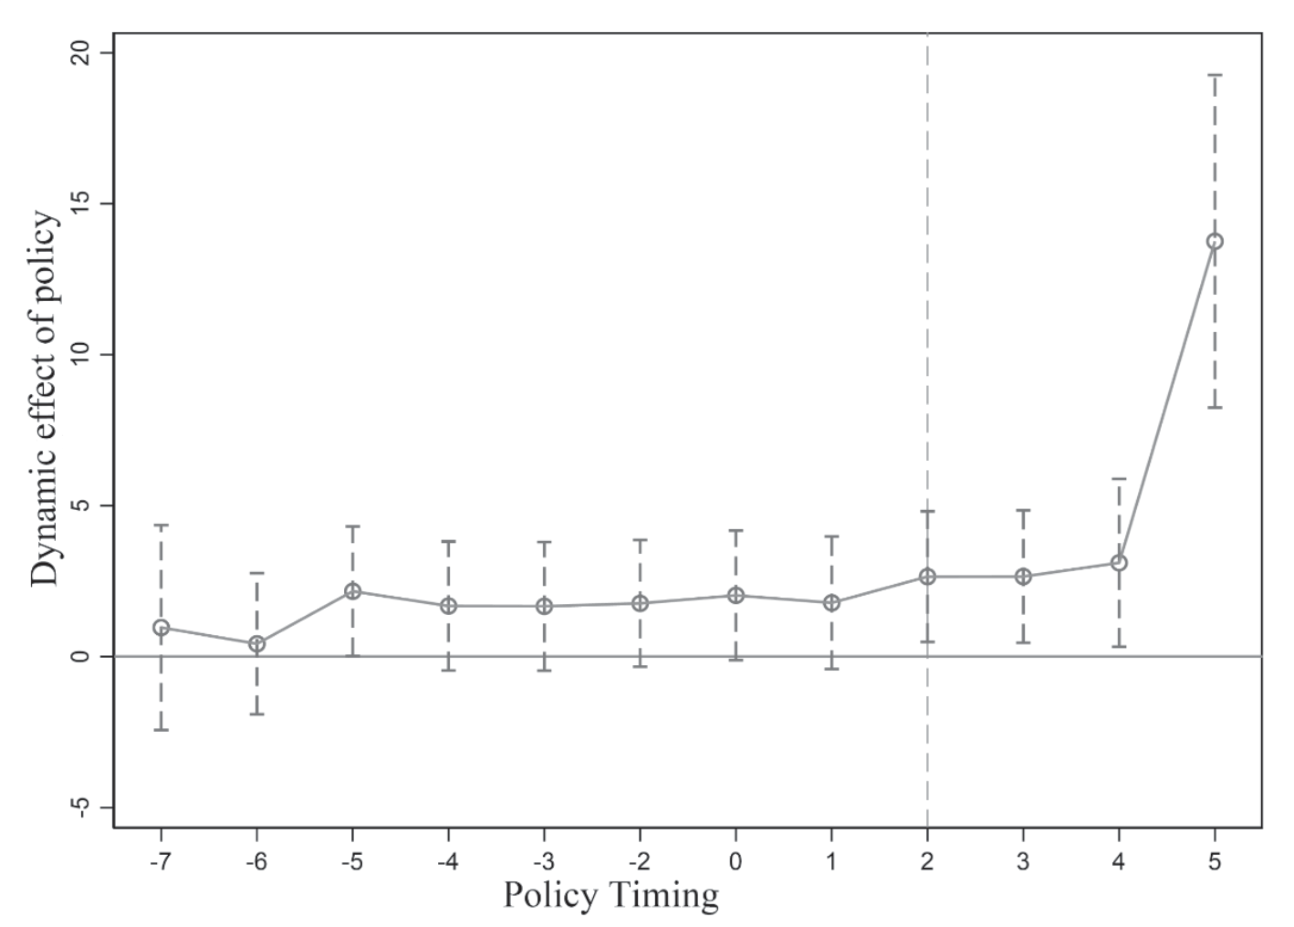
A prerequisite for using the DID approach is that the experimental and control groups exhibit a common trend. This means that regions implementing the policy earlier and those implementing it later, as well as regions implementing the policy and those not implementing it, should not have systematic differences before the policy implementation, or if differences exist, they should be constant. The validity of the DID method relies heavily on the assumption of a parallel trend, meaning that if the pilot policy for the departure audit is lacking, the trend of carbon balance changes between pilot cities and others would be parallel. A parallel trend test was conducted using regression analysis (Fig. 3). Moreover, the regression results in Fig. 3 reveal that the regression coefficients were not significant before the pilot audit policy. However, the coefficients became significantly positive starting from the pilot year and continuing into the second year after implementation. This demonstrates that the DID test fulfills the parallel trend assumption. Positive effects of the departure audit on carbon balance appeared in the pilot year and continued to promote carbon balance into the second year of implementation, with the degree of promotion increasing over time.
Replacing the Dependent Variable
To secure reliable findings, the carbon ecological carrying capacity (ESC) [66] was used as an alternative variable to carbon balance (CBI). ESC represents the ratio of a city’s carbon sink share to the national total relative to its carbon emissions share of the national total. This indicator helps identify the capacity of carbon sinks to offset carbon emissions, reflecting the strength of carbon balance capability. Table 4 clarifies the regression results, considering control variables and fixed effects. The carbon ecological carrying capacity (ESC) shows a significantly positive relationship with the audit pilot (Audit) at the 1% statistical level. The conclusions remain consistent.
Lag Period Test
To address potential endogeneity issues between the departure audit and carbon balance (CBI), this study conducted regressions with the essential core explanatory variable, Audit, lagged by one and two periods. The regression results in Table 5 illustrate that the audit coefficients for both lagged periods are notable at the 1% level. What’s more, this suggests that the audit promotes CBI, which is compatible with earlier findings, demonstrating that the conclusion holds water.
Placebo Test
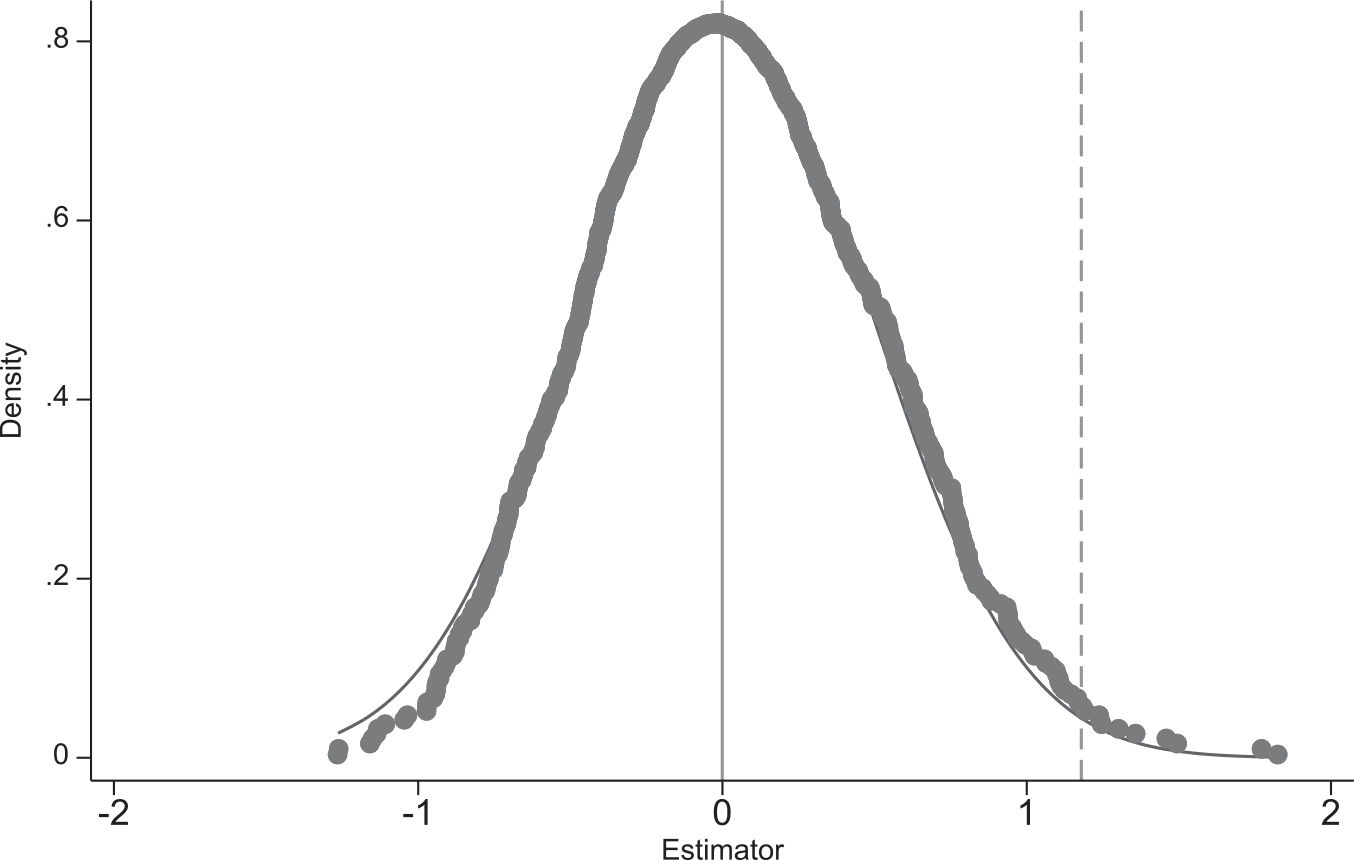
When examining the effects of a policy over multiple years using a DID model, serial correlation can introduce bias into the estimates, leading to inaccurate results. To validate whether other unobserved factors influence the empirical results, we follow the approach of Li et al. [67], as do Ren et al. [68], conducting 1,000 random samplings and regression analyses to check if the estimated coefficients significantly differed from the baseline regression results. Certainly, in Fig. 4, the regression coefficients from the randomly assigned experimental groups are concentrated around zero. This implies that the positive effect of the audit on promoting green development is not influenced by omitted variables, confirming that the regression results align with expectations.
Table 4.
Replacing the Dependent Variable.
Table 5.
Lag Period Test.
Endogeneity Test
Given the time lag between audit initiation and observable changes in carbon balance attributable to audits and the bidirectional causal relationship between carbon balance levels and audit enforcement intensity, this study employs an instrumental variable approach to address potential endogeneity. The instrumental variable is constructed by lagging the departure audit variable by one period, and regression analyses are conducted using 2SLS, LIML, and GMM (see Table 6). The lagged departure audit serves as a valid instrument because it is uncorrelated with the error term and strongly correlated with the current-period departure audit. The regression results show that the coefficient of departure audit pilot implementation (Audit) on the Carbon Balance Index (CBI) is positive and statistically significant at the 1% level, indicating that the departure audit of leading cadres on natural resource assets promotes carbon balance. This conclusion is evidently consistent with previous findings.
Additionally, to account for the potential impact of differences in characteristics between the treatment and control groups of cities on regression results, this study employs the Propensity Score Matching Difference-in-Differences (PSM-DID) method. Trimming the samples before regression improves the comparability between treated and control groups. The study uses control variables as covariates for caliper nearest-neighbor matching, setting the caliper at 0.001. In nearest-neighbor matching, only control group individuals within the predefined caliper range are considered the closest match to the treatment group individuals. After matching, the sample size is reduced to 1,900, and a multiple-period DID regression is performed on the matched sample. The results show that audits have a positive and significant effect on CBI at the 10% level, confirming the robustness of the findings (see Table 7).
Excluding the Influence of Other Policies
Since the 18th National Congress in China, which highlighted the “vigorous promotion of ecological civilization”, the content of the national environmental policy framework has expanded. Expanding the national environmental policy framework mainly includes developments in new lawmaking, law revision, system construction, governance goals and tasks, management systems, and the public-action system. Among them, new law-making has filled legislative gaps in relevant fields, providing legal bases and guarantees for specific regions, specific ecological and environmental problems, and emerging environmental fields. Law revision has made legal norms more specific, enhancing their enforceability and operability. The construction of systems such as the red line, environmental impact assessment, pollutant discharge permits, and ecological compensation systems has become more robust. Governance goals and tasks such as the battle against pollution, carbon peaking and neutrality, and ecosystem protection and restoration have become clearer. Management systems such as ecological-environmental zoning control and the upgrading of the environmental monitoring system have become increasingly refined. The public-action system has been gradually established, including publicity, education, and public participation. Therefore, it is necessary to verify whether changes in government environmental governance during the study period could be affected by other environmental policies, ruling out noise from similar policies. This study considers that the Central Environmental Inspection, implemented starting in 2016, will most likely interfere with the estimated results due to overlapping timelines and policy targets with the natural resource asset audit pilot. To account for this, the model was adjusted to include Environmental Inspection (Inspect) as a control variable. If a province, autonomous region, or municipality was subject to environmental inspection in that year, Inspect was assigned a value of 1; otherwise, it was 0. Through Table 8, even after including the variable (Inspect), the audit pilot continued to promote regional carbon balance. This confirms that the main regression results are reliable.
Further Research
Heterogeneity Based on Geographical Location
To examine the influence of geographical location, the study divided the samples into the developed eastern regions, the resource-rich central regions, and the vast western regions for grouped regression analysis. The eastern region enjoys several natural resource advantages, primarily abundant marine resources with huge potential for marine energy, excellent port resources, and favorable climatic conditions. In the western region, the main natural resource advantages are rich energy resources, abundant water-energy resources, concentrated mineral resources, and extensive land areas. The central region mainly features diverse mineral resources, sufficient water resources, and superior agricultural resources. Table 9 shows that the natural resource assets departure audit significantly affects carbon balance in all regions, indicating that it effectively promotes carbon balance among the various regions. By and large, the promotional effect is more potent in the western regions. Compared to the eastern region, the industrial structure in the other two is more homogenous and dominated by heavy industry, which poses greater environmental risks. This may result in local officials facing higher environmental pressure. Additionally, some central and western cities face economic growth challenges and increased uncertainty due to resource depletion and price fluctuations [69]. Thus, officials in these regions may place more emphasis on ecological issues, leading to a stronger effect of the audits on carbon balance.
Table 6.
Instrumental Variable Test.
Table 7.
Propensity score matching regression results.
Table 8.
Excluding the influence of other policies.
Heterogeneity Based on Carbon Sink Resources
Heterogeneity analysis was also conducted based on regional carbon sink resources. According to the median value, cities were divided into groups with fewer and more carbon sink resources. Table 10 shows that leadership cadre audit and carbon balance regression coefficients are overwhelmingly positive in both groups, with a stronger effect in regions with richer carbon sink resources. This depicts that the richer the carbon sink resources, the more tremendous the effect of the audits on promoting carbon balance.
Table 9.
Heterogeneity based on geographical location.
Natural resource endowments determine a city’s development model [70]. Universally speaking, coal resources are the "cornerstone" of industrial development. Cities with abundant carbon resources often develop resource dependence, leading to excessive carbon emissions and significant damage to carbon sink areas, which hinders carbon balance. Thus, such cities have more room for improved carbon reduction and sequestration and can leverage the departure audit to enhance carbon balance.
Heterogeneity Based on Institutional Environment
The institutional environment also affects the effectiveness of environmental policy implementation. Natural resource asset departure audit functions as a dynamic governance process secured by both internal and external regulations, and their governance effects vary under different external regulatory environments. Elaborately, governance mechanisms are more likely to be more effective within a strictly regulated market environment. This is because enterprises are obliged to adhere to more rigorous regulations and standards, thereby enhancing their compliance and stability. Conversely, governance mechanisms might be relatively feeble in a relatively lax regulatory framework, as adequate regulations are deficient to guarantee that enterprise behaviors comply with the established legal requirements.
Table 10.
Heterogeneity based on carbon sink resources.
Considering regional differences in the institutional environment, this study divided the sample into three groups ‒ weak, medium, and strong ‒ based on the data from the China Provincial Marketization Index Report by Wang Xiaolu et al. The regression results of model (5) for each group are in Table 11. The results show that the audit pilot is not associated with carbon balance (CBI) in a group with a weak institutional environment. In contrast, in the medium and strong institutional environment groups, the coefficients between the dependent variable and the audit pilot (Audit) are remarkably positive at the 1% level. In general, regions with a stronger institutional environment are more conducive to effective governance, with better resource allocation, a robust legal system, and high-quality development policies that provide a foundation for the departure audit.
Table 11.
Heterogeneity based on institutional environment.
Mechanism Testing
This study included mechanism variables in the baseline regression and observed their effect on the carbon balance index to further reveal the internal mechanisms through which the new urbanization policy affects carbon balance.
Table 12 reveals that the coefficient between the natural resource asset audit pilot and the green innovation mediator is 0.005. After including the environmental regulation variable, the coefficient between the carbon balance and the green innovation mediator is 19.839, and the coefficient between the audit pilot and the carbon balance is 2.443. This indicates that green innovation acts as a mediator in promoting carbon balance, supporting H2.
Table 13 conveys that the coefficient between the audit pilot (Audit) and the industrial structure mediator is 0.162. After including the industrial structure mediator, the coefficient between the carbon balance and the industrial structure mediator is 0.073, and the coefficient between the audit pilot and the carbon balance is 2.670. This indicates that the industrial structure mediator intervenes in promoting carbon balance, confirming Hypothesis H3.
Table 12.
Green Innovation Mediating Effect Test.
Conclusions
Research Findings
Analyzing panel data from 277 Chinese cities between 2010 and 2020, this study used the departure audit, implemented in 2015, as a near-natural experiment to empirically investigate its effects on urban carbon balance, the mechanisms involved, and regional heterogeneity. The main conclusions are as follows:
(1) Baseline results indicate that the departure audit policy promotes urban carbon balance. The robustness of these findings was confirmed through placebo tests, exclusion of other policy interferences, parallel trend tests, lag effect analysis, and propensity score matching. Mechanism tests showed that the policy impacts carbon balance through mediators such as green technology innovation and industrial escalation.
Table 13.
Industrial Structure Optimization Mediating Effect Test.
(2) Heterogeneity analysis revealed significant regional differences in the policy’s effects. When considering factors such as geographical location, urban carbon sink resources, and the strength of the institutional environment, it was found that the policy more effectively promotes carbon balance in areas rich in carbon sinks compared to those lacking in such resources. Similarly, it is more effective in regions with a stronger institutional environment than in those with weaker environments. In conclusion, carbon balance policies carry greater weight in the western regions.
(3) Analysis by different implementation years shows that the policy’s influence on regional carbon balance becomes more significant. This may be attributed to the continuous introduction and improvement of audit pilot documents and an increasingly comprehensive audit system, which allows local leaders to better utilize audit results to promote regional carbon balance.
In terms of indicator design, this study adopts a comprehensive measure ‒ “carbon balance” ‒ rather than relying solely on carbon emission levels. This approach offers distinct advantages when evaluating integrated environmental policies, especially those simultaneously involving industrial emission reductions and ecological conservation efforts, such as in China’s western regions. Unlike conventional indicators focusing only on emissions, the carbon balance metric captures the dynamic relationship between carbon sources and sinks within a region, offering a more complete picture of policy effectiveness in addressing climate change. Methodologically, we employ the Difference-in-Differences (DID) approach, treating the Natural Resource Asset Off-Office Audit policy for leading officials as a quasi-natural experiment to assess its impact. In contrast to traditional methods that do not incorporate DID, this approach significantly enhances causal inference capabilities. By systematically comparing the "treated" and "control" groups both before and after policy implementation, DID effectively mitigates potential endogeneity issues stemming from non-random policy assignment. It also takes into account temporal trends and pre-existing disparities between groups, thereby enabling the generation of more robust and reliable estimates of the policy's genuine effect. The rollout of the audit policy aligns well with the assumptions required for a quasi-experimental design. The central government selected the pilot cities, which were not directly related to local carbon balance conditions prior to the policy. Furthermore, the timing of the first round of pilots in 2015 and subsequent expansions was clearly defined, satisfying the exogeneity requirement. In light of this, our study employs a multi-period DID framework, which is better suited than static models for analyzing policies rolled out gradually over time. This approach offers a useful reference for evaluating similar phased initiatives, such as the 2023 carbon peaking pilots, the “Zero-Waste City” program launched in 2019, and the Green Finance Reform Pilot Zones established in 2017. From a practical perspective, this paper delves into the moderating roles of carbon sink resource endowments and institutional environments in the audit policy's impact on carbon balance. The findings reveal the potential for synergistic carbon reduction between the audit system and other emission-reduction, sink-enhancement, and efficiency-improvement policies, offering theoretical support and policy recommendations for promoting low-carbon sustainable development in different types of cities. The conclusions also provide important decision-making references for refining the audit system and optimizing ecological and environmental governance mechanisms.
Policy Recommendations
China’s 14th Five-Year Plan Outline underlines the central government’s guidance implementation to strengthen the departure audit of leading cadres on natural resource assets. This initiative focuses on major tasks such as natural resource asset management, carbon peaking, carbon neutrality, and pollution prevention and control, accelerating the establishment and improvement of audit evaluation standards and indicator systems to ensure that government officials fulfill their responsibilities in ecological civilization construction. This measure is not only closely aligned with China’s dual carbon goals (carbon peaking by 2030 and carbon neutrality by 2060) but also strongly corresponds to the United Nations Sustainable Development Goals (SDGs), especially Goal 13 (Climate Action) and Goal 15 (Life on Land). Building on the research findings, this study proposes the following policy recommendations to enhance the constructive role of departure audits of natural resource assets in promoting carbon balance, strengthening global climate governance, and providing practical insights for local governments to implement the International Union for Conservation of Nature (IUCN)’s Nature-based Solutions (NbS):
(1) Strengthen local leadership as guardians of nature. Economic growth relies on the departure audit. Local leaders should actively follow the internal mechanisms of these audits and integrate natural resource audits into their accountability and promotion systems to enhance local environmental regulation intensity. Additionally, it is recommended that governments worldwide take on a stronger role in promoting the implementation of NbS. By reinforcing government leadership and coordination, countries can lead global environmental governance efforts and work toward achieving carbon balance.
(2) Pay close attention to the positive impact of the departure audit on carbon balance. Given the differences in urban carbon resource endowments, institutional environments, and geographic locations, policy implementation should be adapted to local conditions. The government should intensify audits in cities with fewer carbon sink resources while improving the institutional environment in cities with abundant carbon sinks to amplify the audit’s positive impact on high-quality economic growth. Moreover, it is advised that countries worldwide should strengthen carbon sink resource accounting and international cooperation, particularly by leveraging natural resource audits to drive progress toward global carbon balance goals. This would preserve the validity of the Paris Agreement and the 2030 Sustainable Development Agenda.
(3) Improving the evaluation indicator system for the departure audit, the audit deserves to be highlighted, and the responsibilities of party and government leaders in ecological protection and green development should be clarified. This would provide a clear basis for holding leaders accountable and enhance the audit’s role as both an incentive and a constraint. At the same time, it is suggested that the international community should strive to establish a unified global framework for natural resource asset accounting. This would facilitate experience-sharing among countries in natural resource management and climate action, providing an institutional foundation for securing a sustainable future.
This study has some limitations. Due to the constraints of remote sensing technology, accurately identifying and assessing carbon sinks is challenging, which may affect the precision of carbon balance metrics. The reasons are as follows:
(1) The spatial resolution of remote sensing technology may not be sufficient to accurately distinguish different types of carbon sink areas. For example, for some small ecological patches with significant carbon sink functions, such as small wetlands or special vegetation communities in urban green spaces, low-resolution remote sensing images may blend them with the surrounding environment, making it impossible to accurately define their boundaries and areas, thus affecting the accurate calculation of carbon sink amounts.
(2) Carbon sink’s dynamic changes require monitoring with high temporal resolution. However, the existing remote sensing technology may not be able to meet the need for frequent observations. For example, vegetation’s carbon absorption capacity varies greatly during different seasons and growth stages. Suppose the time interval between remote sensing monitoring is too long. In that case, key growth change points may be missed, leading to deviations in assessing carbon sink amounts and failing to accurately reflect their true carbon sink functions within a specific period.
(3) The spectral characteristics of different types of carbon sinks (such as forests, grasslands, farmlands, wetlands, etc.) and the same type of carbon sink under different environmental conditions (such as different soil moisture and nutrient conditions) may have similarities and variabilities. This makes it difficult to accurately identify the types of carbon sinks solely based on spectral information. For example, the grasslands in some arid areas and degraded forests may exhibit similar characteristics in specific spectral bands, which is prone to misjudgments.
(4) Atmospheric conditions (such as clouds, aerosols, etc.) will interfere with remote sensing signals. The occlusion of clouds will prevent some areas from obtaining accurate remote sensing data in a timely manner. The scattering and absorption effects of aerosols will change the radiation signals received by remote sensing sensors, thereby reducing data quality and affecting the identification and evaluation of carbon sinks, especially in areas with frequent clouds or serious air pollution.
(5) The large amount of data obtained from remote sensing requires complex processing and analysis techniques. The current data processing algorithms may not be perfect enough to accurately extract key information related to carbon sinks from the massive data. Moreover, for some complex carbon sink ecosystems, combining remote sensing data with field survey data, model simulation data, etc., for accurate interpretation is also challenging.
Future research should explore more precise methods for calculating carbon balance. Additionally, this study’s examination of the mechanisms through which these audits affect carbon balance may not be comprehensive, as these pathways are multifaceted. Future research could consider other mediating factors to enrich existing studies.

