

Introduction
Since the reform and opening up, the extensive production mode has made China's economy achieve world-renowned achievements, but it has also burdened the ecological environment. For example, from 2001 to 2010, China’s national GDP grew at an average annual rate of 10.3%, but this came at the cost of an average yearly growth rate of 14.3% in industrial emissions1. Environmental pollution not only threatens human health but also causes harm to the ecosystem. In response to this challenge, the 20th National Congress of the Communist Party of China pointed out, “Accelerating the green transformation of the development mode.” From the perspective of practical experience, green innovation of enterprises plays a vital role in achieving this transformation by reducing corporate pollution. Green innovation mainly refers to technology innovation that reduces energy 1 Data from China Statistical Yearbook consumption and environmental pollution [1]. In Braun et al. [2], green innovation can be divided into two types: (1) Innovative activities that reduce resource consumption and environmental pollution from the source and (2) Innovative activities that treat an already polluted environment. The environmental protection effects of green innovation can also be categorized into two types [3]: On the one hand, green innovation can carry out the technological transformation of energy-intensive equipment. Such green innovation reduces pollutant generation by reducing the energy consumption of energy-intensive equipment, which is called source governance. On the other hand, green innovations help improve pollution treatment equipment and treat already-produced pollutants, which is called end-of-line governance. Given the significance of green innovation in environmental governance, China must actively engage in green innovation activities to achieve green transformation. Green innovation is not “water without a source or a tree without a root.” The input of green innovation resources is a crucial link to improve the output of green innovation. Although relevant studies have not yet formed a unified definition standard for the composition of green innovation resources, the existing literature generally believes that green innovation talents and green innovation funds are essential resources. First, as the carriers of green innovation knowledge, green innovation talents are crucial for enterprises to complete the integration of old and new knowledge and then to enhance the ability of green innovation. Second, green innovation is a complex activity characterized by high adjustment costs and time-consuming and large investments, which require adequate and continuous financial support [4]. In summary, talent and capital are essential resources for enterprises to carry out green innovation activities. However, Chinese enterprises generally face a shortage of these two innovation resources [5]. Given this, how to promote the independent and orderly gathering of green innovation funds and green innovation talents to enterprises has become a major theoretical and practical issue that the Chinese government needs to solve urgently. The green talent policy introduced by Chinese cities may help to solve this problem. Green talent policies attract green innovation talents to work locally through preferential measures such as living allowances, honorary recognition, and settlement. The green talent policy’s increase in urban green human capital helps local enterprises hire more green talents at lower costs. In addition, as talent is crucial to innovation, more green talent participating in a firm’s green innovation is equivalent to signaling external funding providers that the firm’s green innovation is more likely to succeed. This positive signal helps the firm to obtain more external financing. According to the above analysis, green talent policy helps local enterprises obtain the resources2 needed for green innovation. Thus, a green talent policy is expected to enhance local firms’ green innovation capability.
This research has implications for many countries, especially developing ones. In recent years, the greenhouse effect and environmental deterioration have threatened human survival. This environmental problem is more severe in developing countries because these countries have adopted an extensive development model over the past few decades at the expense of environmental costs [6]. Green innovation is considered a critical solution to the contradiction between environmental pollution and economic development [7]. Thus, the most pressing issue developing countries face today is how to enhance their innovation capacity. Compared with other innovation practices, green innovation requires substantial capital investment and specialized knowledge [4], which happens to be lacking in many developing country enterprises. Therefore, our findings may have rich policy implications. Suppose a green talent policy can help local firms access resources such as green talent or green capital. In that case, governments in developing countries can improve their green innovation by formulating green talent policy. However, to the best of our knowledge, no literature currently explores this topic.
As the largest developing country in the world, China provides a good setting for us to study the relationship between green talent policy and green innovation. The reasons are as follows. As China’s population quantity dividend gradually ends, the population quality dividend has become a key force driving China’s economic growth. To compete for high-quality talent, Chinese cities opened the prolog of the “talent competition war” and issued a series of talent policies successively. Simultaneously, China’s awareness of environmental protection has been growing, prompting some cities to embed the demand for environmental protection into their talent policies and to issue green talent policies specifically to attract and cultivate green talent. However, some cities in China have not yet formulated green talent policies for various reasons. This scenario provides a quasi-natural experiment for us to study the impact of green talent policy on green innovation. Firms located in cities that have enacted green talent policies constitute the treatment group, while other firms in cities without such policies will serve as the control group.
Using Chinese A-share listed firms as the study sample, we hand-collected green talent policies from 49 major cities in China to explore the relationship between green talent policy and green innovation. Our findings indicate that enacting green talent policies by Chinese cities increases the level of green innovation among local firms. Furthermore, in line with our expectations, being able to drive green talent and capital to local enterprises are two ways green talent policy affects corporate green innovation. Specifically, our results demonstrate that compared to enterprises in regions that have not promulgated green talent policy, enterprises in areas that have promulgated green talent policy can hire more CEOs with green experience. Not only that, but we also find that green talent policies can help ease financing constraints for local firms. Additional analyses show that the impact of green talent policy on corporate green innovation is more pronounced in talent-deficient firms, in green credit less developed regions, and in highly market-oriented areas. Finally, our findings hold after a series of robustness checks.
Our study contributes to the existing research in several ways. First, our findings expand the literature on the factors affecting corporate green innovation. Most prior studies on the determinants of corporate green innovation focus on environmental regulation, corporate governance, and executive characteristics [8-11]. In contrast, we demonstrate that green talent policy matters in corporate green innovation.
Second, we add research on the economic consequences of talent policy. Most scholars who have discussed the talent policy focus on evaluating its attractiveness to talents, comparing its differences across regions, or sorting out its evolution. There is limited literature exploring its economic consequences. Only a few studies have discussed the economic consequences, which find that talent policy impacts executive compensation, corporate human capital, total factor productivity, enterprise market value, and so on [12-15]. We complement these studies by providing evidence that green talent policy promotes green innovation.
Third, this paper provides new evidence for the Chinese government to evaluate the effectiveness of talent policy. In recent years, cities in China have enacted a series of talent policies in succession. However, these talent policies require considerable fiscal funds, which imposes a financial burden on the government, so evaluating the effect of talent policies’ implementation is essential. This paper examines the impact of green talent policy on green innovation, which can provide insights for government decision-making regarding continuing these policies.
Fourth, the practical implications of our findings extend to other emerging market countries seeking to improve their green innovation capabilities. Our findings demonstrate that green talent policies promote green innovation for local firms. Therefore, if developing countries aspire to elevate their level of green innovation, local governments can issue a policy that specifically trains or introduces green talent.
The remainder of this paper is as follows. Section 2 outlines the institutional background and conducts a literature review; Section 3 proposes research hypotheses; Section 4 introduces sample selection, variable definitions, and research design; Section 5 reports main results and robustness checks; Section 6 explores potential mechanisms and conducts the moderating analysis; and Section 7 summarizes the main conclusions and puts forward policy implications.
Institutional Background and Literature Review
Institutional Background
Talent policy is a normative document formulated by Chinese cities in order to attract outstanding talents from other places to work locally or train local talents. The policy attracts and cultivates talents by giving them material and spiritual rewards. The green talent policy focuses on introducing and cultivating green talents. Green talents are those who can make outstanding contributions to saving resources and reducing environmental pollution. In the context of China’s high priority on environmental issues, municipal governments in many cities have introduced a green talent policy. For example, “The Implementation Opinions on the Introduction of Thousands of High-level Innovative and Entrepreneurial Talents” issued by Suzhou City mentioned that it is necessary to focus on introducing high-level talents in the field of energy conservation and environmental protection. Kunming issued the “Opinions on Further Strengthening the Introduction, Training, and Use of Talents”, focusing on introducing high-level talents in environmental protection. Wuhan promulgated the “Opinions on Strengthening the Management of the Selection and Promotion of Various Experts in Wuhan”, openly selecting talents with outstanding performance in new energy and other aspects. Chongqing pointed out in the “Implementation Rules of Chongqing’s Preferential Policies for Introducing Talents” that the key majors to be introduced are ecology and environment. This paper collects the talent policies of 49 cities in China and selects the green talent policies among them through manual reading. This chapter lists the total number of green talent policies issued by these 49 cities from 2007 to 2021 in Table 1. As can be seen from Table 1, the city that enacted the most green talent policies during 2007- 2021 is Tianjin. This may be because Tianjin is heavily polluted, so the local government pays special attention to energy conservation and environmental protection.
Literature Review
Literature Review of Factors Influencing Green Innovation
Research perspectives on the factors influencing green innovation can be roughly divided into two categories: external environmental perspectives and internal environmental perspectives. The literature on external environment perspectives is mainly concerned with the influence of institutions and stakeholders on green innovation. For example, Kathuria [16] pointed out that command-based environmental regulations promote green innovation by imposing administrative penalties on polluting firms. In contrast, market-based environmental regulations incentivize green innovation by enabling firms that reduce emissions to earn market revenues. As another example, Liu et al. [17], used the implementation of China’s new Environmental Protection Law as a quasi-natural experiment to examine the effect of environmental regulation on firms’ green innovation and found a significant increase in the number of green patent applications after implementing the Environmental Protection Law. In addition, studies on the relationship between institutions and green innovation include: He et al. [18] found that green credit stimulates corporate green innovation; Ma et al. [19] found that low-carbon city pilot policies are conducive to firms’ green innovation; Wang et al. [20] believed that the environmental protection tax in China has a significantly negative effect on green technology innovation, and so on. Stakeholders are also the focus of scholarly attention when studying green innovation. For example, He et al. [21] examined Chinese non-financial listed firms from 2011-2020 and found that retail investors’ attention promotes corporate green innovation. Huang et al. [22] explored the impact of customer concentration on green innovation among Chinese listed firms and found that large customers positively affect corporate green innovation. Gu [23] demonstrated that competitors’ green innovation behavior positively affects firms’ green innovation. Unlike the external environment perspective, the literature on the internal environment perspective explores the factors influencing green innovation at three levels: Enterprise resources level, corporate governance level, and managerial characteristics level. The details are as follows: (1) Enterprise resources level. It has been documented that financial resources, intellectual capital, and so on are determinant factors for corporate green innovation [24, 25]. (2) Corporate governance level. Scholars generally agree that firms with good corporate governance have more green patents. For example, Asni and Agustia [26] found that effective governance mechanisms can promote green innovation. Specifically, the board size, ownership concentration, and independent commissioners positively affect green innovation. (3) Managerial characteristics level. Existing literature found that politically connected, overseas background, hubris, hometown identity, marketing experience, and other executive characteristics affect corporate green innovation [4, 27-30].
Table 1.
Total number of green talent policies issued by each city from 2007 to 2021.
In summary, although green talent policy is an important element of institutions, the existing literature has not explored its impact on green innovation.
Literature Review of Talent Policy’s Economic Consequences
Since Wuhan’s introduction of the “Double Million” program in 2017, which triggered a nationwide “war for talent,” research on talent policy has gained significant attention among Chinese scholars. The existing literature assesses the attractiveness of talent policy to talent, reviews the historical evolution of talent policy, and compares talent policy across different regions [31-36]. In addition to this, the studies on talent policy also include an examination of its economic consequences. For example, Jin and Peng [37] used the talent policy enacted by various regions of China as a quasi-natural experiment to test the impact of talent policy on corporate human capital. The results indicate that the talent policy significantly improves the human capital level of local enterprises. Li et al. [38] used the data of A-share listed firms in Shanghai and Shenzhen from 2001 to 2016 as the research sample to examine the impact of talent policy on corporate total factor productivity. The findings suggest that talent policy enhances the total factor productivity of local enterprises. Chen and Fang [13] found that Chinese cities’ talent policy has significantly reduced executive compensation’s sensitivity to performance.
Overall, while a number of studies have explored the economic consequences of talent policy, little literature systematically explores the impact of green talent policy on green innovation.
Hypothesis Development
According to the resource-based theory, resources are the foundation of enterprise development and play an important role in business management, especially precious, scarce, and irreplaceable resources. The core idea of resource-based theory is that the competitive advantage of an enterprise comes from its internal resources. Talent and capital are important internal resources for enterprise development, but Chinese enterprises generally face the dilemma of talent and capital shortage. The promulgation of green talent policy may bring green human capital and R&D funds to enterprises, thereby increasing firms’ internal resources for green innovation. That is to say, promulgating green talent policies can promote corporate green innovation and help enterprises form unique competitive advantages. The specific analysis is as follows:
When highly qualified people are free to choose where they work, they tend to opt for cities where they can get the highest remuneration [39]. Considering this factor, the green talent policy introduced by various cities in China helps attract green talent to work locally or train green talent by providing preferential measures such as living subsidies, subsidies for purchasing (renting) housing, and so on. The increased availability of green talent in a city brought by the green talent policy creates opportunities for local enterprises to hire and utilize more green talent [40]. There is a significant positive correlation between green human capital and corporate green innovation [41-43] because green human capital can reduce the risk of green innovation investments and increase the probability of green innovation success. For example, it has been documented that CEOs with green experience are better at recognizing market opportunities arising from green innovation and thus actively coordinate internal and external resources to implement green R&D [41]. According to the above analysis, we infer that a city's green talent policy may catalyze the green innovation of local firms.
Besides, enterprises face severe financing constraints when engaging in green innovation activities [24, 44]. We believe introducing a green talent policy can ease the financing constraints for local firms on green innovation. Specifically, on the one hand, enterprises have a strong awareness of cautious disclosure of core technology information, which leads to a serious shortage of R&D information disclosure when enterprises apply for loans. On the other hand, the evaluation of enterprise R&D projects has professional requirements, and it is difficult for investors to effectively screen the quality of corporate green innovation. The information asymmetry caused by these two reasons exacerbates the financing constraints for enterprises to carry out green innovation activities [45]. Green talents are a strong guarantee for the success of green innovation [41-43]. More green talents (especially those recognized by the government) participating in green R&D is equivalent to sending a favorable signal to external capital providers; the enterprise's green innovation ability is trustworthy. After receiving this signal, investors will upgrade their ratings of green innovation and then allocate more credit funds to enterprises. With access to sufficient funds, the financing constraints of green R&D are alleviated, thus promoting local firms’ green innovation. In addition to the signaling effect, the role of green talent policy in easing financing constraints is also reflected in the fact that the tools of talent policy to attract talents include academic activity funding, international academic conference (technical exchange) funding subsidies, etc. Directly injecting these funds into enterprises is also conducive to alleviating the dilemma of insufficient funding for corporate green innovation. Based on the above analysis, this paper proposes the following research hypotheses:
H1: Green talent policy promotes green innovation in local enterprises.
According to the above analysis, the green talent policy promotes the clustering of resources, such as capital, to local enterprises, which in turn promotes local enterprises’ green innovation. The impact of increased resources is particularly significant for relatively resource-poor enterprises [46]. As a result, enterprises that lack adequate funds to invest in green innovation projects are more likely to have their level of green innovation affected by green talent policy than enterprises with sufficient funds. Green finance serves as a critical funding source for green innovation activities [47]. In areas with developed green finance, enterprises are more likely to raise sufficient funds for their green R&D. On the contrary, in areas with underdeveloped green finance, enterprises face difficulties in fundraising. In other words, enterprises in regions with underdeveloped green finance development are relatively resource-poor. Therefore, we believe that the facilitating effect of green talent policy on green innovation is more pronounced for firms in regions lagging on green finance. Based on the above analysis, we make the following hypotheses:
H2: The facilitating effect of green talent policy on green innovation is more pronounced among firms in underdeveloped green finance regions.
As previously analyzed, the green talent policy facilitates local enterprises to recruit more talent, thereby promoting local firms’ green innovation. It is particularly evident that the impact of increased resources is more pronounced in areas and enterprises where resources are relatively scarce [46]. That is to say, in enterprises with low human capital levels, the increase in talent can have a greater effect. Therefore, we believe that the promotion effect of green talent policy on green innovation is more obvious in enterprises with insufficient human capital. We propose the following hypothesis:
H3: The role of green talent policy in promoting green innovation is more pronounced in firms with insufficient human capital.
Knowledge can be disseminated cost-effectively and has significant spillovers. Knowledge spillover makes it easy for new products and technologies to be developed independently, but competitors can easily copy these. These violations of intellectual property rights compress the profits gained from independent research and development, seriously undermining the enthusiasm of talents for innovation [48]. In regions with a high degree of marketization, laws and regulations are sound, and the institutional environment is relatively well-established. This provides a strong guarantee for green talents to maintain their intellectual property rights, and in such an environment, green talents are more willing to implement green innovation activities [41, 44]. Only by incentivizing green talents to innovate can the green talent policy give full play to its role. Therefore, the contribution of green talent policy to green innovation is more obvious in highly marketized areas. On the contrary, the legal regulatory system is inadequate in less market-oriented regions, and the institutional environment is poor. Green talents in these regions are more susceptible to intellectual property infringement and have weaker incentives to research and develop green innovations [41], thus making the role of green talent policies less significant. Based on the above analysis, this paper proposes the following research hypotheses:
H4: The role of green talent policy in promoting green innovation is more pronounced in highly market-oriented areas.
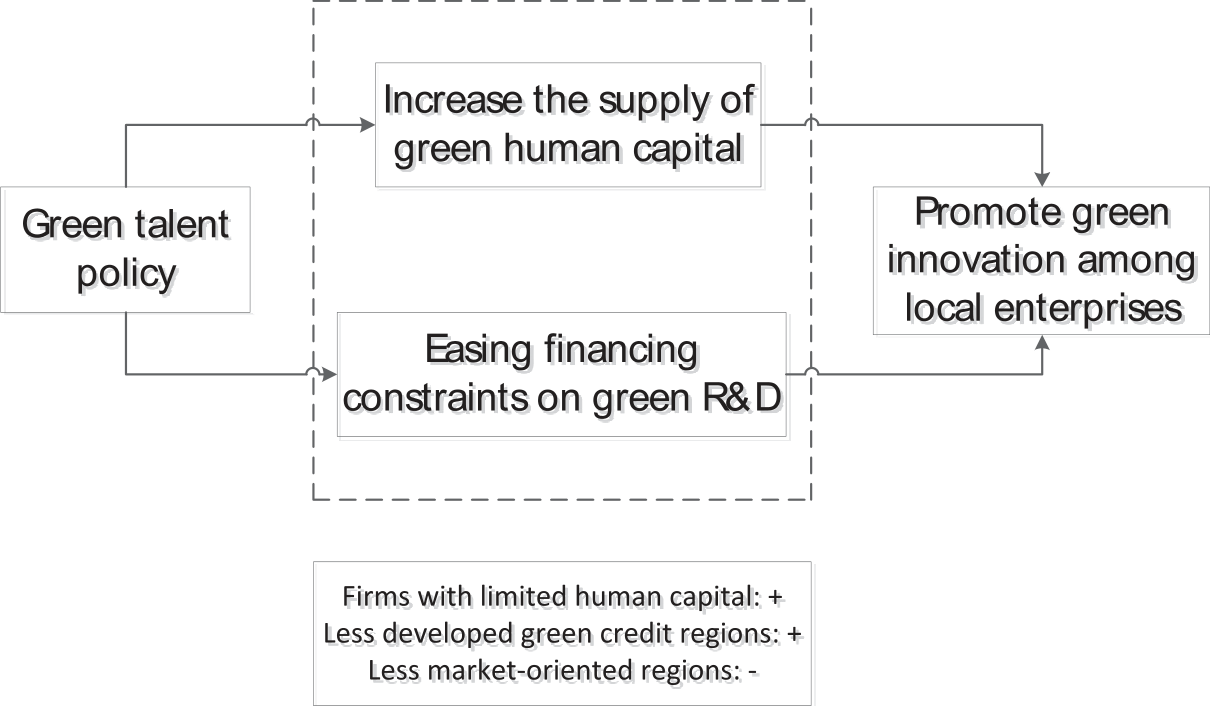
The research framework of this paper is shown in Fig. 1.
Methodology
Model Specification
Drawing on existing literature, this paper constructs the following difference-in-differences model to test research hypothesis 1:
Green(Greeni/Greenu) is the natural logarithm of one plus the number of green patent applications (green invention patent applications / green utility model patent applications). The number of green patent applications equals the sum of the number of green invention patent applications and the number of green utility model patent applications. Policy is a dummy variable equal to 1 if the city where the enterprise is located has enacted a green talent policy and 0 otherwise. Given that it takes time to enact a green talent policy to its eventual effect on green innovation, we lag all explanatory variables by one period.
The control variables are taken from prior literature that examines the factors that affect corporate green innovation[10]. Specifically, we control for firm size (Size), profitability (Roa), firm age (Age), operating cash flow ratio (Cfo), sales growth (Growth), leverage (Lev), the nature of ownership (Soe), the percentage of institutional shareholders (Ins), the percentage of the largest shareholder (Shr1), whether the two positions of general manager and chairman are combined (Dual), and board size (Board). In addition to this, we control for the firm (firmFE) and year-fixed effects (yearFE). Standard errors are clustered at the firm level. Specific definitions of the variables are presented in Table A1 of Appendix A.
Sample Selection and Data Sources
In order to ensure comparability across cities, this paper only selects the cities with more than 20 listed firms as the research subjects. After screening, our research sample finally covers 49 major cities in China, including Beijing, Kunming, Lanzhou, Guiyang, Shenyang, Harbin, Urumqi, Chongqing, Xiamen, Dalian, Changsha, Nanjing, Qingdao, and so on. These cities are located in China’s eastern, middle, and western regions. As of 2021, these cities are home to 3,488 listed companies, which account for 75.37% of the total number of A-share listed firms. Therefore, we believe that the sample in our paper is still highly representative even though it is screened. After identifying the cities that will be the subject of this study, we proceed as follows: First, we used “talent”, “talent introduction”, and “talent cultivation” as keywords to search for relevant government documents on the official website of each city; next, we searched the PKULAW database for government documents by keywords such as “talent”, “talent introduction”, “talent cultivation”, and so on. This was done to supplement the government documents that were not retrieved in the previous step. Finally, we carefully read each of the retrieved government documents and labeled those policies aimed at attracting or nurturing talents in energy saving, environmental protection, etc., as green talent policies.
This paper selects Shanghai and Shenzhen A-share listed firms registered in the above 49 cities from 2007- 2021 as the research sample. After excluding firms in the financial sector, firms subject to special treatment, and firms with missing values for key variables, the paper obtains 21,745 observations. The green innovation data used in this paper comes from the CNRDS database, and the other financial data used in this paper comes from the CSMAR database. All continuous variables are winsorized at the 1st and 99th percentiles, and standard errors are clustered at the firm level.
Empirical Results and Discussion
Descriptive Statistics
The descriptive statistics of the main variables are presented in Panel A of Table 2. The variable Green has a mean of 0.4448 and a median of 0.0000, indicating that Chinese firms are not innovative enough. In this context, it is of great practical significance to study the factors that help to enhance the green innovation level of Chinese enterprises. As for our testing variable, Policy, the mean shows that, on average, 61.67% of firm-year observations are affected by the green talent policy. With respect to the control variables, the firms in our sample have an average firm size of 22.0750, ROA of 0.0475, a logarithm of firm age of 2.7825, Cfo of 0.0442, sales growth of 0.1963, leverage of 0.4225, largest shareholder ownership of 35.36%, institutional ownership of 35.36%, and a board size of 2.1351. The statistics also indicate that 37.51% of enterprises are state-owned, and 27.62% of firms have the same chairman and general manager.
Panel B of Table 2 shows the Pearson correlation matrix. The correlation coefficient between Policy and Green is positive and significant at the 1% level. The results indicate that green talent policy increases corporate green innovation, preliminarily supporting H1 of this study. As other correlations between regression variables are below the threshold of 0.8, we believe that there is no multicollinearity problem in this study.
Regression Results
Panel A of Table 3 reports the results of fixed effects regressions without control variables. The coefficients of the variable Policy are 0.0539, 0.0445, and 0.0373, respectively, and are all statistically significant. Panel B of Table 3 shows the results of fixed effects regressions with control variables. The dependent variables are Green, Greeni, and Greenu in columns 1, 2, and 3, respectively. In column 1, the coefficient on Policy is 0.0573 and significant at the 5% level, indicating that green talent policy is positively correlated with corporate green innovation. In columns 2 and 3, the coefficients on the variable Policy are 0.0470 and 0.0394, respectively, and both are significant at the 5% level, indicating that the green talent policy improves not only the quantity but also the quality of firms' green innovations. These results support hypothesis H1 in stating that the promulgation of the green talent policy is conducive to improving the green innovation level of local enterprises.
Table 2.
Summary statistics.
Endogeneity Checks
Parallel Trend Analysis
In the previous section, we verified H1 by the difference-in-difference model. An important prerequisite for the validity of the results of the DID regression is that the sample satisfies the parallel trend assumption. In line with prior studies [49, 50], we employ the event study method to test whether the parallel trend hypothesis was satisfied in the treatment and control groups before implementing the green talent policy. Before7, Before6, Before5, Before4, Before3, Before2, and Before1 denote 7, 6, 5, 4, 3, 2, and 1 years before the implementation of the green talent policy and treatment group firms take the value of 1; otherwise, the value is 0. Current represents treatment group firms and belongs to the year when the green talent policy was implemented. After1, After2, and After3 represent the 1, 2, and 3 years after the implementation of the green talent policy, treatment group firms take the value of 1; otherwise, the value is 0. Panel A of Table 4 reports the regression results. The coefficients of Before7, Before6, Before5, Before4, Before3, Before2, and Before1 are not significant, indicating that the green innovation evolution process of the control group and the treatment group was almost the same before the green talent policy implementation. The parallel trend is satisfied.
Propensity Score Matching (PSM) Method
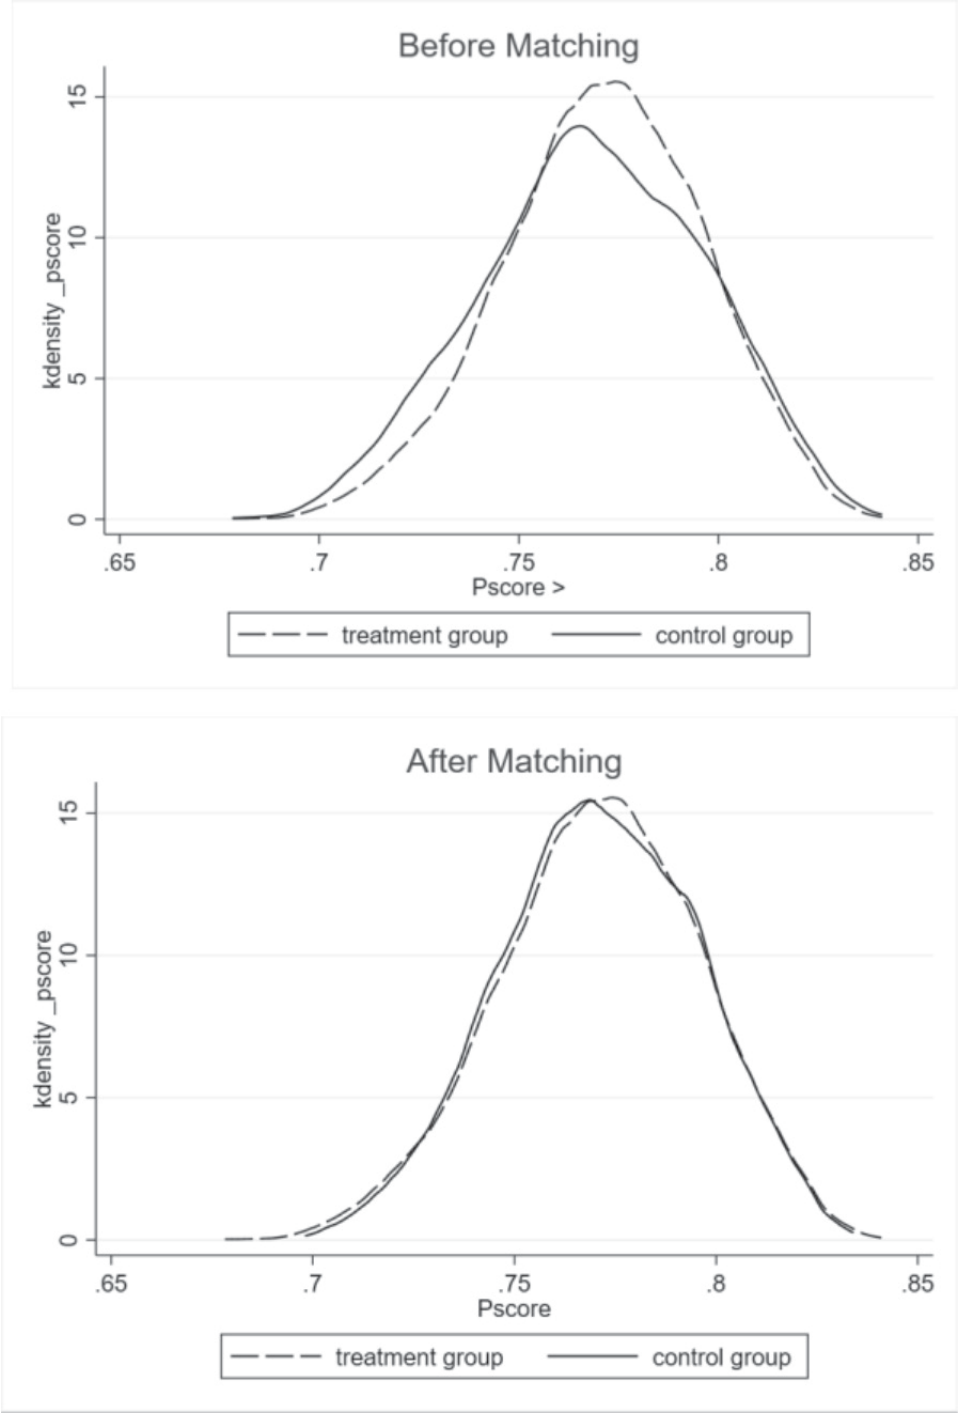
To avoid estimation bias caused by systematic differences between the treatment group (Enterprises that have been affected by green talent policy) and the control groups (Enterprises that have never been affected by green talent policy), we use the propensity score matching (PSM) method to re-test our research. Specifically, we used a logit model to regress variable Policy on control variables in Eq. (1) and estimate the propensity score of a firm to be affected by the green talent policy. Next, we match each treatment firm with 4 control firms with the closest propensity score. The caliper in selecting control group firms is 0.00001, and we perform the matching without replacement. The probability distribution of propensity score (PS) between the treatment group and the control group before and after matching is shown in Fig. 2. Fig. 2 showcases a significant disparity in the probability distribution of PS between the treatment group and the control group before matching, while the difference in the probability distribution of PS between the two groups after matching is substantially reduced. This result shows that the distribution deviation of PS of the two groups has been effectively corrected, indicating that the matching effect is ideal. We used the matched samples to regress Eq. (1) and reported the results in Panel B of Table 4. The coefficients on Policy remain positive and statistically significant at the 10% and 5% levels, suggesting that our findings are robust.
Table 3.
Regression results.
Placebo Test
Randomized Generation of Policy-Affected Observations
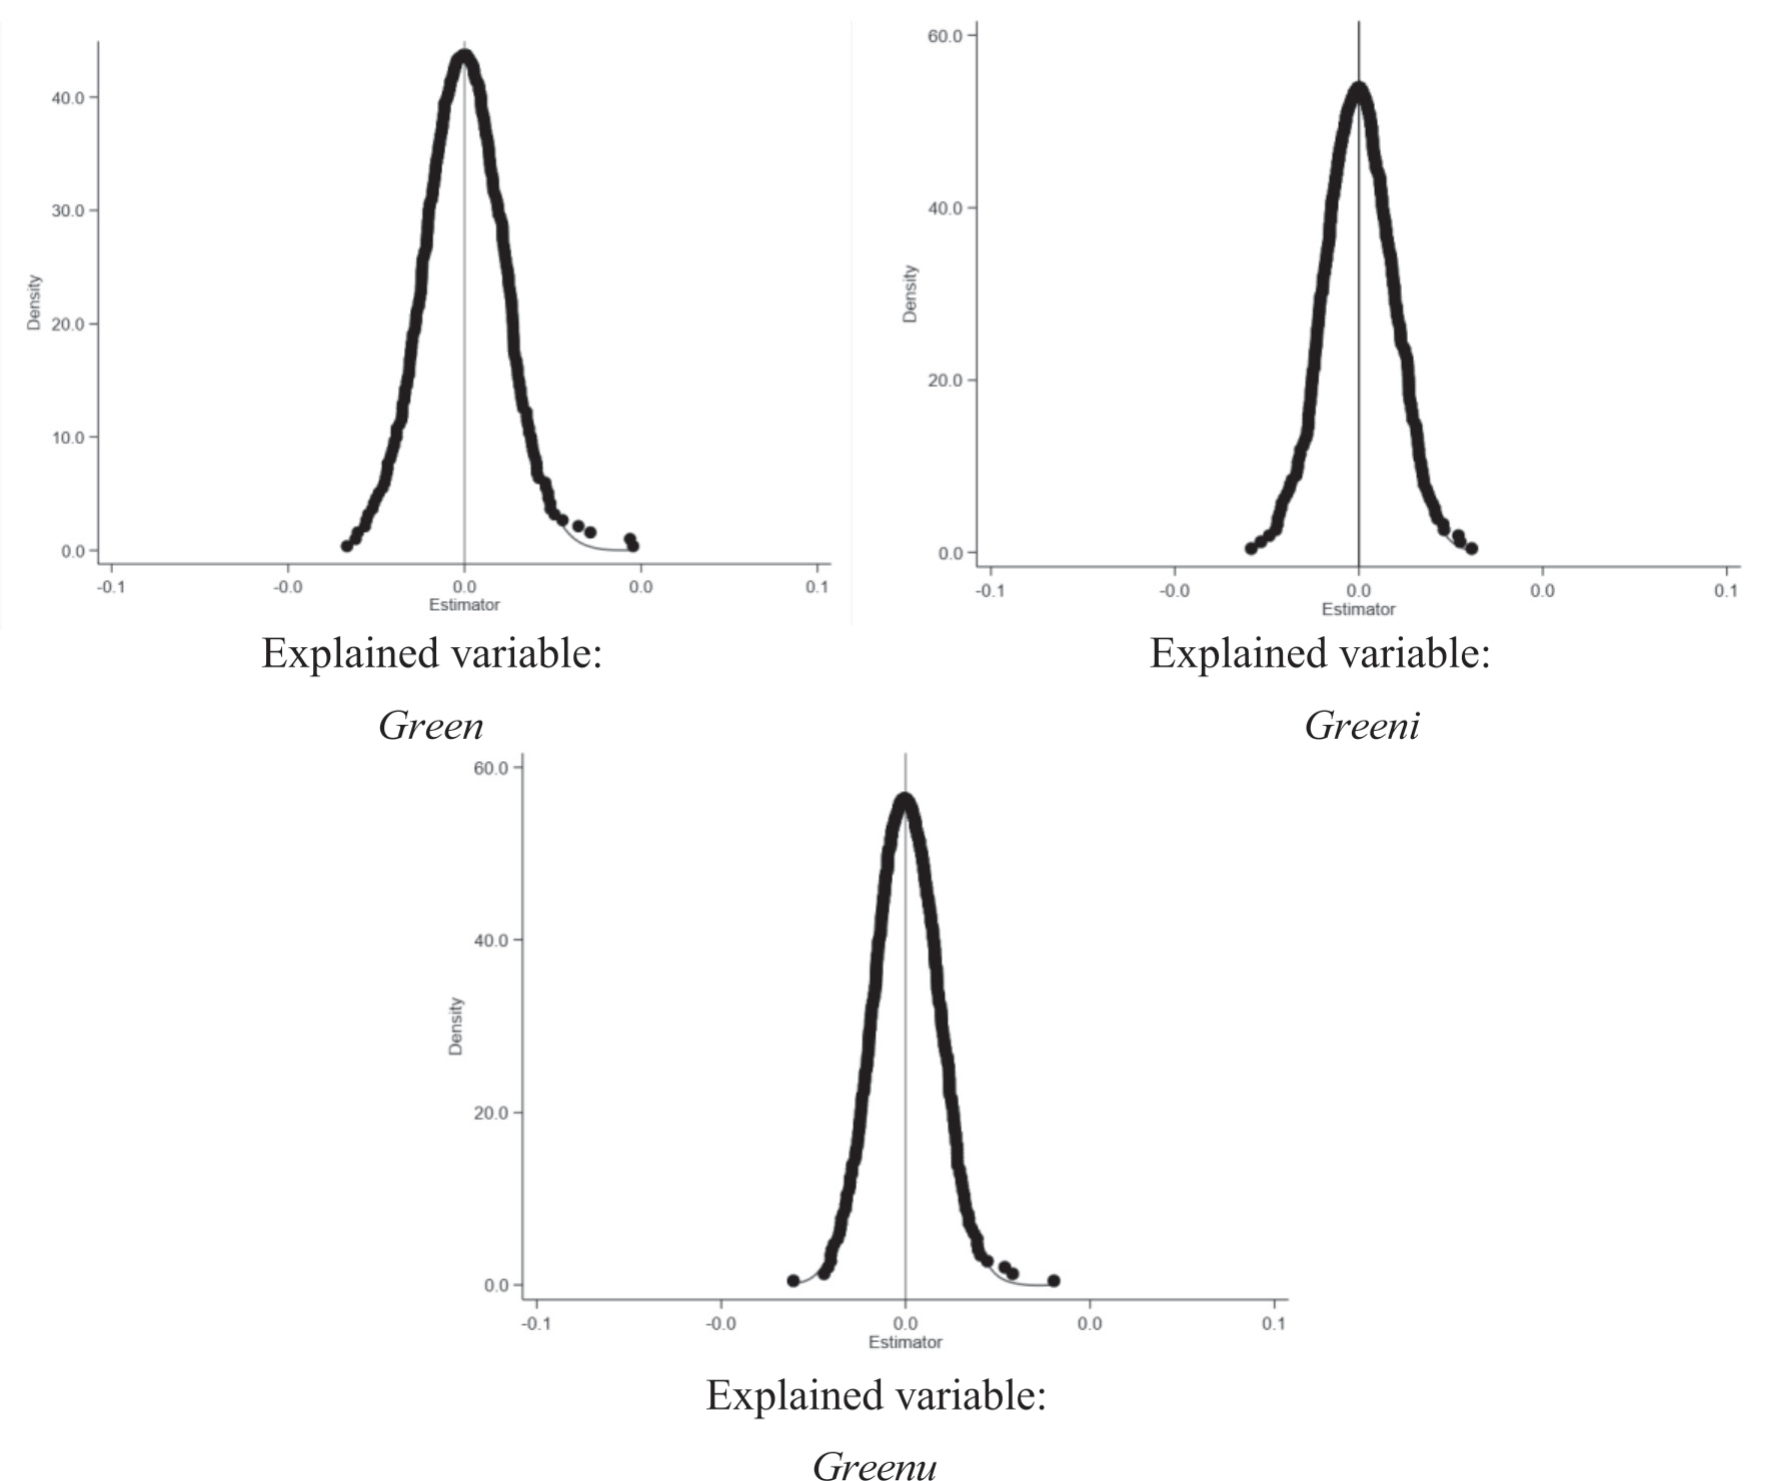
Another concern about the difference-in-difference method is the interference of other unobservable time-varying firm characteristics with the estimation results. Following prior studies [51, 52], we employ an indirect placebo test to address this issue. This approach aims to identify an erroneous variable that theoretically does not affect the results and replace the treatment variable Policy. Since this erroneous variable is randomly generated, its coefficient should be 0. If this erroneous variable actually has an effect on the results of the study, that is, its coefficient is not 0, then it proves that the conclusions of our results are erroneous. That is to say, the increase in green innovation is caused by other factors. Specifically, this paper randomly generates a list of enterprises affected by the green talent policy, resulting in an incorrect estimate ˆ randomβ . Next, the above process is repeated 500 times, resulting in 500 wrong estimators ˆ randomβ . Fig. 3 depicts the distribution of ˆ randomβ , and we find that ˆ randomβ is distributed near 0 and follows a normal distribution. This result is consistent with placebo expectations, indicating that the findings of this paper are due to the green talent policy rather than other factors.
Table 4.
Endogeneity checks.
Advance The Event-Year By 4 Years
To rule out the possibility that the increase in green innovation is caused by other factors rather than green talent policy, following Chen et al. [53], we introduce a placebo test to advance event time. We shift the event-year by 4 years before the actual event-year. Placebo_policy is an indicator variable that is Placebo_policy equal to 1 for years after the pseudo-event-year, and 0 for years before the pseudo-event-year. Then, we use the Placebo_policy variable to explore the relationship between green talent policy and green innovation. The results are reported in Panel C of Table 4. The coefficients on Placebo_policy becomes no longer significant, which implies that the increase in green innovation is indeed from the green talent policy rather than other factors.
Robustness Checks
Alternative Measures of Green Talent Policy
The generalization of our findings depends on the methodology employed to measure green talent policy and green innovation. For robustness checks, we use alternative measures of green talent policy and run the regression model again. Specifically, we use the variable Gnp to measure the strength of green talent policies across cities. Gnp is equal to ln (1+the number of effective green talent policies in the city where the enterprise is located). The results using this updated green talent policy variable as the independent variable are reported in Panel A of Table 5. The coefficients on variable Gnp in Columns 1 to 3 are all significantly positive, which means our findings continue to hold even after substituting the explanatory variables.
Alternative Measure of Green Innovation
Compared with the number of green patent applications, the number of green patents grants can better reflect the innovation quality of enterprises. Therefore, we measure green innovation using variables Sgreen (Take the natural logarithm after adding 1 to the number of green patents granted), Sgreeni (Take the natural logarithm after adding 1 to the number of green invention patents granted), and Sgreenu (Take the natural logarithm after adding 1 to the number of green utility model granted) respectively, and then regress the model. The regression results are shown in columns (1) to (3) of Table 5, Panel B. The coefficients on Policy in the three columns remain positive and significant at the 5% levels, indicating that our findings remain valid after using the number of green patents granted as an alternative measure of green innovation.
Include Government Disclosure Preferences as Controls
Green talent policy data are collected manually from the official websites of each city government. It is important to note that the amount of government disclosure of green talent policies may be influenced by this government's preference for information disclosure. Governments that do not value information disclosure may not publish relevant information on their official websites, even if they have issued green talent policies. Instead, they may distribute the policies to various units as paper documents. In order to exclude this potential interference from the research conclusion, we regress the model again with government disclosure preferences (GIDP) as the control variable. The calculation method for variable GIDP is to enter talent in the search engine on the government website and then take the logarithm of the total number of news that pops up. The higher the total number of news pop-ups on the government's official website, the more keen the government is on information disclosure. Panel C of Table 5 reports the regression results. The coefficients on Policy in the three columns remain positive and significant at the 5% levels, respectively. These results are consistent with our expectations.
Include The Government’s Environmental Concerns as Controls
The positive correlation between green talent policy and green innovation may potentially be influenced by the government's concern for the environment. The more environmentally conscious the government is, the more likely it is to enact green talent policies, and the more likely local firms are to develop green patents. To mitigate this problem, we include the government's environmental concerns (GEC) as controls. Specifically, (1) Extract the text content of each city's government work report; (2) Following Li [54], identify keywords related to environmental protection; (3) Search keywords in government work reports and make word frequency statistics; (4) Add the word frequency by 1 and then take the logarithm to obtain the variable GEC that represents the government's environmental concern. Panel D of Table 5 reports the regression results. The coefficients on Policy in the three columns remain positive and significant at the 5% levels, respectively.
Table 5.
Robustness check.
Use the Classic DID Model to Re-Examine the Research Hypothesis
This paper collects data on green talent policies in 49 cities. The specific time for these 49 cities to introduce their first green talent policies is as follows:
In order to increase the robustness of the research conclusion, this paper uses the information in Panel E of Table 5 to construct several classical DID models to re-test our research hypothesis. The specific steps are as follows:
First, the cities in Group 1 have never enacted a green talent policy; that is, the firms located in these areas have never been affected by a green talent policy. Therefore, we use group 1 enterprises as the control group.
Second, the cities in Group 2 have issued green talent policies and then canceled them. It is difficult for us to determine whether the firms located in Group 2 cities belong to the treatment group or the control group. Therefore, we removed the firms in Group 2 cities from the sample.
Third, cities in Group 3 enacted their first green talent policies before 2007. Our sample starts in 2007; that is, during the sample period, all observations in Group 3 were affected by the green talent policy, and there was a lack of observations before the policy for comparison (lack of observations with Postt = 0). Therefore, we removed firms located in Group 3 cities.
Fourth, the cities in Group 4 all issued their first green talent policies in 2009. We took group 4 as the treatment group and group 1 as the control group to construct the classical DID model for the robustness test. If enterprise i is located in the city of group 4, the value of Tratt is 1. If enterprise i is located in the city of group 1, the value of Tratt is 0. If the year t is 2009 or later, the value of Postt is 1. If the year t is before 2009, the value of Postt is 0. The regression results are shown in the first column of Panel F in Table 5, where the coefficient of the interaction term Tratt × Postt is significantly positive, indicating that green talent policies help improve the green innovation level of local enterprises.
Fifth, the cities in Group 5 all issued their first green talent policies in 2010. We took Group 5 as the treatment group and Group 1 as the control group to construct the classical DID model for the robustness test. If enterprise i is located in the city of Group 5, the value of Tratt is 1. If enterprise i is located in the city of Group 1, the value of Tratt is 0. If the year t is 2010 or later, the value of Postt is 1. If the year t is before 2010, the value of Postt is 0. The regression results are shown in the second column of Panel F in Table 5, where the coefficient of the interaction term Tratt × Postt is significantly positive, further supporting the research hypothesis of this paper.
Sixth, the cities in Group 6 all issued their first green talent policies in 2011. We took Group 6 as the treatment group and group 1 as the control group to construct the classical DID model for the robustness test. If enterprise i is located in the city of group 6, the value of Tratt is 1. If enterprise i is located in the city of group 1, the value of Tratt is 0. If the year t is 2011 or later, the value of Postt is 1. If the year t is before 2011, the value of Postt is 0. The regression results are shown in the third column of Panel F in Table 5. The coefficient on variable Tratt × Postt is significantly positive, which still supports the research conclusion of this paper.
Seventh, the cities in Group 7 all issued their first green talent policies in 2013. We took group 7 as the treatment group and group 1 as the control group to construct the classical DID model for the robustness test. If enterprise i is located in the city of group 7, the value of Tratt is 1. If enterprise i is located in the city of group 1, the value of Tratt is 0. If the year t is 2013 or later, the value of Postt is 1. If the year t is before 2013, the value of Postt is 0. The regression results are shown in the fourth column of Panel F in Table 5. The coefficient on variable ratt × Postt is significantly positive, which still supports the research conclusion of this paper.
Eighth, among the 8-13 groups, only one or two cities issued green talent policies that year. If we use firms located in these cities as treatment groups, the number of firms in the treatment group is too small. Therefore, we do not use these cities to construct the classic DID model.
When the above regression is carried out, the enterprises whose registration place has changed are deleted. The regression results for the variable Tratt are omitted because of the multicollinearity problem. The results obtained by using the classical DID model still support hypothesis H1.
Additional Analysis
Potential Mechanisms Analysis
In this subsection, we examine two potential mechanisms through which green talent policy positively affects firm green innovation: enhanced green human capital and alleviated financing constraints.
Enhanced green human capital. One mechanism discussed in the research hypotheses section is “enhanced green human capital”. We hypothesize that a green talent policy prompts local firms to recruit more green talents, thereby enhancing their capacity for green innovation. We test this mechanism by examining whether firms affected by the green talent policy are more likely to hire executives with green experience or recruit R&D employees in energy conservation and emission reduction.
The dependent variable in the first column of Panel A of Table 6 is GreenCEO, which equals 1 if the CEO of a firm has green experience and 0 otherwise. Following Lu and Jiang [41], we manually identified executives with green-related education or jobs from executive biographical data3. Executives with green experience are more environmentally conscious and contribute to greater levels of green innovation [41-43]. Therefore, prior studies view CEOs with green experience as critical green talents, and we adopt this perspective in our research design. We use a logit model to run the regression4. The coefficient on Policy is 0.3021 and significant at the 5% level. Consistent with our prediction, we find that firms impacted by green talent policies are better able to obtain CEOs with green experience.
The dependent variable in column 2 of Panel A of Table 6 is GreenRecruit, which represents the number of green R&D personnel each enterprise wants to recruit, as stated in their recruitment information. Here, green R&D personnel mainly refers to technical personnel who can contribute to energy conservation and emission reduction. Specifically, (1) This paper enters the name of each enterprise into the 51job recruitment website;
(2) This paper reads the recruitment information of various enterprises and calculates the total number of green R&D personnel each enterprise wants to recruit each year. Suppose a firm indicates in its recruitment information that it wants to recruit R&D personnel with a background in energy conservation and emission reduction. In that case, we consider that the firm wants to recruit green R&D personnel. (3) This paper takes ln(1+ the total number of green R&D personnel each company wants to hire each year *1000) as the dependent variable GreenRecruit. The regression results indicate that if the region where the enterprise is located has implemented green talent policies, it will recruit more green R&D personnel in its recruitment information. This phenomenon may be because the green talent policy has reduced the cost of hiring green R&D personnel for enterprises, so enterprises have published more recruitment information for green R&D personnel.
Alleviated financing constraints. Another mechanism analyzed in the hypothesis development section of our study is "alleviated financing constraints". We refer to Hadlock and Pierce [55] to test this prediction, using the SA index as a proxy for financing constraints. The larger the SA index is, the more severe the firms’ financing constraints are [55]. We expect that the green talent policy issued by various cities can alleviate the financing constraints of local enterprises. If that is the case, one might expect a negative effect of green talent policy on SA index. Panel B of Table 6 reports the results. As expected, the coefficient on Policy is negative and significant at the 1% level. This suggests that compared with enterprises not affected by green talent policy, those affected by green talent policy have eased their financing constraints.
Moderating Effect Analysis
In this subsection, we investigate the influence of moderators on the relationship between green talent policy and green innovation.
We first examine how green finance affects the association between the two (H2). We measure green finance by the ratio of total urban environmental project credit to total urban credit. If the green credit of enterprise i in year t is lower than the sample median, the value of Lowgf is 1; otherwise, the value is 0. Panel A of Table 7 reports the results. We find a significantly positive coefficient on Policy × Lowgf, suggesting that the positive effect of green talent policy is reinforced when the firm is in an underdeveloped green finance region, which is consistent with H2.
Table 6.
Potential mechanisms.
In the subsequent analysis, we examine how human capital moderates the association between green talent policy and green innovation (H3). We anticipate that the association is more pronounced in firms with insufficient human capital. There is a consensus that education contributes to the accumulation of human capital. Thus, the existing literature mostly uses years of schooling as the measurement index of human capital level [56]. Following this convention, we refer to Ji and Yang [57] and use the ratio of employees with bachelor's degrees or above as an indicator to measure corporate human capital. If this ratio is lower than the sample median, variable Lowedu is 1, indicating insufficient human capital within the firm. Panel B of Table 7 reports the results. Consistent with H3, we find the coefficient on Policy × Lowedu to be positive and statistically significant, indicating that the promotion effect of green talent policy is more obvious in enterprises that lack adequate human capital resources.
Table 7.
Moderating effect.
Finally, we examine how the degree of marketization affects the association between green talent policy and firm green innovation (H4). Following Ma et al. [58], we use Fan Gang's marketization index to measure the degree of marketization. If the marketization index5 of the enterprise's location in the current year is greater than the median of the sample, then Highmarket is taken as 1, otherwise Highmarket is taken as 0. Panel C of Table 7 reports the results of this analysis. Consistent with H4, the coefficient on Policy × Highmarket is positive and statistically significant at the 5% levels. In general, the results show that the promoting effect of green talent policy on green innovation is more pronounced in regions with a higher marketization degree. H4 is supported.
Conclusions and Policy Implications
Conclusion
We examine the impact of green talent policies on corporate green innovation. (1) We employ a sample of Chinese A-share listed firms spanning from 2007 to 2021 and hand-collected green talent policy data. Our findings reveal a positive correlation between green talent policy and green innovation, suggesting that green talent policies are more likely to promote enterprise green innovation. (2) This conclusion stands up to a series of tests, including alternative measures of green talent policy and green innovation, placebo tests, the Propensity Score Matching (PSM) method, and parallel trends analysis. (3) Heterogeneity analysis shows that enterprises located in higher marketization areas, green credit less developed areas, and enterprises with insufficient human capital exhibit a stronger sensitivity to the green talent policy.
(4) Mechanism analysis sheds light on the fact that green talent policy can enhance green innovation within local enterprises by improving their green human capital and easing their financing constraints. 5 The data comes from the China Marketization Index Report
by Province (2021), in which the marketization index is only
updated until 2019. With reference to Ma et al. (2015), this
paper takes the average growth rate of the marketization
index over the past years as the basis for predicting the
marketization index in 2020-2021.
Policy Implications
First, Chinese enterprises often face the dilemma of insufficient talent and funds in the process of green innovation. The conclusion of this paper shows that a green talent policy can alleviate the above problems. Therefore, this paper believes local governments should continue implementing green talent policies. Specifically, on the one hand, the government should attract and cultivate green talents by providing more incentives; on the other hand, the government should vigorously publicize the contribution of green talents to green innovation. Doing so can strengthen the signal function of green talent policy and help enterprises obtain more external financing.
This paper finds that the promotion effect of green talent policy on enterprise green innovation is more obvious in areas with insufficient human capital and underdeveloped green credit. Therefore, the green talent policy should be tilted towards these regions, that is, to give more financial support to green talents who are willing to work in these regions.
This paper finds that the promotion effect of green talent policy on green innovation is weakened in regions with low marketization degrees. This is because regions with low marketization have weaker intellectual property protection. In view of this, this paper believes that the government should strengthen intellectual property protection. Doing so can stimulate green talent research and development enthusiasm, thereby improving the efficiency of green talent policies.
Shortcomings
Green R&D personnel mainly refers to technical personnel who can contribute to energy conservation and emission reduction. This paper hopes to examine whether enterprises in areas with green talent policies will actually hire more green R&D personnel. However, obtaining data on enterprises’ actual employment of green R&D personnel is difficult. In view of this, this paper examines whether firms affected by green talent policies will release more recruitment information for green R&D personnel.
Appendix A
Table A1.
Variable definition.

