

Introduction
With the growing global focus on sustainable development, ESG principles have become crucial in corporate decision-making. ESG not only underscores the importance of environmental sustainability and social responsibility but also aligns with China's high-quality development objectives and advances the "dual-carbon" goal. Recent corporate governance failures, exemplified by the Luckin Coffee scandal, have amplified market concerns over Non-financial performance, urging companies to adopt more rigorous ESG management practices to foster social trust and sustain market competitiveness. The concept of ESG originates from ethical and responsible investment and was integrated into the UN Principles for Responsible Investment (PRI) framework in 2006 to offer a new approach to evaluating long-term corporate sustainability. Since the introduction of the United Nations Sustainable Development Goals (SDGs) in 2015, global ESG policies have proliferated, including the European Union's Sustainable Finance Disclosure Regulation (SFDR) and the U.S. Securities and Exchange Commission's (SEC) ESG disclosure requirements. These policies have enhanced corporate ESG transparency and established ESG investing as a prevailing trend in capital markets.
Although China's ESG framework was established later than in many developed markets, ESG investments have expanded rapidly under the influence of government policies and increasing market demand. Since 2006, China has gradually developed a structured ESG disclosure system for listed companies. Regulatory progress includes the Green Investment Guidelines issued by the China Securities Investment Funds Industry Association in 2018, the Guidelines for Public Company-Investor Relations Efforts introduced by the China Securities Regulatory Commission (CSRC) in 2022, and the Reference Indicator System for ESG Special Reporting of Listed Companies Controlled by Central Enterprises published by the State-owned Assets Supervision and Administration Commission of the State Council (SASAC) in 2023, marking the country's first official ESG disclosure framework. Although China's A-share market is still operating under a voluntary ESG reporting model, the number of ESG reports released has risen significantly, from 565 in 2011 to 1,800 in 2023, underscoring the increasing integration of ESG principles into corporate governance and capital market practices.
Although ESG performance is increasingly regarded as a significant driver of long-term firm value, scholarly debate on its precise impact persists. Supporters contend that robust ESG performance contributes to firm value by improving corporate reputation, enhancing brand loyalty, appealing to long-term investors, and mitigating financing costs [1, 2]. While ESG initiatives are widely promoted, some scholars argue that they may result in increased operational costs, adversely impacting short-term profitability and diminishing firms’ market competitiveness [3, 4]. Moreover, ESG's effect on firm value is not uniform and is influenced by industry characteristics, market conditions, and governance models [5]. The inconsistencies in empirical findings highlight the need for further research to elucidate the precise impact of ESG performance on firm value.
Despite the growing body of literature on the relationship between ESG performance and firm value, notable research gaps remain. First, the role of organizational visibility as a potential mediating mechanism has received little scholarly attention. Second, while executive incentives are expected to moderate this relationship, systematic empirical investigations are lacking. To address these limitations, this study draws on panel data from Chinese A-share listed manufacturing firms to examine the effect of ESG performance on firm value, with particular emphasis on the mediating role of organizational visibility and the moderating effect of executive incentives.
This study contributes to the literature in the following ways: First, from a signaling theory perspective, organizational visibility is introduced as a mediating variable to systematically analyze the roles of analyst attention, media attention, and institutional investor attention in the ESG performance – firm value relationship, offering a fresh theoretical lens on the ESG value effect. Second, from an internal corporate governance standpoint, executive incentives are examined as a moderating variable to assess how executive compensation and equity-based incentives influence the relationship between ESG performance and firm value, thereby extending the principal-agent theory’s application to the domain of corporate sustainability.
Literature Review
Measurement of ESG Performance and Its Influencing Factors
As ESG performance gains prominence in corporate sustainability strategies, academic research has increasingly focused on its measurement and determinants. Traditional approaches primarily rely on ESG ratings provided by major third-party agencies, including MSCI, Refinitiv, and Bloomberg [6]. Meanwhile, emerging studies have introduced text analysis methodologies to extract ESG related insights from corporate annual reports, sustainability disclosures, and media coverage, contributing to developing more sophisticated ESG scoring systems [7]. Multiple factors contribute to ESG performance, including internal governance, market dynamics, and regulatory conditions. Yasin (2025) finds that board gender diversity serves as a key driver of ESG performance, whereas earnings volatility reduces its effectiveness [8]. Similarly, Komath et al. (2025) emphasize that corporate reputation mediates the relationship between environmental performance and firm value, suggesting that ESG performance is shaped by both internal governance strategies and external market forces [9].
Measurement of Firm Value and Its Determinants
Firm value, a foundational concept in financial management and strategic decision-making, was introduced by Modigliani and Miller (1959) and remains a primary indicator of corporate market performance [10]. Traditionally, financial measures such as market capitalization, Tobin's Q, and Return on Equity (ROE) have been widely used to assess firm value [11]. However, recent studies emphasize that non-financial factors, including market competitiveness, innovation capacity, and equity structure, also play a crucial role. Wu et al. (2022) find that ESG adoption significantly enhances firm value, particularly in firms with well-established corporate governance structures [12]. Shahrun et al. (2023) highlight that corporate investments in the SDGs lead to higher market valuations, with pronounced effects in developed capital markets [13]. Additionally, Helfaya et al. (2023) demonstrate that ESG disclosure mitigates investor uncertainty, strengthens corporate governance, and subsequently boosts firm value [14]. These findings suggest that firm value is not solely determined by financial performance but is also shaped by broader market dynamics and sustainability considerations.
Relationship between ESG Performance and Firm Value
The debate over the effect of ESG performance on firm value remains unresolved within academic discourse. One school of thought posits that ESG initiatives enhance firm value by improving corporate reputation and investor confidence [15, 16]. Conversely, critics argue that ESG investments contribute to rising operational costs, thereby negatively impacting firm value [17]. Furthermore, Shangguan et al. (2024) propose an inverted U-shaped relationship, suggesting that while moderate ESG investment yields positive returns, excessive ESG spending leads to diminishing benefits and potential resource misallocation [18].
Although the exact nature of the relationship between ESG performance and firm value remains a subject of academic debate, extensive research suggests that ESG engagement enhances firm value through various mechanisms. One key advantage is lower financing costs, as firms with strong ESG performance are often perceived by financial institutions and investors as more resilient and sustainable, increasing their access to cost-effective capital [12]. Another is that ESG performance is a key determinant of market competitiveness. Companies that actively implement ESG strategies not only enhance their brand reputation but also foster consumer trust and loyalty, thereby increasing profitability [19]. As societal expectations for corporate responsibility grow, both consumers and supply chain stakeholders increasingly prioritize engagement with firms demonstrating strong ESG commitments, reinforcing their market position. Furthermore, integrating ESG governance structures improves managerial efficiency, lowers agency costs, and enhances internal control mechanisms, leading to overall operational improvements. Importantly, in an era of evolving regulatory frameworks, firms with high ESG performance demonstrate superior adaptability to policy shifts, effectively mitigating legal compliance risks and promoting long-term corporate sustainability.
Despite extensive research on ESG performance and its implications for firm value, notable gaps remain. First, existing studies have predominantly examined financing constraints as a mediating factor, with insufficient attention paid to the role of organizational visibility in this context. Despite growing research on ESG performance and firm value, there remains a lack of systematic studies on how executive incentives moderate this relationship. The key contributions of this study include: (1) A comprehensive analysis of the role of organizational visibility in mediating the impact of ESG performance on firm value.
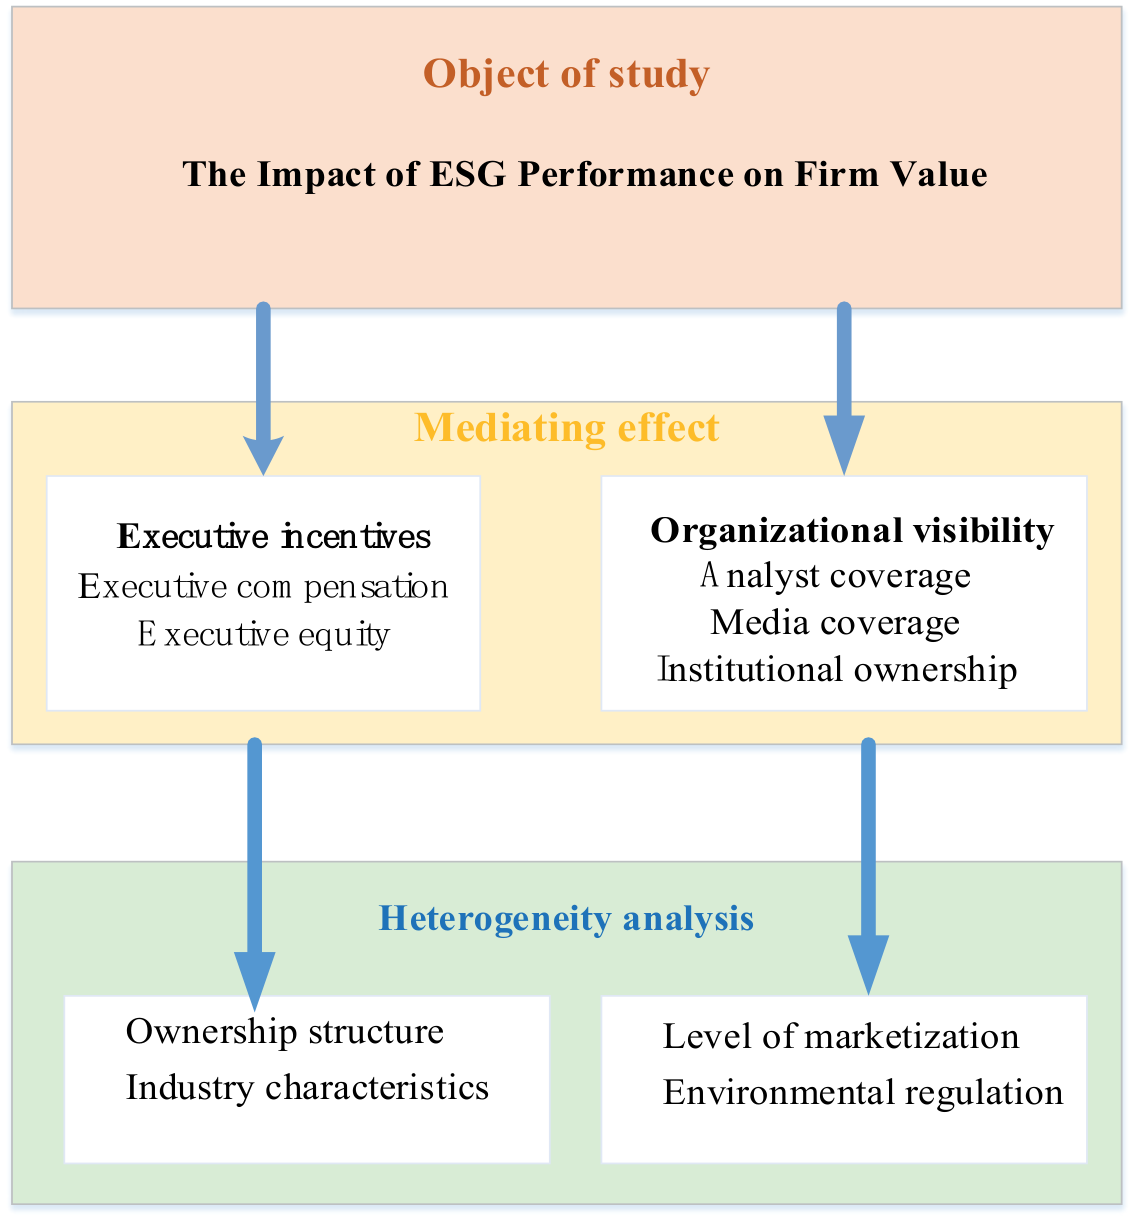
(2) Investigate the heterogeneous effects of ownership structure, industry characteristics, marketization level, and environmental regulations on the relationship between ESG performance and firm value. Through these contributions, this study aims to provide stronger empirical support for research on ESG performance and firm value.
Theoretical Analysis and Research Hypothesis
The Direct Impact of ESG Performance on Firm Value
As an extension of Corporate Social Responsibility (CSR) and Socially Responsible Investment (SRI), ESG represents a broader, more integrated approach to corporate responsibility. However, its influence on firm value remains the subject of ongoing debate. Shareholder primacy theory argues that the fundamental objective of a firm is to maximize shareholder wealth, implying that ESG investments may lead to inefficient resource allocation and reduce shareholder returns [20]. Conversely, stakeholder theory emphasizes a multi-stakeholder approach, advocating that firms should balance the interests of various stakeholders to achieve long-term stability and sustainability [21].
Stakeholder theory suggests that firms excelling in ESG performance garner positive recognition from governments, consumers, employees, and investors, contributing to firm value enhancement. Notably, government and public endorsement help firms mitigate litigation risks, counteract negative public sentiment, secure policy advantages, and obtain government subsidies, reinforcing market competitiveness and driving sustainable firm growth [22]. Second, as sustainability becomes a key determinant of consumer preferences, firms with outstanding ESG performance are more likely to capture the attention of environmentally conscious consumers. This competitive edge enables firms to expand their market presence, enhance operating profits, and ultimately improve financial performance [23]. Furthermore, employee buy-in is crucial for organizational stability. Effective ESG practices cultivate a positive corporate culture, strengthen employees’ sense of belonging, and reduce turnover, thereby ensuring sustained business operations [24]. Finally, investor attention to ESG underscores its significance. Firms with strong ESG performance typically exhibit sound corporate governance and robust risk management, making them attractive to long-term investors [25]. Institutional investors prefer firms with sustainable growth potential, whereas companies that neglect ESG and prioritize short-term profits may face selling pressure from investors [26]. Based on this, Hypothesis H1 states that ESG performance has a significant positive impact on firm value.
Mechanisms of ESG Performance on Firm Value
According to signaling theory, a company's ESG performance conveys to the market its commitment to environmental, social, and corporate governance responsibilities, thereby enhancing organizational visibility. This signal strengthens corporate reputation, fosters consumer trust, attracts capital market attention, improves financing conditions, and ultimately enhances firm value. On the one hand, greater organizational visibility reduces information asymmetry, enabling investors to assess firms’ profitability more accurately [27]. Additionally, increased visibility helps optimize capital structure and lower financing costs [28, 29]. On the other hand, external stakeholder monitoring mitigates managerial opportunism, strengthens corporate governance, improves transparency, and enhances investor confidence [30]. Thus, ESG performance not only boosts organizational visibility but also contributes to firm value by reinforcing external oversight and improving resource accessibility.
1. ESG performance promotes firm value through increased analyst attention
As ESG concerns gain prominence, analysts are increasingly focusing on corporate ESG performance. Greater transparency in ESG disclosure facilitates access to accurate and reliable information, reduces information-gathering costs, and enhances the accuracy of earnings forecasts. Increased analyst attention strengthens firm value through external monitoring and market signaling effects. On the one hand, continuous analyst scrutiny of management behavior helps curb short-term decision-making, lower agency costs, and encourage firms to adopt long-term sustainable growth strategies. On the other hand, analyst reports significantly influence investor decision-making. Positive assessments of ESG-performing firms enhance market recognition, drive stock price appreciation, and ultimately increase firm value. Consequently, companies with strong ESG performance attract greater analyst attention, reinforcing their external monitoring and market-guiding effects, further enhancing firm value.
2. ESG performance promotes firm value through increased media attention
The media serves as a key channel for the public to access corporate information, with ESG issues increasingly becoming a focal point in financial media coverage. Companies with strong ESG performance are more likely to gain media exposure, amplifying their social influence and enhancing their market reputation. Media scrutiny plays a crucial role in shaping firm value. On the one hand, media coverage strengthens a firm’s socially responsible image, enhancing brand value and providing a competitive advantage [31]. On the other hand, frequent media coverage enhances a company's visibility in the capital market, strengthens investor confidence, and improves stock liquidity. Additionally, media scrutiny incentivizes firms to optimize governance structures and maintain regulatory compliance, thereby mitigating legal and policy risks. Thus, by attracting media attention through strong ESG performance, companies can expand their capital market influence, enhance long-term stability, and drive firm value growth.
3. ESG performance promotes firm value through increased institutional investor attention
Institutional investors play a crucial role in capital markets, with their investment decisions increasingly influenced by ESG factors. Firms with strong ESG performance are more attractive to institutional investors. On the one hand, proactive ESG disclosure enhances market transparency, allowing for a more accurate assessment of a company's financial health and future profitability, thereby attracting sustained institutional investment. On the other hand, institutional investors favor low-risk and sustainable firms, making their long-term investment in ESG-performing companies instrumental in strengthening capital stability, reducing stock price volatility, and promoting a management focus on long-term strategic planning [32]. Additionally, institutional investors can influence firms through shareholder activism, improving corporate governance structures and transparency, thereby enhancing firm value [33].
Based on this, the following hypothesis is proposed:
H2a: ESG performance can contribute to firm value enhancement through increased analyst attention.
H2b: ESG performance can promote firm value through increased media attention.
H2c: ESG performance can promote firm value enhancement by increasing institutional investor attention.
Moderating Effects of Executive Incentives
Executive compensation incentives are crucial in determining the impact of ESG performance on firm value. Since ESG investments involve long-term uncertainties and potential risks, they may reduce the intrinsic motivation for corporate ESG engagement [34]. When executive compensation incentives are high, executives are more likely to optimize ESG cost management to maximize their compensation, as it is typically tied to corporate performance. Additionally, compensation incentives serve as a safeguard against ESG-related decision-making risks, helping curb short-term opportunistic behavior during ESG implementation. A performance-based compensation system not only aligns executive and shareholder interests but also enhances operational efficiency and reduces costs. Therefore, a well-structured incentive mechanism can guide executives in balancing risk and return in ESG investments, ultimately strengthening the positive impact of ESG performance on firm value.
Executive equity incentives also play a crucial role in shaping the impact of ESG performance on firm value. Unlike compensation incentives, equity incentives are more long-term oriented. Executives with higher equity incentives receive greater residual claims on corporate earnings, making them more invested in the firm’s long-term value. Equity incentives directly tie executives’ personal earnings to the firm’s long-term profitability [35], encouraging a long-term strategic approach that aligns their interests with sustainable firm development. This mechanism not only aligns executives’ decision-making with stakeholder expectations but also enhances corporate responsiveness to ESG-driven sustainable development strategies, ultimately maximizing the long-term market value of ESG performance. Furthermore, executive equity incentives help mitigate agency problems and executives’ risk aversion in ESG investments, fostering a sense of “ownership” and an “entrepreneurial” mindset. This, in turn, strengthens the positive impact of ESG performance on firm value.
Based on this, the hypothesis is formulated:
H3a: Executive compensation incentives boost the enhancement effect of ESG performance on firm value.
H3b: Executive equity incentives boost the enhancement effect of ESG performance on firm value.
The above analysis forms the theoretical framework of this study, as shown in Fig. 1.
Materials and Methods
Model Construction
Benchmark Regression Model Construction
To accurately assess the impact of ESG performance on firm value, this study employs econometric techniques to develop an analytical model, ensuring result validity through appropriate estimation methods. Therefore, this study compares multiple measures to determine the optimal model. First, the Ordinary Least Squares (OLS) method is employed for regression analysis. While OLS is computationally simple and yields unbiased estimates under ideal conditions, it fails to account for firm-level and time-dimension heterogeneity, potentially leading to omitted variable bias and systematic errors. Therefore, OLS methods alone are insufficient to meet the analytical requirements of this study. Second, the Random Effects (RE) model offers an alternative approach to enhance estimation efficiency, provided individual effects are uncorrelated with the explanatory variables. However, in firm-level studies, firm characteristics often correlate with explanatory variables, which can introduce bias in RE estimation and reduce result reliability. Consequently, the RE model is not the optimal choice.
In contrast, Fixed-Effects (FE) models account for correlations between explanatory variables and individual characteristics, effectively controlling for unobserved individual effects and mitigating omitted-variable bias. However, unidirectional FE models control only for individual or time effects, failing to capture dynamic effects over time, which may limit estimate accuracy. This study selects the Two-Way Fixed Effects Model (TWFE) as the final estimation method. This model accounts for both individual and time effects, enhances estimation accuracy, mitigates omitted variable bias, and effectively captures systematic temporal effects. The specific econometric model is as follows:
In Equation (1), i represents the firm and t represents the year; TQit+1 represents the firm value of the subsequent period; ESGi,t represents the ESG performance of firm i in year t; Xi,t denotes the control variable; μi represents firm fixed effects; δt represents time fixed effects; and εi,t represents the random error term. α0 represents the constant term; α2 represents the coefficients of control variables. α1 stands for the impact of ESG performance on firm value.
Mechanism Testing Model Construction
Referring to YU et al. (2023) [36], the following model is constructed to test the mechanism of ESG performance and firm value.
In Equation (2), Visibilityi,t represents the mechanism variable, which contains analyst attention, media attention, and institutional investor attention. β1 represents the effect of ESG performance on the mechanism variables, β2 represents the coefficients on the control variables. In Equation (3), γ1 represents the effect of ESG performance on firm value, γ2 represents the effect of mechanism variables on firm value, and γ3 represents the coefficients of control variables. Equation (3) reflects the relationship between the core explanatory variables, the mechanism variables, and the explained variables. The remaining variables are all consistent with the meaning of Equation (1).
Moderating Effects Model Construction
Drawing on Xiao et al. (2024) [37], the moderating effect model is constructed as shown in Equation (4).
In Equation (4), Di,t represents the moderating variables, including executive compensation incentives (Msl) and executive equity incentives (Msh). ESGi,t * Di,t represents the interaction term of the core explanatory and moderating variables. λ1 is the focus of the moderating effects examination. If λ1 is significant, it indicates that Di,t plays a moderating role in the process of ESG performance affecting firm value. All the remaining variables are consistent with the meaning of Equation (1).
Variable Selection
Explained Variables
Referring to Wong et al. (2021) [38], the study utilizes Tobin’s Q to measure firm value. Tobin’s Q not only accurately reflects a company’s long-term market performance but also synthesizes a company’s historical achievements and future earnings expectations to ensure the reliability and stability of research results. In addition, business decisions often have a time lag effect, and their impact on enterprise value may take some time to manifest. To capture this lagged effect more fully, the study uses firm value in the latter period (TQt+1) as the explanatory variable.
Core Explanatory Variables
This study uses the ESG composite score from the Bloomberg database to measure corporate ESG performance [39]. The Bloomberg ESG Scoring System is based on a scientific and rigorous index calculation methodology, covering 3 dimensions of Environment (E), Society (S), and Corporate Governance (G), and containing over 140 ESG sub-indicators to ensure the comprehensiveness and objectivity of the evaluation system. The ESG score ranges from 0-100. It is further divided into ESG composite, environmental (E), social (S), and governance (G) scores based on the level and perspective of disclosure to more accurately measure a company’s ESG performance in different areas.
Mechanism Variables
Organizational visibility reflects enterprises’ recognition and information transparency in the capital market, directly affecting investors’ decision-making and the market’s evaluation of enterprises. Drawing on Brockman et al. (2017) [40] and Hassan (2018) [41], this study uses analyst attention, media attention, and institutional investor attention to measure organizational visibility.
(1) Analyst attention (Ac): Analyst attention represents the capital market’s attention to firms, which helps to reduce information asymmetry and improve firm transparency. This study uses the number of analysts plus one to measure the natural logarithm.
(2) Media attention (Mc): Media attention reflects a company’s exposure in the news media and can influence investor expectations and market perceptions. This study uses the number of financial media reports provided by the Chinese Research Data Services Platform (CNRDS) and measures them in natural logarithms.
(3) Institutional investor attention (Ic): Institutional investors are important participants in the capital markets and are usually influenced by a firm’s ESG performance in their investment decisions. This study adopts the proportion of outstanding shares held by institutional investors to measure their attention to the enterprise.
Moderating Variables
In this study, executive incentives are selected as a moderating variable in order to explore the moderating role of short-term compensation incentives and long-term executive equity incentives in the impact of ESG performance on firm value.
(1) Executive compensation incentives (Msl), which uses the logarithm of total executive compensation to assess the strength of a firm’s short-term compensation incentives for management.
(2) Executive equity incentives (Msh), measured as the natural logarithm of the ratio of the total number of shares held by executives to the total number of shares in the company plus one, are used to measure the strength of executive equity incentives.
Control Variables
In order to avoid omitted variables affecting the accuracy of model estimation, drawing on the studies of Feng and Wu (2023) [42] and Tang et al. (2022) [43], the following control variables are selected: (1) Enterprise size (Size): Measured by the natural logarithm of total assets at the end of the year. (2) Gearing ratio (Lev): Measured by the total liabilities to total assets ratio.
(3) Cash flow ratio (Cashflow): Measured as the ratio of net cash flows from operating activities to total assets.
(4) Growth (Grow): Measured using the business revenue growth rate. (5) Proportion of independent directors (Indep): Measured using the ratio of independent directors to the total number of board members.
(6) Combination of two positions (Dual): If the same person holds the positions of chairman and general manager, the value is assigned as 1; otherwise, it is 0.
(7) Occupation of funds by major shareholders (Occupy): Measured using the ratio of the total amount of funds occupied by major shareholders in the company to total assets. (8) Listed years (ListAge): Measured using the number of years since the enterprise went public.
(9) Whether Big 4 (Big 4): Assigns a value of 1 if the business is audited by one of the Big 4 accounting firms and 0 otherwise.
Data Description and Descriptive Statistics
This study examines Chinese A-share listed manufacturing firms, utilizing panel data from 2011 to 2023 for empirical analysis. ESG performance scores are sourced from the Bloomberg database, financial data from the CSMAR database, and media attention data from the CNRDS. The sample data were carefully screened and processed to ensure data quality and the robustness of the findings: (1) Excluding samples of special treatment companies (ST and *ST) to avoid the interference of special operating conditions on the research results to ensure the representativeness and consistency of the data. (2) Removal of missing value samples: Firms with more serious missing data are removed to minimize the estimation bias that incomplete data may cause. (3) Exclusion of firms without ESG scores: As ESG performance is the core variable of this study, firms that do not provide ESG scores are excluded to ensure the integrity of the data.
(4) Handling of extreme values: To reduce the statistical bias that outliers may cause, all continuous variables are shrink-tailed at the 1% and 99% levels to reduce the impact of extreme values on the regression analysis and to improve the robustness and reliability of the estimation results.
Results and Discussion
Descriptive Statistics Analysis
Table 1 reports the descriptive statistics of the variables. The mean value of firm value (TQt+1) is 2.105, the standard deviation is 1.604, the minimum value is 0.692, and the maximum value is 22.572. This suggests a wide variation in the sample firm’s value level, with some firms having higher market valuations and others having relatively lower valuations. The ESG performance mean was 31.505, the standard deviation was 10.468, the maximum value was 9.091, and the minimum value was 76.240. This indicates significant heterogeneity in the investment and performance of different firms in ESG practices, with some firms excelling in environmental and social responsibility and corporate governance, while some firms’ ESG practices are still low.
Variable Correlation Analysis
In this study, several variables are selected, which may trigger the problem of multicollinearity if the direct correlation of the variables is high. For this purpose, the Pearson test and Variance Inflation Factor (VIF) method were used for the correlation test, and the variable correlation coefficients are shown in Table 2. The results showed that the absolute value of the correlation coefficients among the variables did not exceed 0.460, indicating no serious multicollinearity problem among the selected variables. Next, the relationship between the variables was examined using the VIF method, which showed that the maximum value of VIF was 2.28 and the minimum value was 1.01, both of which were less than 5, further confirming that the problem of multicollinearity between the variables was low. In addition, the regression results show a significant positive relationship between ESG performance and firm value, a finding that provides initial empirical support for hypothesis H1.
Table 1.
Descriptive statistics.
Benchmark Regression Results
Table 3 presents the benchmark regression results on the impact of ESG performance on firm value. In Column (1), the ESG coefficient is 0.0049 and significant at the 10% level, suggesting a positive relationship between ESG performance and firm value, even in the absence of control variables. When all control variables such as firm size, gearing ratio, and cash flow ratio are added, the results in Column (7) show that the coefficient value of ESG increases to 0.0125 and is significant at the 1% level, further confirming the positive contribution of ESG performance to firm value. This finding supports Hypothesis H1, which suggests that ESG performance contributes to firm value. The findings of this study are consistent with those of Broadstock et al. (2021) [1], who argue that ESG performance enhances firms' financial resilience and reduces systemic risk in the context of high market uncertainty, which in turn enhances firm value.
Robustness Tests
Lagged Explanatory Variable
The benchmark regression results indicate that ESG performance has a significant positive impact on firm value. However, this relationship may not be unidirectional, and growth in enterprise value may likewise affect ESG performance. Specifically, companies may increase their environmental responsibility investment, actively fulfill their social responsibility, and optimize their corporate governance level after value enhancement to improve their market reputation and investment attractiveness, improving their ESG performance. This bi-directional causality may raise potential causality issues that affect the robustness of the estimation results. In order to further verify the robustness of the impact of ESG performance on firm value, this study adopts the lagged variable method to conduct robustness tests. ESG performance is lagged by one, two, and three periods for regression analysis, and the regression results are shown in Table 4, Columns (1) to (4). The ESG coefficient value for lag one is 0.011 and is significant at the 1% level; for lag two, it is 0.009; and for lag three, it is 0.008, both of which are significant at the 5% level. This result suggests that the positive impact of ESG performance on firm value remains robust to both short-term and longer-term lagged effects, further supporting the core findings of this study.
Replacement of Explanatory Variable
CSI’s ESG rating system not only draws on mainstream international ESG evaluation frameworks, such as MSCI and Refinitiv ESG scoring standards but also fully considers China’s unique institutional environment and corporate development characteristics. The system covers all A-share listed companies. Due to its wide applicability and high data quality, it has become an important data support tool for ESG-related research and investment decisions. Based on this, this study uses the CSI ESG rating composite score (0-100) to replace the explanatory variables and re-run the regression analysis, and the results are shown in Column (5) of Table 5. The regression results show that the regression coefficient value for ESG1 is 0.006 and is significant at the 5% level. This result suggests that the positive effect of ESG performance on firm value remains even when different ESG rating criteria are used. That is, the benchmark regression results are robust.
Table 2.
Variables correlation coefficients.
Table 3.
Benchmark regression results.
Replacement Regression Model
Considering that the explained variables are non-negative truncated data, the Tobit regression model provides more robust estimates when dealing with such data, thus increasing the reliability of the conclusions. Therefore, the Tobit regression model was used to test the robustness of the results against the benchmark regression. The results are shown in Column (6) in Table 4, and the regression coefficient for ESG performance remains significant at the 5% level with an estimated value of 0.009. This result further validates the positive impact of ESG performance on firm value, suggesting the strong robustness of the benchmark regression findings.
Instrumental Variables Method
Considering the possible endogeneity problem between ESG performance and firm value, this study employs Two-Stage Least Squares (2SLS) regression using the Instrumental Variables(IV) method to mitigate the potential bias of endogeneity on the estimation results. Drawing on Francis (2013) [44], the mean ESG performance of other firms in the same province (IVESG1) and the mean ESG performance of other firms in the same industry (IVESG2) are selected as instrumental variables. Since there is a "peer effect" in ESG performance at the regional and industry levels, and the ESG performance of individual firms is often influenced by regional and industry ESG norms, IVESG1 and IVESG2 are strongly correlated and fulfill the correlation requirement of the instrumental variables. In addition, these two variables do not directly affect the value of a particular firm, which is consistent with the exogeneity assumption for instrumental variables.
Table 4.
Robustness test.
The results of instrumental variables regression are presented in Table 5. Column (1) shows the results of the first stage regression, which shows that the value of the coefficient of instrumental variables is 0.652, which is significant at the 1% level. Also, the Kleibergen-Paap rk LM statistic was 56.17, which was significant at the 1% level, indicating that the instrumental variables passed the validity test. The Cragg-Donald Wald F statistic of 83.76 is well above the threshold of 10, ruling out the weak instrumental variable problem. Column (2) shows the results of the second-stage regression, where the coefficient value for ESG is 0.165 and significant at the 1% level. This result suggests that the positive impact of ESG performance on firm value persists after controlling for endogeneity issues. That is, the benchmark regression results are more robust.
Mechanism Analysis
Analyst Attention
The results of Column (1) in Table 6 show that the coefficient of ESG is 0.010 and is significant at the 1% level. The results of Column (2) in Table 6 show that the coefficient of Analyst Concern Level (AC) is 0.451 and is significant at the 1% level, while the coefficient value of ESG is 0.008 and is significant at the 1% level. That is, ESG performance has an uplifting effect on firm value by increasing the analyst attention. This finding supports Hypothesis H2a. This suggests that companies with better ESG performance tend to attract more analyst attention and receive more accurate earnings forecasts, which boosts market confidence and ultimately increases enterprise value.
Media Attention
The results of Column (3) in Table 6 show that the coefficient value of ESG is 0.0081 and is significant at the 1% level. The results in Column (4) in Table 6 show that the coefficient value of media attention (Mc) is 0.372, which is significant at the 1% level. The coefficient value of ESG was 0.0098 and was significant at the 1% level. That is, ESG performance has an uplifting effect on firm value through increased media attention. This suggests that companies with better ESG performance have higher media exposure, which enhances corporate transparency and reduces investors’ information asymmetry and cognitive bias, thereby increasing corporate recognition in the capital market and ultimately promoting firm value. This finding supports Hypothesis H2b.
Institutional Investor Attention
As seen from the results in Column (5) in Table 6, the coefficient of ESG performance on the level of institutional investor attention is not significant. Therefore, a further Sobel test was carried out with a Z value of 5.951 and a P value of 0.000, which showed the passing of the Sobel test. The results of Column (6) in Table 6 show that the coefficient of Ic is 0.0242 and is significant at the 1% level. The coefficient of ESG was 0.0121 and was significant at the 1% level. ESG performance enhances firm value by increasing the attention of institutional investors. This suggests that companies with superior ESG performance are more likely to be favored by institutional investors and receive long-term capital support, thus increasing their firm value. This finding supports Hypothesis H2c.
Moderating Effect Analysis
Table 7 shows the moderating effects test results. Column (1) shows that the coefficient value of ESG*Msl is 0.077 and significant at the 1% level. Column (2) shows that the coefficient value of ESG*Msh is 0.008, which is significant at the 5% level. This suggests that equity and compensation incentives play a positive moderating role in the process of ESG performance-enhancing firm value. This finding supports hypotheses H3a and H3b. That is, reasonable executive compensation and equity incentives can further amplify the positive impact of ESG performance on firm value, which validates hypothesis H3. This role’s realization stems mainly from the executive incentives’ role in guiding management's decision-making behavior. Compensation incentives enhance management's focus on sustainable development strategies by linking executive income to ESG performance, which in turn promotes the tilting of corporate resources toward ESG-related projects, thereby enhancing firm value. In addition, equity incentives, as a long-term incentive, align executives' interests more closely with the long-term value of the firm, which in turn leads to a greater focus on the long-term returns of the ESG strategy rather than on short-term financial goals.
Table 6.
Mechanism test results.
Heterogeneity Analysis
Heterogeneity Analysis of Ownership Structure
The effect of ESG performance on firm value may differ based on the firm’s ownership structure. State-owned firms (SOFs) and Non-state-owned firms (Non-SOFs) exhibit significant differences in ESG strategies, governance mechanisms, and market constraints, leading to potential variations in the impact of ESG performance on firm value [45]. SOFs primarily align their ESG strategies with government policies, emphasizing compliance and social responsibility, whereas Non-SOFs adjust their ESG approaches based on market incentives and investor expectations [46]. To further examine this heterogeneous effect, the sample is categorized into SOFs and Non-SOFs firms based on the attributes of their actual controllers, followed by regression analysis. The results in Columns (1) and (2) of Table 8 indicate that the ESG coefficient for SOFS is insignificant, whereas for Non-SOFs, it is 0.018 and statistically significant at the 1% level.
The Chow test was then conducted to analyze coefficient differences between groups, yielding a P-value significant at the 1% level, confirming a significant disparity in the effect of ESG on firm value between SOFs and Non-SOFs. Specifically, ESG performance significantly enhances firm value in Non-SOFs, whereas its positive impact on SOFs remains unestablished. This variation may result from fundamental differences in ESG strategy implementation between the two types of firms. SOFs are primarily guided by policy directives and government regulations in their ESG practices, with their ESG activities driven more by compliance mandates than competitive market pressures. Therefore, while SOFs may excel in ESG disclosure and sustainability, their ability to create value through ESG initiatives may be constrained by the absence of competitive market pressures [47]. In contrast, Non-SOFs actively implement ESG strategies to strengthen market legitimacy and competitive advantage, responding to intense market competition to attract investors, build consumer trust, and gain favorable capital market feedback [48]. Additionally, stakeholders of Non-SOFs generally hold higher expectations for ESG performance, while these firms exhibit greater market adaptability and flexibility, enabling them to more effectively translate ESG efforts into long-term value growth [49]. These findings highlight the crucial role of corporate governance in shaping ESG performance while offering policymakers insights into optimizing ESG incentive mechanisms for SOFs. Specifically, it underscores the need to make SOFs’ ESG investments more market-driven to effectively enhance long-term firm value.
Heterogeneity Analysis of Industry Characteristics
Firms across industries experience varying degrees of external regulatory and market pressures, with heavily polluting industries facing stricter environmental regulations and greater market scrutiny than their Non-polluting counterparts. In a highly transparent information environment with rapid market responses, optimizing ESG disclosure allows heavily polluting firms to signal positive market intent, enhance corporate reputation, and demonstrate active engagement in green transformation and sustainable development. To examine the differential impact of industry characteristics, this study classifies firms into heavily polluting and Non-heavily polluting categories based on the Ministry of Environmental Protection’s (MEP) 2008 list of 16 heavily polluting industries and the CSRC's industry classification standards. Regression analyses were then conducted, with results presented in Columns (3) and (4) of Table 8. The results indicate that while the ESG coefficient for firms in heavily polluting industries is positive but not statistically significant, the ESG coefficient for firms in Non-heavily polluting industries is positive and significant at the 1% level.
Next, a Chow test was conducted to analyze coefficient differences between groups, yielding a P-value significant at the 1% level, confirming a disparity between firms in heavily polluting and Non-heavily polluting industries. Specifically, ESG performance does not currently exert a meaningful positive effect on firm value in heavily polluting industries, whereas in No-heavily polluting industries, it significantly promotes the increase of firm value. Even though some firms proactively improve their ESG disclosures to gain market confidence and comply with regulatory standards, the dual pressures of governmental enforcement and third-party ESG evaluations can lead to formalistic compliance, in which firms superficially enhance disclosure without truly advancing sustainable management [50, 51]. In contrast, firms in Non-heavily polluting industries face less environmental pressure and lower costs to improve their ESG performance, making it easier to translate ESG practices into competitive advantages and economic benefits, which in turn contribute to increased enterprise value.
Heterogeneity Analysis of Marketization Level
Significant regional differences exist in China’s marketization process, especially regarding resource allocation, the extent of government intervention, and competitive market pressures. The extent of regional marketization determines the complexity within which a firm operates, potentially modifying the impact ESG performance has on firm value. This study investigates such heterogeneity by defining firms from the top five regions, as ranked by the marketization index, as high-marketization firms and low-marketization firms (typically those in other regions). The results presented in Columns (5) and (6) of Table 8 show that the ESG coefficient for high-marketization firms is 0.008, significant at the 5% level, whereas for low-marketization firms, it is 0.007, significant at the 10% level.
Next, the difference in coefficients between groups after group regression was analyzed using the Chow test, and the P-value was significant at the 1% level, indicating a difference between high-marketization firms and low-marketization firms. In other words, ESG performance positively influences firm value irrespective of the marketization level. However, this positive effect is notably stronger in firms operating within highly marketized regions. This phenomenon may be attributed to the varying degrees of marketization, which significantly shape firms' operating environments. Specifically, regions with higher marketization experience greater market competition and more stringent government regulation. Thus, firms must enhance their competitiveness in response to market pressures while simultaneously complying with strict regulatory requirements to ensure stable operations. Consequently, firms have greater incentives to proactively enhance ESG performance to boost investor confidence and consumer loyalty, thereby increasing overall firm value. Furthermore, stakeholders in highly marketized regions tend to emphasize corporate ESG performance more, making ESG a crucial criterion for investors, consumers, and regulators when evaluating corporate sustainability, thus amplifying ESG's positive influence on firm value. By contrast, in less market-oriented regions, the public and the market pay relatively less attention to the ESG performance of firms, which may weaken the return on investment in ESG and thus reduce the role of ESG performance in enhancing firm value.
Table 8.
Heterogeneity analysis.
Heterogeneity Analysis of Environmental Regulation
The business activities of enterprises are not only subject to the mandatory constraints of external environmental regulations but also face widespread public concern over the fulfillment of environmental responsibility. As the concept of sustainability becomes more entrenched, companies increasingly look to ESG performance as a key strategic tool for enhancing firm value. In this study, the ratio of industrial pollution control investment completion in the secondary industry is used as a measure of the environmental regulation intensity, and the median of this indicator is used as a benchmark to divide the sample into strong and weak environmental regulation firms for heterogeneity analysis. The results are shown in Columns (7) and (8) of Table 8, where the coefficient value of ESG for high environmental regulation firms is 0.008, and for low environmental regulation firms, it is 0.009, both of which are significant at the 5% level.
Next, the Chow test was utilized to assess the differences in the coefficients between groups after group regression, and the results showed that the P-value was significant at the 10% level, indicating a significant difference between firms with strong environmental regulation and firms with weak environmental regulation. Specifically, while ESG performance is effective in increasing firm value across different levels of environmental regulation, the effect is more pronounced among firms with weak environmental regulation. This difference may be related to the different expectations of market participants and stakeholders under different environmental regulatory intensities. In regions with low environmental regulation, market participants and the public have relatively low expectations of corporate environmental responsibility fulfillment. Therefore, when companies take the initiative to implement ESG strategies, their ESG performance often exceeds market expectations, which triggers stronger market recognition and ultimately promotes firm value. In addition, in a weak environmental regulatory environment, a company's proactive strengthening of ESG performance not only enhances brand reputation and investor attractiveness but also prepares for possible tightening of environmental policies in the future to minimize compliance costs and business risks associated with policy adjustments.
Conclusions
Using panel data from Chinese manufacturing listed companies between 2011 and 2023, this study employs a TWFE model to examine the impact and underlying mechanisms of ESG performance on firm value. Additionally, it analyzes the moderating role of executive compensation and conducts a heterogeneity analysis. The key findings are as follows:
(1) The conclusion that ESG performance positively influences firm value is consistently supported across multiple robustness tests, including lagged explanatory variables, alternative measurement approaches, varying regression models, and applying an instrumental variables method. (2) ESG performance can enhance firm value by increasing analyst attention, media attention, and institutional investor attention.
(3) Executive compensation and equity incentives amplify the positive impact of ESG performance on firm value. (4) The impact of ESG performance on firm value varies across different types of firms. Regarding ownership structure, ESG performance enhances the value of Non-SOFs, whereas its effect on SOFs remains inconclusive. From an industry perspective, ESG performance significantly improves firm value in Non-heavily polluting industries but does not exhibit a positive effect in heavily polluting sectors. In terms of marketization, ESG performance benefits firms across different marketization levels, with a more pronounced effect in highly marketized regions. Regarding environmental regulation, ESG performance positively influences firm value under varying regulatory intensities, but its impact is stronger in firms subject to weaker environmental regulations.
Implications
Grounded in an in-depth analysis of the impact of ESG performance on firm value, this study proposes managerial insights designed to enhance the efficiency of ESG strategy implementation and promote long-term corporate sustainability.
First, companies must recognize ESG performance as a fundamental strategic asset rather than merely a compliance obligation or response to external demands. Viewing ESG as a strategic capital necessitates proactive engagement in environmental sustainability, social responsibility, and governance transparency beyond basic regulatory adherence. By embedding ESG principles within corporate strategy, firms can enhance their brand credibility, attract sustainability-driven investors, and establish a competitive market position. Therefore, a well-structured ESG strategy should be developed and aligned with long-term business objectives to drive sustainable value creation.
Second, companies should actively engage with external stakeholders and develop long-term communication mechanisms, with a particular emphasis on strengthening partnerships with institutional investors. Institutional investor participation not only enables companies to better align with external expectations but also fosters improvements in corporate governance and ESG performance. Additionally, firms must manage relationships with analysts, the media, and other investors by maintaining transparency through regular ESG reporting and participation in investor communication initiatives. Strengthened external communication increases the visibility of ESG efforts, enhances corporate reputation, and attracts investment, ultimately contributing to long-term firm value. Moreover, companies should leverage external feedback as a strategic resource to optimize ESG practices, refine policies, and ensure continuous advancement toward sustainable corporate growth.
Third, optimizing executive incentive structures is a critical strategy for advancing ESG performance and strengthening firm value. A well-balanced mix of short- and long-term incentives directly linked to ESG performance metrics is essential to ensure consistency between corporate sustainability objectives and overall firm value. By integrating financial compensation, benefits, and a structured pay gap system with explicit rewards and penalties, companies can reduce short-term incentive biases and reinforce long-term ESG engagement. Additionally, a higher proportion of equity-based incentives can effectively align executive interests with the company's long-term strategic vision, ensuring sustained ESG implementation. This approach enhances corporate credibility among investors and consumers while improving resilience in fluctuating market conditions, ultimately driving sustainable firm value.
Fourth, the successful implementation of ESG strategies requires companies to consider both their intrinsic organizational characteristics and the external environmental landscape to ensure long-term effectiveness and sustainability. Non-SOFs, firms in Non-heavily polluting industries, those in regions with high marketization, and businesses operating under less stringent environmental regulations should leverage their inherent flexibility, market advantages, and policy incentives to foster ESG-driven innovation and refinement. These firms, endowed with greater autonomy, can explore tailored ESG investment strategies that align with their corporate identity, seamlessly integrating ESG principles into core business functions as a key driver of value creation. Additionally, companies must evaluate the interplay between market forces and regulatory requirements when shaping ESG strategies, ensuring that external compliance obligations are harmonized with long-term sustainability goals. Through a precise analysis of external conditions and an alignment with internal strategic imperatives, businesses can develop ESG approaches that not only satisfy regulatory expectations but also serve as a catalyst for sustained competitive advantage in evolving markets.
Limitations and Future Research
This study employs panel data from manufacturing firms to investigate the impact of ESG performance on firm value, delineating the specific channels through which ESG practices contribute to corporate valuation while providing empirical evidence to guide both academic inquiry and managerial strategy. Despite its contributions, this study has certain limitations that future research can address. First, it focuses solely on Chinese manufacturing firms, leaving room for expansion into other industries such as finance, energy, and technology to explore the heterogeneous impact of ESG performance on firm value across different sectors. Additionally, the institutional environment and market maturity in which firms operate may influence the effectiveness of ESG implementation. Therefore, cross-country comparative studies could be conducted to examine how varying ESG policies, market structures, and regulatory frameworks shape the relationship between ESG performance and firm value. Such research would enhance the external validity of these findings and offer practical insights for global ESG policymaking. Second, this study does not account for the spatial spillover effects of ESG performance. That is, whether ESG initiatives influence the value of neighboring firms through competition, supply chain linkages, or market demonstration effects. Future studies could incorporate spatial econometric models to investigate these spillover effects, offering more targeted corporate and policy decision-making recommendations.
This study makes a meaningful contribution to ESG research, offering both theoretical and practical insights. For enterprises, ESG strategic planning should not only focus on internal sustainability but also leverage industry and regional synergies to drive long-term value creation. Policymakers should prioritize research on the sector-specific effectiveness of ESG policies and strengthen regional policy coordination to enhance the macroeconomic impact of ESG regulations. As ESG disclosure standards continue to improve and investment in ESG expands across various sectors and countries, future research should further develop theoretical and empirical frameworks to explore ESG's role in shaping firm value with greater depth and refinement.

