

Introduction
In recent years, the world economy has been confronted with many challenges, particularly downward economic pressures, geopolitical conflicts, and increasing climate change. These complex factors have given rise to the global issue of sustainable development, which has become the central focus of development in today’s world. In this situation, governments, corporations, and all sectors of society are gradually realizing the urgency of achieving sustainable development and are actively exploring strategies to balance environmental protection, economic growth, and social well-being. Corporate, as the main body of economic activity, has the responsibility to push society towards the goal of sustainability, which means that while pursuing profit maximization, firms also need to build a sustainable business model and actively practice ESG concepts [1-5]. In this paper, we will explore whether and how high education agglomerations improve firm ESG performance.
Chinese university town construction was implemented in Shanghai city in 1987 and has lasted until today. There are 123 cities that have constructed university towns until 2023, which is 36.8% of the 334 cities in China. Firms located in the cities that are constructing university towns could have more human capital or hire more skilled workers from higher education agglomerations, which would promote firm ESG performance.
Exploiting the Chinese university town construction as an exogenous, quasi-natural experiment, this paper explores whether and how higher education agglomeration affects the firm ESG performance with the DID method. We find that the higher education agglomeration would improve the firm ESG performance. This effect is more prominent in SOEs and high-tech firms. Additionally, the potential channels for the improvement effect in firm ESG performance are that higher education agglomerations would increase human capital and hire more skilled workers.
There are two potential contributions in this paper. Firstly, we contribute to the literature on the effect of agglomeration in high education. Although previous scholars in this field have shed light on the effects of industrial agglomeration [6-8], economic agglomeration [9-11], financial agglomeration [12], and population agglomeration [13, 14], little literature has explored the impact of high education agglomeration. This paper regards China’s university town construction as an exogenous quasi-natural experiment and explores whether and how high education agglomeration from university town construction has spillover effects on firm ESG performance, which enriches the literature on the effect of agglomeration.
Secondly, we enrich the research on the factors influencing firm ESG performance. Existing research has explored why there are differences in firm ESG performance within firms from firm characteristics, including firm size [15], firm digitization [16], corporate governance [17], CEO career concerns [18], executive compensation [19], or from firm external factors, including government environmental attention [20], environmental regulation [21, 22], local government debt pressure [23], green finance [24], financial performance shortfalls [25], digitalization transformation [26], and so on. However, rare literature investigates the factors affecting firm ESG performance from agglomeration. In contrast to the previous research, we explore the impact of high education agglomeration on firm ESG performance, especially based on the setting of China’s university town construction.
Literature Review
Institutional Background
With the rapid growth of China’s economy, the demand for high-quality talents has been increasing, prompting the Chinese government to invest more in higher education. This has led to an increase in the number of universities and, consequently, a growing demand for more educational facilities. In this context, the construction of university towns has become a necessary measure. These towns not only provide the necessary space and resources for the ever-increasing number of students and educational institutions, but also enhance the quality of education by concentrating high-quality educational resources. University towns have become important bases for promoting academic exchange, research innovation, and talent cultivation, playing a significant role in improving the national level of education and driving socio-economic development. At the same time, the construction of university towns is also a part of China’s regional development strategy. They not only promote the economic development of the region but also attract high-tech companies and research centers, forming an interaction of education, research, and industry. Additionally, the construction of university towns is closely related to the national urbanization process, helping to alleviate the pressure on space and resources in urban central areas while promoting the urbanization development of surrounding regions.
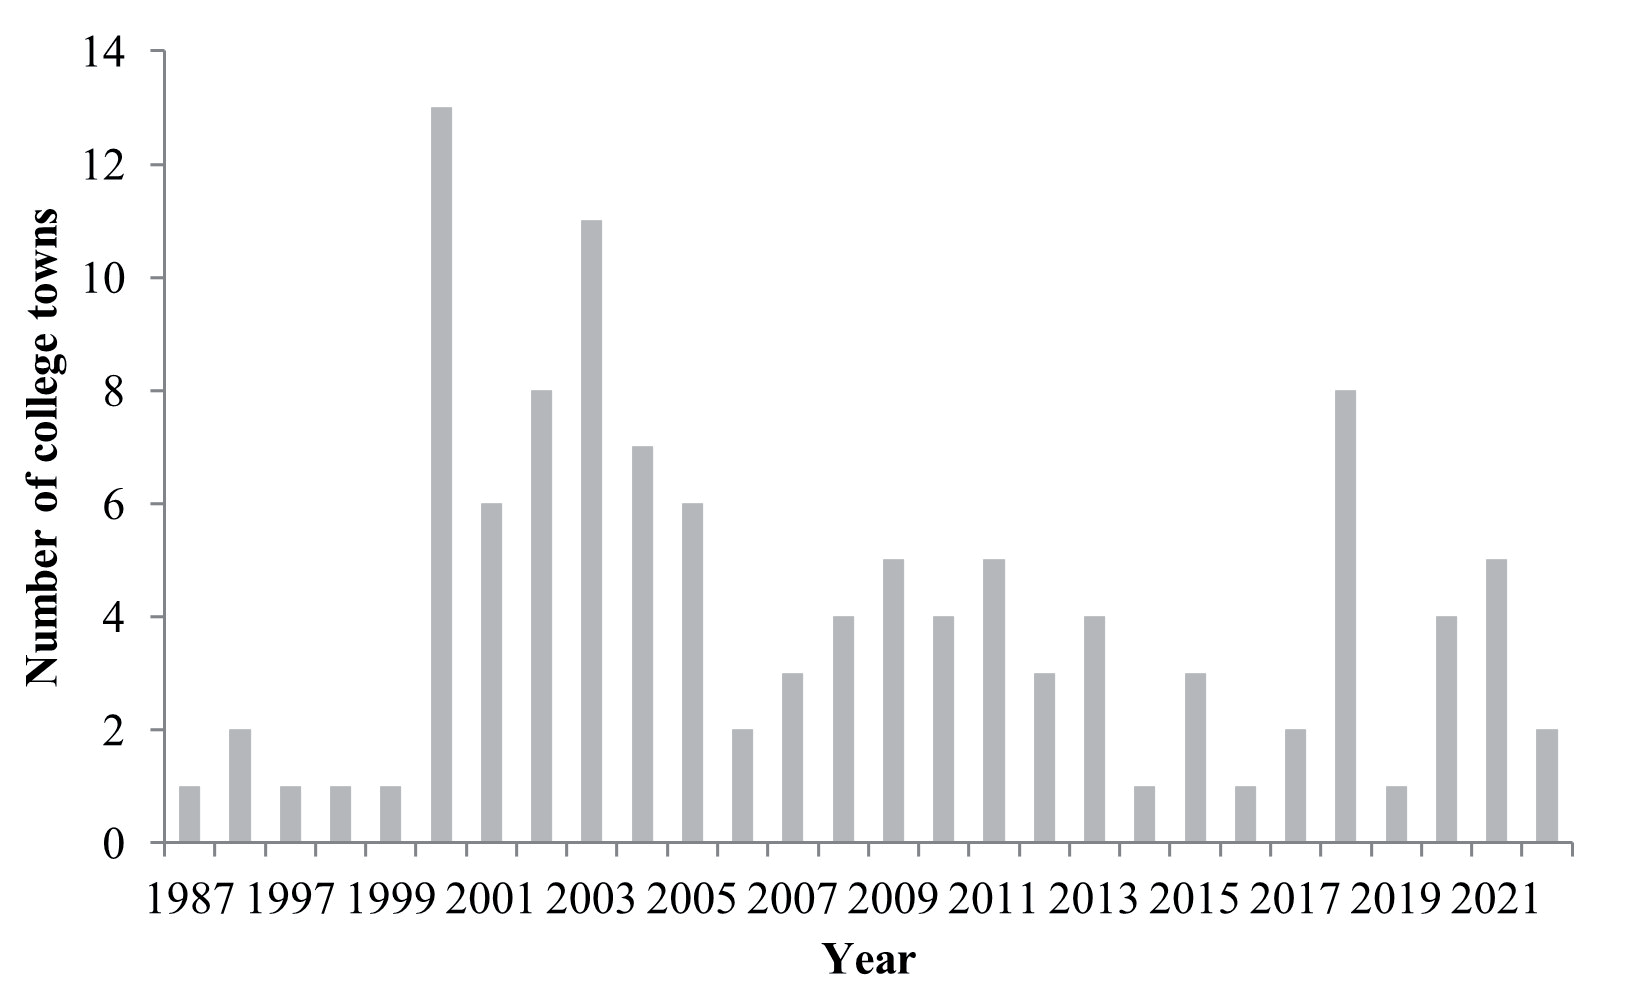
In 1999, the construction of the first “University Town” in Shanghai City marked the beginning of nationwide university town development in China. Especially under the backdrop of China’s “Better Science Education” strategy, provincial governments across China began to plan and construct university towns on a large scale. As shown in Fig. 1 from 1999 to 2022, the number of university towns completed in China increased annually. Such large-scale construction of university towns has also led to the development of higher education from a holistic to a comprehensive system.
Materials and Methods
Sample and Data
Our research sample mainly comes from three databases. First, we obtain the basic financial information of Chinese A-share listed companies from 2011 to 2021 from the CSMAR database. Second, we get the firm ESG scores from Bloomberg Corporate. Third, the city’s economic development and fiscal decentralization are based on the China City Statistical Yearbook. Referring to Ren et al. (2023) [27], we clean the sample data as follows: (1) Excluding financial and ST* companies; (2) Excluding companies with liabilities exceeding assets; (3) Excluding cities that had university town construction before 2011. Finally, our sample in this paper has 3408 firm-year observations. To minimize the impact of outliers, we performed tail-trimming on all continuous variables at the top and bottom 1%.
Variable Measurement
Independent Variable: Higher Education Agglomeration (Agglomeration)
As we have discussed the institutional background in section 2, there are some university town constructions in Chinese cities every year. Therefore, adopting the city variations and year variations, we regard the university town construction as a quasi-natural experiment to identify the impact of higher education agglomerations on firm ESG performance. Specially, we construct the agglomeration variable, which equals 1 after the city-constructed university town, to measure the human capital agglomeration.
Dependent Variable: Firm Esg Performance (LnESG)
Following Li et al. (2023), Zhang, and Lucey (2022) [28, 29], we adopt the firm ESG scores from Bloomberg Corporate to represent the firm ESG performance. Bloomberg Corporate collected the Chinese A-share listed firms ESG disclosure information from 2011 and provided a comprehensive evaluation of the corporate disclosure quality in the firm environment, social responsibility performance, and corporate governance performance, and then scored these performances. The scores range from 0 to 100. Firms are more engaged in ESG-related activities with higher scores. To exclude the effects of heteroskedasticity, this paper adopts the natural logarithmic of firms ESG scores.
The Control Variables
In this paper, the dependent variable LnESG is a firm-level variable, while the core explanatory variable Agglomeration is a city-level variable. Therefore, we included two level control variables: firm-level control variables and city-level control variables. The firm-level control variables include firm size (Size), firm leverage ratio (Lev), firm age (Age), firm earnings capacity (Roa), firm property rights (Soe), and firm concentration ownership (Top 3). The city-level control variables include city economic development (LnGDP) and city fiscal decentralization (Fiscal). Appendix Table A.1 reports the variable definitions.
Research Model
To explore the impact of higher education agglomeration from university town construction on firm ESG performance, we adopt the following DID model:
(1) Where i is the firm i, c is the city c, and t is the year t. LnESG is our dependent variable that represents firm ESG performance. Agglomeration is the independent variable that represents higher education agglomeration at UTC. Our control variables include the firm-level control variables, K, and the city-level control variables, X. δi is a firm fixed effect. In addition, we control the industry-year fixed effect (ηind,t) to exclude the impact of some industry policies on firm ESG performance and the province-year fixed effect (θp,t) to exclude the impact of some province policies on firm ESG performance.
Summary Statistics
In this section, we report our main core variables’ descriptive statistics in Table 1. The mean and standard deviation of firm ESG performance (LnESG) are 3.309 and 0.297, respectively. Additionally, the minimum value and maximum value of ESG are 2.181 and 4.243, respectively, implying that there are differences in firms ESG performance among Chinese A-share listed companies.
Table A.1.
Variables Definitions.
Table 1.
Descriptive statistics.
Results and Discussion
education agglomeration in UTC affects firm ESG
performance. Table 2 reports the basic results. From column (1) to column (4), the core dependent variable Agglomeration is positively and significantly correlated with the core independent variable LnESG. And the coefficient on the agglomeration in column (4) is 0.05, suggesting that the higher education agglomeration would significantly increase the firm ESG performance by 5.1% (=(exp(0.05)-1)×100%) on average. Therefore, this section has found that the higher education agglomeration will promote the firm ESG performance. The result is similar to the finding from Sun et al. (2021) [30], who found that education can lead CEOs to increase corporate social responsibility.
Table 2.
Basic results.
[i] Notes: *** denotes significance at 1%, ** at 5%, and * at 10%. Firm FE is firm fixed effects. Industry-Year FE is Industry-Year fixed effects. Province-Year FE is Province-Year fixed effects. City Control include city economic development (LnGDP), city fiscal decentralization (Fiscal), Firm Control include firm size (Size), firm age (Age), firm earnings capacity (Roa), firm leverage (Lev), firm equity concentration (Top3), firm property rights (Soe).
The Parallel Trend Assumption
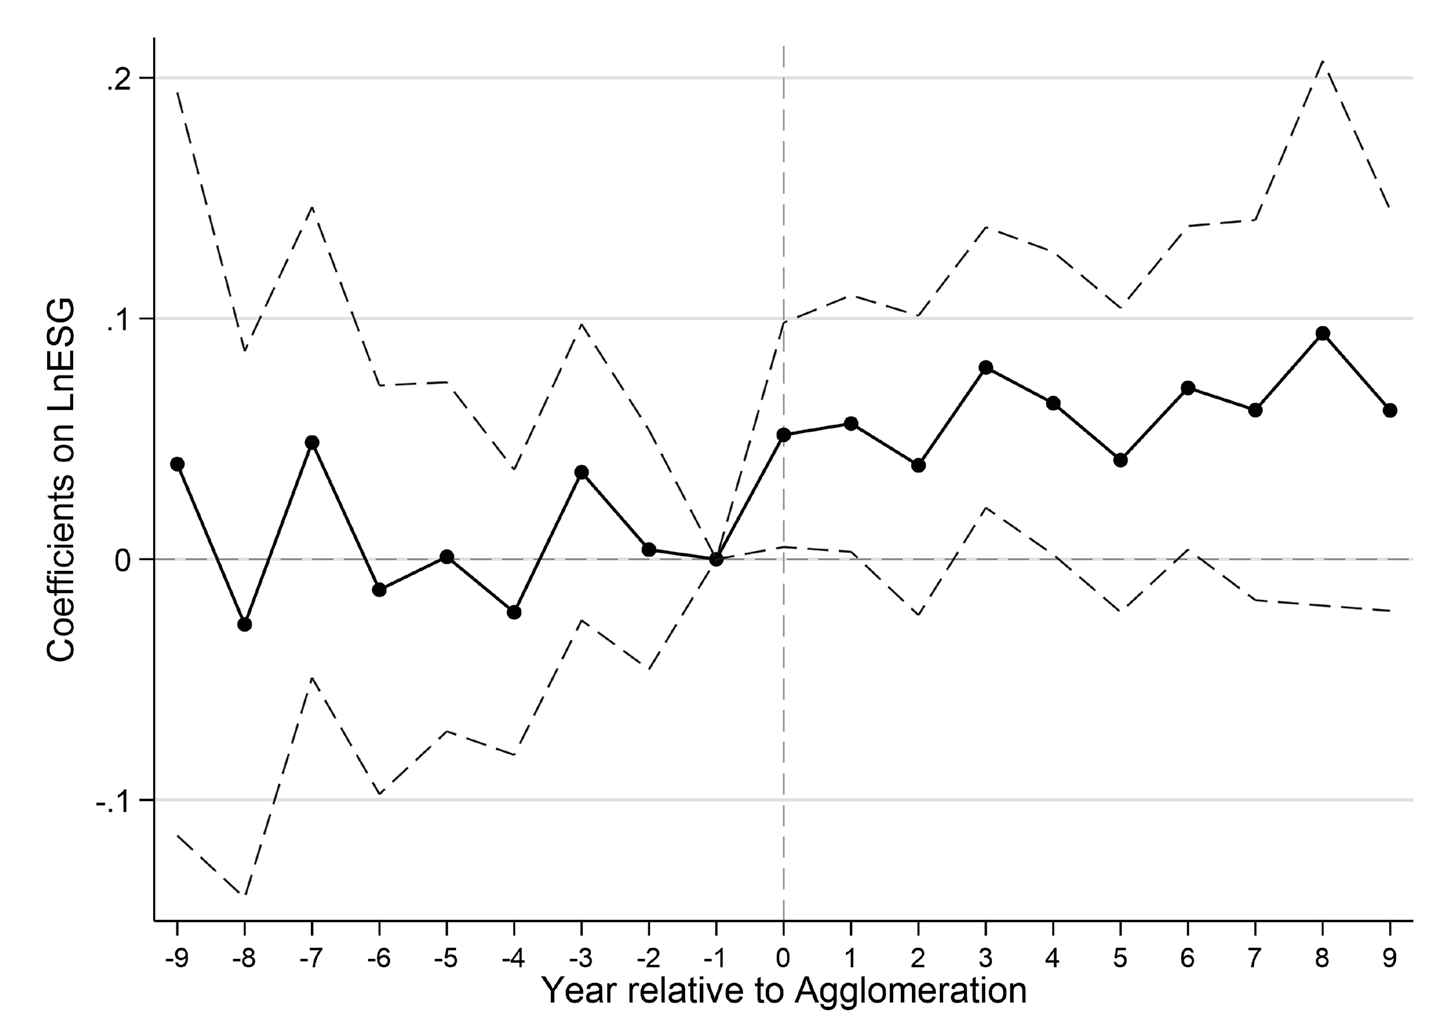
The DID method in model (1) should satisfy the parallel trend assumption. Therefore, in this section, we will follow Gutmann et al. (2023) and Xu et al. (2023) [31, 32] in adopting the event study model to test the parallel trend assumption. The model is as follows:
Where Agglomeration(t) represents year policy state variables, this identifies the annual policy effects of higher education agglomeration in the t year, relative to the higher education agglomeration year. Agglomeration (+1) identifies the policy effect of the higher education agglomeration one year later relative to the higher education agglomeration. As Li et al. (2016) state, this paper considers the agglomeration (-1) as the base period. If our model satisfies the parallel trend assumption test, the coefficients of agglomeration (-9), …, and agglomeration (-2) should roughly be insignificant. Fig. 2 shows that the coefficients of pre-policy year variables (agglomeration (-9), …, and agglomeration (-2)) are roughly insignificant, indicating that our model satisfies the parallel trend assumption test.
Mechanism Analysis
In the above discussion, we have demonstrated that higher education agglomerations would improve firm ESG performance. However, it is not clear how the higher education agglomeration affects the firm ESG performance. Intuitively, the higher education agglomerations could provide local firms with convenient conditions, making it easier for them to attract and hire high-quality employees. Therefore, in this section, we will explore whether firms located in higher education agglomerations would have higher human capital, hire more high-skill workers, and have better corporate governance, which would enhance firm ESG performance. Firstly, we will check whether higher education agglomerations would improve firm human capital. We measure the firm human capital quality (lnEducation) by the logarithm of the sum of three times the master number and two times the undergraduate number. In column (1) of Table 3, the agglomeration is significantly negatively correlated with LnEducation, suggesting that firms located in higher education agglomerations will hire higher education employees. Secondly, we will check whether human capital agglomerations will hire more highly skilled workers. We follow Kong et al. (2023) [33] and measure the higher-skilled workers by firm R&D staff (LnRD_ Staff). In column (2), the agglomeration is significantly negatively correlated with the LnRD_Staff, suggesting that the firms located in the human capital agglomeration from college town construction will hire more high-skill workers.
In summary, higher education agglomerations would improve firm ESG performance by improving corporate human capital and hiring more skilled workers.
Heterogeneity Effects of Higher Education Agglomeration on Firm ESG Performance
In this section, we will explore the heterogeneous effects of higher education agglomeration on firm ESG performance from the perspectives of firm property rights and industry technicalization. The results are reported in Table 4. Firstly, we divided the sample into SOEs and non-SOEs based on the firm’s property rights. And we re-regress model (1) in two samples. In columns (1) and (2), we found that the coefficient of agglomeration in the SOE samples is larger and more significant. The reason for this may be that most higher education institutions in China are state-owned and have close ties with the government; at the same time, SOEs usually follow government directives more closely. Therefore, the connection and communication between SOEs and higher education institutions are relatively closer compared to private enterprises, which makes the impact of higher education agglomerations on the SOEs’ ESG performance more significant. Secondly, to explore the impact of higher education agglomeration on firms with different levels of industry technicalization, we followed Wu et al. (2022) [34] and divided the samples into high-tech firm sample and non-high-tech firm samples, using a re-regression model (1) based on two samples. In columns (3) and (4), we found that the core explanatory variable, agglomeration, is only significantly positive in a high-tech firm sample. A possible reason is that high-tech firms have a greater demand for high-quality labor and need to absorb fresh graduates with innovative capabilities each year to add new vitality to their innovation.
In summary, we found that the higher education agglomeration from the university town construction has a great impact on SOE and high-tech firms.
Robustness Checks
In this section, we will do some robust checks to further support our core conclusions. The results are reported in Table 5, Table 6, and Table 7.
Alternative Dependent Variables
Because firm ESG performance is the count-based outcome, which would bias our estimator, we construct the variable LnESG_HSE by making an inverse hyperbolic sine transformation for firm ESG performance in the robust checks [35, 36] Additionally, following Larch et al. (2019) [37], we adopt the PPML Model to identify the effect of higher education agglomeration on firm ESG performance. The results in columns (1) and (2) of Table 5 show that the higher education agglomeration would also improve the firm ESG performance.
Table 3.
Mechanism analysis.
| (1) | (2) | |
|---|---|---|
| LnEducation | LnRD_Staff | |
| Agglomeration | 0.406*** | 1.161* |
| (3.435) | (1.858) | |
| City Control | YES | YES |
| Firm Control | YES | YES |
| Firm FE | YES | YES |
| Industry-Year FE | YES | YES |
| Province-Year FE | YES | YES |
| Observations | 12261 | 2024 |
| Adj_R2 | 0.732 | 0.890 |
Table 4.
Heterogeneity effects of higher education agglomeration on firm ESG performance.
Table 5.
Robust check 1.
Placebo Test
In this section, we will do the year placebo test. Specifically, this paper constructs the virtual policy variable (Placebo2, Placebo4, Placebo6) by assuming that the higher education agglomeration before the 2 (4, 6) year compares to the real higher education agglomeration year. And the results are shown in columns (3), (4), and (5). The coefficients on Placebo2, Placebo4, and Placebo6 are not significant, indicating that the improvement in ESG performance is really caused by the higher education agglomeration.
Excluding the Impacts of Concurrent Policies
In this section, we will exclude the impacts of concurrent policies (the Clean Air Action in 2013, CAA; Low Carbon Cities policy from 2011, LCCP; and the 2019 Covid-19 policy) on the firm ESG performance. Firstly, following Zhu and Xu (2022) [38], we construct the variable CAA, measured by the intersection of the natural logarithm of city emission reduction targets and Post (Post is a dummy variable, which equals 1 if the year is larger than 2013). To exclude the impact of CAA, we add the variable CAA to the model (1). The result of column (1) shows that the core conclusion still holds. Secondly, referring to Zeng et al. (2023) [39], we construct the variable LCCP, measuring that LCCP would equal 1 when city c is listed as the LCCP cities, otherwise zero. To exclude the impact of LCCP, we add the variable LCCP to the model (1). The result of column (2) shows that the core conclusion still holds. Additionally, Wuhan in China has outbroken the COVID-19 pandemic in December 2019. To exclude the impact of the COVID-19 pandemic, we restricted the sample to before 2019. The core conclusion still holds in column (3). Finally, we control the intersection term of province, industry, and year fixed effect to exclude the impact of province industry policies during the year, such as the value-added tax (VAT) policy in 2012. The result is shown in column (4). The core conclusion still holds.
Other Robust Check
In this section, we will do other robust checks, including adopting the propensity score matching DID (PSM-DID) and controlling the impacts of city characteristics. In the propensity score matching, we adopt the 1:1 nearest neighbor matching method [40], the radius matching method [41], and the kernel matching method [42] to select more similar treatment and control groups. In columns (1), (2), and (3) of Table 7, the results show that our core conclusion still holds. There are some city characteristics that would affect the firm’s ESG performance, such as city geography, city trend, and initial city characteristics. In column (4), we add the intersection of city geography characteristics (altitude, slope, and distance from the coastline) and a year dummy to control the city geography effect. In column (5), we further add the intersection of city dummy and year trend to control the city trend effect. In column (6), we further add the intersection of the city initial control variable and year of the trend to control the initial city characteristics effect. And all the results show that our core conclusion still holds.
Table 6.
Excluding the impacts of concurrent policies.
Table 7.
Other Robust Check.
Conclusions and Policy Implications
Conclusions
Exploiting the Chinese university town construction as an exogenous, quasi-natural experiment, this paper explores whether and how higher education agglomeration affects the firm ESG performance with the DID method. We find that the higher education agglomeration would improve the firm ESG performance. This effect is more prominent in SOEs and high-tech firms. Additionally, the potential channels for improvement in firm ESG performance are that higher education agglomerations would increase human capital and hire more skilled workers.
Policy Implications
Based on the empirical research results and analysis conclusions, we propose the following policy implications: Firstly, Table 2 shows that higher education agglomerations would improve the firm ESG performance. Therefore, governments should continue to increase planning and investment in the construction of university towns. This includes not only plans for new university towns but also the upgrading and optimization of existing ones, providing advanced educational and research facilities to strengthen talent cultivation and scientific innovation capabilities.
Secondly, Table 4 shows that the effect of higher education agglomerations is more prominent in SOE and high-tech firms. Therefore, university towns should enhance the cultivation of high-quality talent. Governments can encourage schools to promote the comprehensive development of students and faculty through course innovation, academic exchange, and practical projects during the planning of university towns. Emphasizing the cultivation of practical skills and innovative thinking in students prepares them for future entry into the business world, thus nurturing high-quality talent with modern knowledge structures and innovative capabilities for society.
Thirdly, Table 3 shows that higher education agglomerations would increase human capital and hire more skilled workers. Therefore, governments should encourage and facilitate cooperation between universities and various types of enterprises, especially between state-owned and high-tech industry enterprises. Such cooperation not only promotes the practical application of academic research results but also helps companies achieve breakthroughs in R&D and technological innovation. Through diverse cooperation models, such as joint R&D projects, internship and employment programs, and joint research centers, these measures will directly enhance the quality of corporate human capital and improve corporate ESG performance.
There are heterogeneous treatment effects in our model; future research could explore heterogeneity effects testing following Callaway and Sant’Anna (2021) and Sun and Abraham (2021) [43, 44]. Our sample focuses on publicly listed companies, future research could examine non-listed small and micro enterprises for a more comprehensive understanding. Our paper just examines the impact of university town establishments on the local firm ESG performance, future research could consider the spillover effects of university town establishments on the ESG performance of companies in other cities.

