

Introduction
About 55 percent of the world’s population lived in urban areas in 2018, and the United Nations projects that the global urban population will reach 68 percent by 2050 [1]. Although the rapid development of urbanization has brought a great deal of material wealth, greenhouse gas emissions have also led to a complex and changeable climate, threatening human health and living environments [1]. China, the largest carbon emitter, vowed to curb greenhouse gas emissions at the Copenhagen climate conference and has since proposed a “dual-carbon target” [2, 3]. Due to the economic downturn and environmental policies, although the growth rate of energy consumption and carbon dioxide emissions has decreased recently, due to the large economic scale, the energy structure has been heavily dependent on coal for a long time, resulting in high carbon intensity. In addition, the carbon-intensive economic structure is relatively high. Under the backdrop of the “new normal”, the medium-level growth rate of the Chinese economy will undoubtedly pose challenges to global environmental governance and climate change [4].
Existing studies have discussed the implementation effect of pilot policies in low-carbon cities from different angles [5-10]. From the perspective of economic effect, pilot policies in low-carbon cities can help regions with better infrastructure to form economies of scale, significantly increase the gross urban product, and increase the proportion of producer services [11]. At the same time, technological innovation at the enterprise and city levels will be promoted to upgrade industrial structures and improve enterprise productivity [12]. From the perspective of social effects, the construction of low-carbon pilot cities can reduce carbon emission levels and power consumption intensity, control urban haze pollution, improve air quality, and effectively realize the prevention and control of air pollution. However, some studies have pointed out that with the in-depth development of pilot policies for low-carbon cities, problems such as incomplete policy implementation [13], an imperfect evaluation system, and inadequate financial support have been exposed, which affect the effectiveness of policy implementation [14]. According to the report of the 19th National Congress of the Communist Party of China (CPC), the Chinese economy has shifted from a stage of high-speed growth to a stage of high-quality development [15]. High-quality development of enterprises is the microfoundation of high-quality economic development. The transformation of economic development mode, the optimization of economic structure, and the transformation of growth drivers are inseparable from the subjective role of enterprises. In this context, as an important environmental policy, whether low-carbon city pilots can achieve win-win economic efficiency and social benefits and promote the high-quality development of microenterprises is the core issue of this study.
Based on this, this paper takes 281 cities at or above the prefecture-level level in China from 2009 to 2019 as research objects and constructs the STIRPAT model to test the impact of financial development on urban low-carbon economic transformation. The possible innovation points and marginal contributions of this paper are as follows: First, it takes urban economic development as the starting point and enriches the research on low-carbon urban transformation. Most of the existing literature analyzes the industrial structure upgrading effect and pollution control effect of low-carbon cities solely from an economic or social perspective. However, few studies have explored the impact of financial development on urban low-carbon economic transition. This paper is conducive to a more comprehensive evaluation of the transformation of low-carbon cities. Second, it enriches the research on the measurement connotation and influencing factors of financial development. Based on the two dimensions of urban financial development -- the capital demand side and the capital supply side -- this paper coordinates the total factor productivity and sustainable development performance of financial development and demonstrates and tests the intermediary role of environmental rules, industrial structure, and urbanization. A comprehensive analysis of the impact of financial development on the urban low-carbon economic transition provides new test evidence for whether the “Porter hypothesis” conforms to the status quo of China’s low-carbon economic transition.
Compared with previous studies, the main contributions of this study are as follows: first, it examines the influence of financial development on the transformation of low-carbon economies under different constraint mechanisms and puts forward a path for reference to better improve the effect of regional low-carbon economy transformation under different constraint conditions. Second, considering the transmission effect of environmental regulation, industrial structure, and urbanization on financial development and low-carbon economic transition, it provides new basis and ideas for the introduction of appropriate environmental and industrial policies and the improvement of urban management levels.
Literature Review
As the relationship between financial deepening and economic growth tends to be stable, more and more studies take financial factors into consideration in the field of environmental economies. Based on the research theme, this part classifies literature related to financial development, carbon emissions, and economic transition to provide theoretical support for the mechanism analysis and research hypothesis in the following paper.
Financial Development and Carbon Emissions
Existing studies on the impact of financial development on carbon emissions can be roughly divided into four categories: 1) inhibition effect. Financial developments encourage companies to adopt new technologies, improve energy efficiency, and promote an increase in renewable energy consumption, leading to a decline in carbon emissions [16]. 2) Promoting effect. Active capital market activity affects consumer and business confidence by creating funds that may expand the economy and sustain energy demand, leading to increased energy consumption and CO2 emissions [17]. 3) Neutral or insignificant. Dogan and Turkekul’s (2016) study [18] of nearly 50 years of US data found no significant correlation between financial development and environmental quality, which does not support the validity of the US environmental Kuznets Curve (EKC) hypothesis. Abbasi and Riaz’s (2016) study [19] of Pakistan comes to a similar conclusion. 4) Nonlinearity or uncertainty. Wan et al. (2018) [20] constructed an endogenous growth model including financial development, innovation and CO2 emission, and verified the inverted U-shaped relationship between credit scale and CO2 intensity in China. Fang et al. (2020) [21] proposed that the impact of finance on environmental quality is mainly realized through the scale effect of production expansion, the technical effect of scientific and technological progress and the structural effect of industrial adjustment.
Economic Transformation
The research on economic transformation is mainly based on the transformation effect, which focuses on three aspects. First, based on Porter’s hypothesis, the impact of environmental regulation on regional and industrial green transformation is analyzed [22]. Considering that the key impact of environmental regulation is to promote the green innovation of enterprises, most scholars believe that environmental regulation can promote the technological innovation of the industrial sector and then drive the overall green transformation [23]. Second, evaluate various green economic policies. For example, the impact of climate protection policies represented by the United Nations Framework Convention on Climate Change, energy policies represented by promoting the development of renewable energy such as photovoltaic hydropower and eliminating traditional energy subsidies [24], industrial policies represented by the development of a circular economy and rational allocation of green rent, and trade policies represented by carbon tariffs and carbon border adjustment mechanisms on economic transformation [25]. Third, the policies and measures of emerging economies represented by China to promote their own green transition and the impact of regional green transition on regional ecological environment and urban-rural income gap [26].
In addition to financial development, urbanization, trade openness, industrial structure, energy structure, R&D, and innovation are all important factors affecting carbon emissions and economic growth [27]. Institutional quality, the regulatory system, and the strength of the ruling party also have a significant impact on air quality [28]. Existing literature provides a logical starting point for follow-up studies, but studies on the economic consequences of financial development currently focus on the inter-provincial or national level, with a lack of studies on the city level. Moreover, among various influencing factors, environmental and economic impacts of environmental regulation and urbanization linked financial development are rarely considered, and the transmission mechanism of financial development on economic effects is rarely studied. In view of this, this paper uses the panel data of 281 prefecture-level cities in China from 2009 to 2019 and uses the STIRPAT Model and the threshold model to examine the impact of financial development on the realization of low-carbon economic transition under the constraints of different mechanisms such as environmental regulation, industrial structure, and urbanization.
Theoretical Analysis and Hypothesis
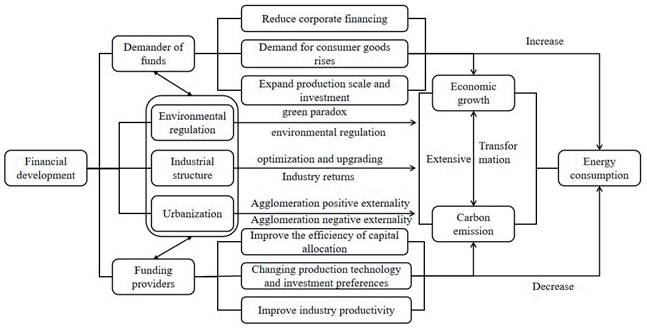
On the basis of literature reviews, this paper attempts to explain and construct the theoretical logic, action mechanism and research framework of the impact of financial development on low-carbon economic transition, as shown in Fig. 1. Then, this part puts forward the research hypothesis of this paper, including the following contents.
Financial Development and Low-Carbon Economic Transformation
Achieving a balance between carbon emission control and economic growth in a low-carbon context is a common challenge facing developing countries [29]. Dynamically adjusting the opportunity cost of environmental pollution through credit channels, for example, when polluting enterprises face higher threshold restrictions and transaction costs when obtaining credit financing, is an important embodiment of financial institutions’ capital allocation function under sustainable development [30]. According to the theory of financial development, the financial system (including financial intermediation and the financial market) mainly acts on economic growth through two major paths: “capital accumulation” and “technological progress” [31]. Since carbon productivity can measure the comprehensive level of low-carbon technologies in a country or economy over a certain period to assess the cost of carbon emissions brought by economic growth as well as measure the extent of a country’s efforts to deal with climate change, the main way to reduce carbon emissions and maintain economic growth is to improve carbon productivity. So, in the process of economic transformation, can financial development effectively improve carbon productivity? On the one hand, the continuous development of financial finance can broaden private lending channels, stimulate the demand for consumer goods, reduce credit discrimination against private enterprises or high-tech sectors with high production efficiency, and provide them with low-cost capital, thus strengthening the demand for energy in the expansion of economic activities and intensifying carbon emissions. On the other hand, the green development of finance guides financial resources to be invested in clean industries, promotes technological progress or organizational reform by spreading risks and reducing costs, and reduces energy consumption per unit of output, thus reducing carbon emissions [32]. At the same time, changes in production technology and investment preferences may have positive or negative impacts on carbon productivity in other regions through supply chain transmission. In general, financial development may not only promote the progress of production scale or extensive technology, leading to an increase in energy consumption and carbon emissions in the same direction as economic growth, but also encourage organizations and industries to focus on research and development activities, improve green technology progress, energy efficiency, and industry performance, so as to improve carbon productivity and promote the possibility and success rate of low-carbon economic transformation. Since there may not be a simple linear relationship between financial development and low-carbon economy transition, the following hypotheses are proposed:
H1: There is a nonlinear relationship between financial development and low-carbon economic transition.
Financial Development, Environmental Regulation and Low-Carbon Economic Transformation
Enterprises are the main source of energy consumption and environmental pollution, and environmental regulation is the institutional constraint put forward by the government on enterprises’ environmental behavior [33]. In addition to administrative means such as “shutdown and transfer”, incentive tools such as market income induction, the innovation compensation effect, and government support and guidance are also used to promote the technological innovation of enterprises so as to reduce carbon emissions [33]. The environmental awareness and strength of citizens and organizations will also help to improve environmental quality. Due to the negative externality of the environment, enterprises have different responses to the green strategy of carrying out technological innovation to reduce pollution. The endowment advantages of finance, such as capital, market, and credit, can make up for the deficiencies of micro subjects, such as a lack of behavioral incentives and an unfavorable policy environment. In the case of less stringent environmental regulations, pollution-intensive enterprises may take advantage of the higher return on capital to obtain more factors of production through finance, leading to a rapid increase in pollution levels [34]. In environmentally conscious economies, financial structures tend to provide better financial services for environmentally friendly projects. Strict environmental regulations not only guide financial market funds from “two high and leftover” industries to energy conservation, environmental protection, and green industries [35]. It forces high-polluting enterprises to carry out green innovation activities to reduce pollution in order to regain financial support from financial institutions. Moreover, it improves the transparency of environmental information, reduces the asymmetry of information, and encourages enterprises to obtain external financing with a larger scale, a longer term, and a lower cost [36]. Therefore, the hypothesis is proposed:
H2a: Financial development can influence the transition to a low-carbon economy through environmental regulation.
Financial Development, Industrial Structure and Low-Carbon Economic Transformation
Financial development can affect the transfer and allocation of resources between industries, especially in regions with weak economic foundations and large differences in productivity and recovery rates between industries. In order to speed up the process of industrialization, financial resources may be concentrated in industry, especially heavy industrial sectors in economically backward areas, thus inhibiting the development of clean industries [37]. When technology-intensive industries do not have a comparative competitive advantage, financial capital pushes local factors of production toward polluting industries with higher returns on capital [38]. When regional employment pressure is high, local governments may also use financial resources to promote the development of labor-intensive industries with lower technology levels. The existing industrial structure and its development mode may form path dependence and hinder industrial upgrading, which is not conducive to reducing carbon emission intensity. But without the development of industrial entities, it is difficult to solve the economic spears between development and the environment. So the pressure on resources and the environment can only be eased by more advanced and powerful industries. High-tech industries and tertiary industries not only have great potential to reduce emissions, but are also important areas for financial resource investment [39]. Unlike banks, which are subject to more government intervention, the market-oriented financial sector is more sensitive to industrial competitiveness and can better identify the growth capacity of different industries. In recent years, China’s industrial structure has seen an obvious transition to high-end manufacturing and the service industry. Good financial development may prompt production resources to flow from the industrial sector to the low-carbon service sector or change the internal output composition and proportion of the manufacturing sector so as to promote the optimization and upgrading of industrial structures and improve carbon productivity. Therefore, the hypothesis is proposed:
H2b: Financial development can influence the transformation of a low-carbon economy through industrial structure.
Financial Development, Urbanization and Low-Carbon Economic Transformation
Due to the advanced public service level and superior location conditions, the early financial centers were mainly distributed in global or regional big cities, such as New York and Tokyo. According to the city size hypothesis, the financial industry, as a high-end value-added service industry in modern cities, needs a high level of matching and economic support, and its development has a high population and market threshold [40]. The in-depth development of finance is usually inseparable from the agglomeration effect of enterprises. The positive externality of agglomeration brings industrial support and financial guarantee to economic growth and promotes the development of urbanization by improving efficiency and increasing the employment population [41, 42]. Urbanization concentrates a large amount of industrial capacity, leading to output expansion. The continuous influx of enterprises and population gradually increases the demand for infrastructure and energy such as electric power and urban construction, which has a significant impact on urban pollution and carbon emissions. On the one hand, in order to increase economic output and household income, regional governments may focus on developing industry and promoting carbon emissions. On the other hand, with the improvement of the quality of life of urban citizens, the collective awareness of environmental protection and the willingness to engage in green consumption will be enhanced, and the demand for leisure and greening will be higher, which may stimulate the agglomeration of the service industry, prompt enterprises to turn to clean technology innovation and production of environment-friendly products, and promote the growth of the low-carbon economy. Based on this, the following hypothesis is proposed:
H2c: Financial development can influence the transformation of a low-carbon economy through urbanization.
Methodology
Method Research
The STRIPAT model proposed by [43] is a classic model for studying industrial, economic and environmental issues. This model allows proper decomposition and improvement of impact factors, but it assumes that the relationship between variables is linear.
1. Benchmark regression model
Based on a wide range of STIRPAT models in the field of environmental economics:
Where I represents the transformation of the urban low-carbon economy and P represents the population factor, which is measured by population density. A is wealth. T is technology level, measured by per capita GDP and the number of patent applications in cities. ε represents the random error term. On the basis of considering the effect of traditional variables on the transformation of low-carbon economies, after the logarithm of Equation (1) is taken, ordinary least squares (OLS) aggregated at the region-year level is used to investigate whether financial development contributes to the transformation of low-carbon economies. According to Hypothesis H1, considering the uncertainty of the impact of financial development on the transformation of low-carbon economies, a quadratic term (FD2) is introduced to construct the benchmark regression model, as shown in Equation (2):
Table 1.
CO2 emission coefficient.
Among them, LCET stands for low-carbon economic transition, measured by carbon productivity. FD is an explanatory variable, representing the degree of financial development. i for city. t is time. εit is a random disturbance item. μi is the individual effect. In order to further understand how financial development affects regional low-carbon economic transformation, the following model is set up to explore the transmission path of financial development by referring to the transmission effect model of He et al. (2019) [44]:
Where, Z represents the possible path of regional low-carbon economic transformation influenced by financial development, and β2 is used to measure its impact.
Threshold Estimation Model
According to the above analysis and assumptions of H2a, H2b, and H2c, the transformation effect of a low-carbon economy on financial development may be affected by the threshold effects of various factors. Referring to the fixed-effect panel threshold model set by Lin and Li (2020)[45], the indicator function is introduced on the basis of Equation (2), and considering the possibility of multiple threshold values, the multi-threshold panel model is finally constructed in this paper:
(4)
Where, I(·) is the indicative function and qit-1 is the threshold variable, which are respectively measured by financial development degree (FD), environmental regulation (ER), industrial structure (INS) and urbanization level (URB). γ is the unknown threshold.
Sample and Data Source
The sample of this paper includes 281 cities at the prefecture level and above, excluding Tibet and a small number of cities where data are seriously missing. Individually missing data were supplemented by the interpolation method. Considering the adverse impact of the financial crisis, data from 2009 to 2019 was selected. At the same time, in order to eliminate the impact of inflation, the price variables involved need to be deflated based on the 2008 GDP index. The data and other variables needed to calculate urban carbon emissions are mainly collected from the China City Statistical Yearbook, the China City Construction Statistical Yearbook, the Statistical yearbooks of provinces and municipalities, as well as the China Research Data Platform (CNRDS), the Flush (IFIND), and the CSMAR database. In order to reduce the influence of outliers, all continuous variables are reduced by 1%.
Variable Definition
Explained variable: Transition to Low carbon Economy (LCET). Industrial or economic transformation is generally measured by green production efficiency. In this paper, based on the research of Wang et al. (2019b), considering that carbon productivity directly reflects the comprehensive utilization efficiency of carbon resources in the social economy, LCEFF, that is, the gross national income created by each unit of CO2 emission, is adopted to measure the transformation degree of regional low-carbon economies. Due to the lack of city-level carbon emission data, the method proposed by Wang et al. (2022) [47] is used as a reference to measure and sum carbon emissions generated by various energy sources. The calculation method is shown in Equation (5).
C1, C2, C3, and C4 are respectively the carbon dioxide emissions caused by natural gas, liquefied petroleum gas, electricity consumption by the whole society, and steam and hot water heating. In urban steam and hot water heating, raw coal is mostly used as a raw material. Considering that the current coal-burning industrial boilers for central heating are mainly small and medium-sized boilers, a 70% thermal efficiency value is adopted to calculate. The average low calorific value of raw coal is 20,908 kJ/kg. The amount of raw coal needed is calculated using heat supply, thermal efficiency, and the calorific value of raw coal. Ei is the consumption of all kinds of energy, and ki is the corresponding conversion coefficient of CO2, as shown in Table 1. At the same time, Afonso et al. (2021) [48] took energy use efficiency (ENU) as the alternative index of LCET. The larger the ratio (actual output value of the secondary industry/total energy use), the higher the energy use efficiency and the more optimized the economic structure.
Explanatory variable: degree of financial development (FD). Based on the study of Zhang et al. (2012), this paper adopted the ratio of financial institution loans to GDP at the end of a city as the proxy variable of financial development. In order to further test the robustness, the diversification degree of financial development is examined from the perspective of financial structure (FDS). The larger the value (total stock market value of local listed companies at the end of the year/deposit balance of financial institutions at the end of the year), the less easily financial institutions in the city are absorbed by the banking industry, and the higher the marketization degree of financial development. Both measures exclude foreign currency and extended credit.
Intermediate variables: environmental regulation intensity (ER), industrial structure optimization (INF), urbanization (URB). The intensity of environmental regulation has a direct influence on regional environmental input costs and environmental performance. This paper starts with the effect of regulation, considering that the pollution produced by cities is mainly industrial pollution and the difference in economic size of each city. It selects four indicators of industrial wastewater discharge: industrial sulfur dioxide emission intensity, industrial soot emission intensity, and the solid waste treatment rate of each city. The entropy method was used to calculate the ave cttive weights, and then the linear weighted sum was used to obtain the comprehensive emission of industrial pollutants (POL) in different cities in different years. The output of each unit of comprehensive pollutants (ER = actual GDP/POL) was used to measure the strictness of environmental regulations.
Most literature uses rationalization or upgrading of industrial structures to measure the optimization degree of regional industrial structures [50, 51]. In this paper, the ratio of output value between tertiary industry and secondary industry is used to measure the optimization degree of industrial structure. The representative indicators of urbanization can be divided into population and land urbanization, which can be specifically divided into the proportion of urban population, built-up area, industrial output value, and construction output value. In this paper, the proportion of the population of a municipal jurisdiction in the whole city’s population is selected as a proxy indicator of urbanization.
Control variable. In addition to the three intermediate variables, combined with the actual situation of China’s economic development. Energy structure (ES, industrial electricity consumption/social electricity consumption), foreign direct investment (FDI, FDI actually used* average annual exchange rate /GDP) and human capital (HUM, number of college students per 10,000) were selected to control the differences in energy consumption, business environment, capital stock, and intellectual input of workers.
Results
Benchmark Regression Analysis
Descriptive statistics and kernel density analysis. Table 2 shows the descriptive statistics of the main variables. The mean value (0.935) of carbon productivity (LCTFF) is equivalent to the median value (0.833), indicating that the selected samples can better reflect the overall effect of the low-carbon economy transition. The minimum value of financial development (FD) is 0.287, and the maximum value is 3.148, indicating that the financial scale of different cities varies greatly and that there is still room for improvement in the transformation of low-carbon economies driven by financial development. Among the control variables, the standard deviations of the number of patent applications (T) and human capital (HUM) are relatively large, indicating that there is a certain gap between the innovation output of different cities and the higher education level of labor markets Before the regression analysis, the collinearity test was carried out, and the results showed that the mean value of VIF was 2.36, and the maximum value was 4.18, both lower than the critical value of 10. Moreover, the correlation between various variables was weak, and most of the correlation coefficients were below 0.3, so the regression equation basically did not have multicollinearity problems.
Table 2.
Descriptive statistics.
Table 3.
The test results of financial development on low-carbon economic transition.
From the perspective of distribution position, the peak of the carbon productivity curve generally shifted to the left, indicating that the carbon productivity of all cities showed a downward trend from 2009 to 2019. In particular, since 2015, the annual average growth rate of GDP has dropped below 7%, indicating that economic growth and carbon emissions may have a strong negative decoupling. Under the guidance of the “two-carbon” goal, many developed provinces and cities, such as Shanghai, Beijing, and Jiangsu, have proposed to take the lead in achieving the carbon peak in advance. Therefore, carbon productivity may continue to show a downward trend in the next 10 years. From the perspective of distribution pattern and ductility, the peak height of the carbon productivity curve increased significantly after 2015, while the width became narrower, which means that the non-equilibrium of carbon productivity in various cities tended to weaken, and the gap between high and low carbon productivity cities narrowed to a certain extent. From the perspective of distribution position, the peak of the financial development curve moves to the right year by year, indicating that the financial development of all cities presents an overall upward trend from 2009 to 2019. The left tail of the curve shrinks to the right year by year, indicating that the density of urban financial development scattered on the left gradually decreases while the number of areas tending to be financially developed increases significantly. However, the right tail of the curve did not improve significantly, indicating that there is a trend toward “high-end” financial development in some regions.
Baseline regression analysis of financial development and low-carbon economic transition. Table 3 shows the empirical results of the relationship between financial development and low-carbon economic transition under the OLS model. Columns (1) and (3) show that financial development is obviously unfavorable to the transformation of the low-carbon economy when only the influence of the FD primary term is considered. In column (2), the FD coefficient was negative and significant (β1 = -0.549, p<0.01), and the FD2 coefficient was positive and significant (β2 = 0.128, p<0.01) when quadratic terms were considered. The inflection points of the curve X* are calculated (X* = -β1/2β2 = 2.145). Since FD ranges from 0.287 to 3.148, the inflection point is between the range of values. The slope of FD was greater than 0 at the maximum value (FDMAX’ = β1 + 2β2FDMAX = 0.257) and less than 0 at the minimum value (FDMIN’ = β1 + 2β2FDMIN = -0.476). At the same time, the three conditions of the “U-shaped” relation proposed by Haans et al. (2016) are satisfied. Therefore, there is a “U” shaped relationship between financial development and carbon productivity, which first inhibits and then promotes. In other words, when the degree of financial development is low, there is a negative correlation between financial development and low-carbon economic transformation, while when financial development exceeds a certain critical value, there is a positive correlation between financial development and low-carbon economic transformation. This may be because the financial sector pays little attention to the environment in the initial stages of economic growth and improves environmental quality by lending to environmentally friendly projects once the economy matures. Considering that there may be variables that affect carbon productivity but do not vary with the year, a fixed effect estimation is carried out. According to the regression results in Column (4), the correlation values also meet the three conditions proposed by Haans et al., and the U-shaped relationship between FD and LCEFF is still valid, so hypothesis H1 is verified. Since the sample median and mean of FD are both less than 0.99, the U-shaped curve inflection point of FD and LCEFF has not been reached, indicating that the U-shaped curve is skewed to the left; that is, financial development at the present stage is more of an inhibition effect on the low-carbon economic transformation of most cities in the sample. Even after considering the fixed effects of region and year, the inhibition effect is still the dominant effect.
Analysis on the conduction path of financial development to low-carbon economic transformation. In Table 3, columns (5), (7), and (9) examine the indirect influence of financial development on low-carbon economic transition through environmental regulation, industrial structure, and urbanization. The control variables added in each regression are the same as the baseline regression. Except for the effect of environmental regulation, the influence of financial development on the other two transmission paths presents a significant “U” shape; that is, the “U” shape influence of financial development on regional low-carbon economic transformation is transmitted through the intensity of environmental regulation. When the level of financial development is too high, the optimization of industrial structure and the agglomeration effect of population in the central city have adverse effects, which verifies the hypotheses H2a, H2b, and H2c. Because environmental regulation, industrial structure, and urban size change have different mechanisms of action on carbon emissions, the effect of financial development on urban low-carbon economic transformation depends on the relative size of the environmental effect, structural effect, and scale effect.
Endogeneity and robustness tests. There may be an endogenous relationship between the degree of financial development and the transformation effect of a low-carbon economy. The degree of financial development will affect carbon emissions, but on the contrary, regions with higher carbon productivity usually have a higher economic density, which is conducive to the development and agglomeration of the financial industry; that is, there may be a reverse causality between financial development and low-carbon economic transformation. This paper uses the propensity score matching method (PSM) to solve this endogenous problem.
Table 4.
Threshold effect existence test, estimated value, and confidence interval.
Since the heterogeneity of cities will directly affect carbon productivity, this paper selects the variables that are not included in baseline regression, such as the proportion of financial expenditure on science and education, topographic relief, proportion of secondary industry, and green coverage rate, as well as the variables ES and FDI, and constructs the Logit model to match the sample cities so as to find the approximate cities for regression. Samples are grouped according to the degree of financial development. The specific methods are as follows: Each city was ranked from the highest FD value to the lowest FD value every year and then scored according to the ranking (the higher the ranking, the lower the score). Then the total scores of each city from 2009 to 2019 were added and averaged, and the cities were ranked according to the total scores from the lowest to the highest. The cities ranked above the median were the financially developed group, while the rest were the financially underdeveloped group. The caliper nearest neighbor matching method (neighbor = 2) was used to eliminate the unmatched observations, and the control variables selected by the matching samples passed the balance test. There was no statistically significant difference between the experimental group and the control group (the P-value of the above variables in the T-test was at least greater than 0.184); that is, the selection of matching variables and methods was appropriate, and the matching estimation results were reliable. The matched samples were returned again, and the results were consistent with the results of multiple regression. At the same time, the alternative dependent variable – energy profit efficiency (ENU) and the alternative variable financial structure (FDS) of financial development were used to test the robustness of the regression results under fixed and random effects. The test results showed that there was still a significant U-shaped relationship between financial development and the transformation of the low-carbon economy.
Threshold Regression Analysis
In order to investigate whether the influence of financial development on low-carbon economic transition is limited by the threshold effects of finance itself, environmental regulations, industrial structure, and urbanization. Through Bootstrap sampling 5000 times, the null hypothesis with no threshold value, one threshold value, and two threshold values were tested, respectively, and the F statistic and P value under “Bootstrap” were obtained. The triple threshold effect of the whole sample was not significant, while the effect of a single threshold or double threshold was significant. The results are shown in Table 4. Based on the principle of minimum sum of squares of residuals, the value of the threshold variable was further searched to obtain the threshold estimate and 95% level of confidence interval (LR<7.35).
Table 5 shows the full sample estimation results of the panel threshold regression model, indicating that the effect of financial development (FD) on low-carbon economic transition is influenced by the threshold effects of financial development itself, environmental regulation (ER), industrial structure (INS), and urbanization (URB), which verifies hypotheses H1, H2a, H2b, and H2c again. Column (1) shows that, with the deepening of financial development, the transformation effect of a low-carbon economy presents a trend of promoting First, then inhibiting, and finally promoting: When FD is between the first and second thresholds (0.549-2.239), the estimated coefficient of FD on LCEFF drops from 0.087 to -0.025. Based on the baseline regression results, it can be seen that financial development at this stage has an inhibiting effect on the low-carbon economic transformation of most sample cities. When FD crosses the second threshold (2.239), financial development has a positive impact on the transformation of the low-carbon economy again. In general, the deepening of financial development is conducive to easing the adverse impact of finance on the transition to a low-carbon economy. Fig. 3 shows that financial development in most areas of China has not yet crossed the second threshold. In the three intervals bounded by the threshold value of urbanization, the transformation effect of the low-carbon economy also showed an “N-shaped” pattern of first rising, then falling, and then rising with the deepening of financial development: when URBAN was between the first and second thresholds (0.142- 0.321), URB’s estimated coefficient of LCEFF decreased from 0.047 to -0.051. When URB crosses the second threshold, its estimated coefficient rises to 0.007. This is basically consistent with the conclusion of baseline regression, indicating that the process of urbanization is an important factor in the increase in carbon emission intensity. When urbanization reaches a certain level, the positive environmental effect of finance plays a dominant role. When ER and INS crossed the threshold values, respectively, the estimated coefficients of LCEFF changed from negative to positive. It shows that the increase in environmental regulation intensity and the optimization of industrial structure magnify the favorable influence of financial development on the transformation of low-carbon economies, and further indicate that the compensation effect of environmental regulation and the “structural dividend” brought by industrial adjustment and optimization can continuously improve the allocation of social production factors. Thus, the efficiency of green development will be effectively improved, and the transformation of the regional low-carbon economy will be promoted.
Table 5.
Panel threshold regression results.
Discussion
In the face of the new normal of economic development with slowing growth and changing driving forces, this paper proposes the following policy implications for improving the financial market:, environmental policies, industrial structure, and urban development, and integrating financial development, economic growth, and energy consumption to promote the synergistic effect of regional low-carbon economic transition to achieve high-quality development.
First, we should optimize the design of the financial system and strengthen the construction of the capital market. Combined with the actual situation, the financial development of most cities is between the first and second thresholds. Therefore, it is necessary to further expand the financial scale and improve the depth and efficiency of financial service entities on the premise of paying attention to the environmental impact [37]. Developing green finance is an important means to support the improvement of the quality of economic growth, and is also an important trend for the development of our financial institutions. We should improve the policy framework and incentive mechanism for green finance that favors low-carbon enterprises, and vigorously build and develop multi-tiered currency, capital, and derivatives markets [53]. Financial institutions should promote the innovation of financial products and tools, and broaden capital sources by guiding government funds and social capital to meet the demand for diversified financial services such as venture capital, venture capital, breakeven merger and acquisition and financing guarantees in economic activities such as technology research and development, industrial adjustment, and asset transfer in the process of structural transformation [45]. Give full play to its resource allocation function to realize the low-carbon and green development of the whole economy. At the same time, the government leads the establishment of enterprise pollution information supervision platforms and environmental information sharing platforms, and connects them with the financial credit information base database, so as to provide an evaluation basis for the majority of financial institutions to screen clean projects, evaluate green benefits, and make green credit decisions.
Secondly, a reasonable choice of environmental regulation intensity and regulation tools willto strengthen the level of urban management. In recent years, the size of cities and “new first-tier cities” hasve increased rapidly, which means that the corresponding governance system, population structure, and ecological management need to be improved to properly handle the gap between the rich and the poor, energy consumption, public security, and other social conflicts brought about by urbanization. Therefore, appropriate environmental policies should be introduced to create an external environment conducive to energy savings and emission reduction. Although high-intensity environmental regulations may hinder capital inflow or aggravate the “greenwashing” and “greenwashing” of enterprises, too low intensity of regulations may lead to the transfer of capital to pollution-intensive industries [30]. Due to the existence of pollution paradise and the boundary effect, governments at all levels should coordinate their environmental protection efforts to avoid the relocation of enterprises with high pollution and high energy consumption to areas with weak environmental regulations. More importantly, resource consumption, environmental damage, and ecological benefits should be incorporated into the evaluation system of economic and social development, and strong environmental governance measures should be adopted, such as strengthening environmental protection talks and penalties, and changing the allocation of resources through financial means, so as to improve the quality and efficiency of economic development through technological progress or organizational reform.
Third, we will improve policies for the development of green and low-carbon industries and promote the optimization and upgrading of the industrial structure. Due to the different factor endowment conditions in different regions, on the basis of giving full play to the characteristic advantages of local resources, hard infrastructure construction and soft institutional arrangements, such as adjusting human resources policy and opening to the outside world allocation structure, are adopted. Introduce advanced technology, absorb talents and foreign investment, reduce transaction costs, encourage regional enterprises to strengthen green process innovation to improve cost control ability or promote green product innovation to achieve product differentiation, reduce pollution treatment costs, and constantly improve industrial and technological upgrading [39]. The government should strengthen its support for the green economy, and provide appropriate industrial support and financial support when necessary. For example, the government should ease the constraints on green clean projects and financing by means of financial discounts for green projects and risk write-off funds.
Conclusions and Recommendations
Conclusion
In this paper, OLS regression and the panel threshold model are used to conduct in-depth research on the relationship between financial development and urban low-carbon economic transformation. H1, H2a, H2b, and H2c were verified. The main conclusions are as follows: First, there is a U-shaped relationship between financial development and low-carbon economic transformation. When the degree o financial development exceeds a certain critical value, the higher the degree of financial development, the more conducive it is to the realization of low-carbon economic transformation.
Second, the intermediate mechanism test shows that the U-shaped influence of financial development on the transformation of the low-carbon economy is mainly transmitted through three ways: environmental regulation, industrial structure optimization, and urbanization. When financial development level control is within a reasonable range, these three paths can all play an important role in guiding investment and financing direction, reducing product and information transmission costs, promoting clean industry development, improving production efficiency, and reducing carbon emissions.
Third, financial development has a significant threshold effect on the transformation of the low-carbon economy, and its process is limited by the differences betweenof financial development itself, environmental regulations, industrial structure, and urbanization. The higher the degree of financial development, environmental regulation intensity, industrial structure optimization, and urbanization, the lower the negative impact of financial development on carbon productivity, and the higher the degree of low-carbon economic transformation.
Recommendations
First, it is necessary to summarize the development experience of low-carbon pilot cities on the existing basis, expand the scope of promotion, help other cities explore low-carbon transformation schemes through common comparison and differential analysis, and mobilize the widespread participation of local governments. Based on the high-quality development perspective of micro enterprises, the implementation of pilot policies for low-carbon cities is positive and effective on the whole. But at the same time, it should be noted that there are significant differences in the effectiveness of different types of policy tools, and the role of market incentive policies in low-carbon pilot cities still needs to be improved. Local governments should pay more attention to the establishment and improvement of the market system, create a service-oriented role for the government, and promote the construction of a carbon trading market. The central and provincial governments can clarify management and responsibility mechanisms based on the actual situation of pilot cities, stimulate pilot cities to explore market-oriented approaches, help local governments improve the supporting system of market orientation, and guide enterprises to achieve a low-carbon transition.
Second, innovation is an important way to promote high-quality enterprise development in pilot low-carbon cities. The government should further attach greater importance to technological innovation, create a favorable environment for enterprises to innovate, stimulate their innovation vitality, and help enterprises improve their research and development efficiency through the development of low-carbon technology industriesy and the transformation of results. Attention should be paid to the relationship between economic efficiency and the social benefits of high-quality enterprise development of enterprises, and enterprises should be guided to change their development mode and improve production efficiency. Enterprises should speed up the transformation of development mode, realize quality reform through dynamic reform and efficiency reform, establish long-term sustainable development concepts, and fulfill their responsibilities and obligations as economic and social subjects.
Third, build the synergy of government, financial institutions, the media, and other parties to promote high- quality development of enterprises. The development of green finance can help low-carbon city pilot policies play a positive role. Local governments should promote the design and planning of green finance policies in accordance with local economic development and resource endowment, speed up the improvement of the green finance system, guide financial institutions to increase the degree of support for enterprises’ green credit, and provide a favorable financing environment for enterprises’ low-carbon transformation. At the same time, relevant laws and regulations on green finance should be established and improved, requirements for tracking and supervision of the utilization of financial resources should be raised, supervision of financial institutions and implementation of relevant information disclosure systems for enterprises should be strengthened, so as to promote the real flow of funds to the green industry. In addition, attention should be paid to the positive role of external media governance in the process of low-carbon economic transition. Through the publicity of the concept of low-carbon sustainable development, stakeholders should pay more attention to carbon information and create a favorable public opinion atmosphere and market environment for the low-carbon transition of enterprises.
Limitations and Future Research Directions
There are also some limitations in this paper, which point out the direction for future research. Firstly, this paper has the limitation of sample representativeness. In this paper, the sampling method is convenient sampling, and the data is not obtained according to the strict random sampling procedure. Future studies need to use more samples to test the generality of the conclusions of this study. Finally, from the perspective of the integration of efficiency mechanisms and legitimacy mechanisms, some factors affecting economic efficiency can be added into the research model to be tested, so as to predict and explain financial development ion urban low- carbon transitions to green production transitions more effectively.

