

Introduction
After more than 40 years of development through reform and opening up, China has achieved certain economic achievements, but it has also brought about social problems such as ecological damage to the environment and the huge gap between the residents. After entering a new era, the Chinese government has put forward the concept of high-quality development, focusing on coordinating the relationship between economic development and ecological environment protection. It can be seen that the Chinese government regards high-quality development as an important goal. With the development of the economy, the Chinese government has also introduced a series of reforms to the tax collection and management system. A prominent and representative example is the application of modern technological means in the field of tax collection and management, which greatly compresses the space for enterprises to evade taxes. On the one hand, it guarantees government revenue and combats the tax evasion behavior of enterprises [1, 2]. On the other hand, it increases the tax burden on enterprises and is not conducive to improving their efficiency [3].
Under the centralized fiscal model, although local governments have a certain degree of fiscal autonomy, they lack leadership in tax rate formulation, tax incentives, tax supervision, and other policies and can only passively accept the policies of the central government [4]. “The Third Phase of the Golden Tax Project” is a far-reaching tax governance project led by the Chinese government that greatly improves the government’s tax collection and management capabilities through modern governance technologies and means. On the one hand, “the Third Phase of the Golden Tax Project” utilizes big data technology to obtain information on the upstream and downstream purchases and sales of goods by enterprises, providing a basis for data exchange between tax departments and other institutions such as customs and banks. On the other hand, “the Third Phase of the Golden Tax Project” can identify tax risks and cover all types of taxes, including value-added tax, corporate income tax, social insurance premiums, etc., achieving “full tax collection”. Previous literature studies have shown that “the Third Phase of the Golden Tax Project” improves the government’s tax management level and increases the tax burden on enterprises [5, 6]. Therefore, this article uses the launch of “the Third Phase of the Golden Tax Project” to enhance tax collection and management capabilities as an exogenous shock and constructs a double difference model to examine the impact of changes in tax collection and management capabilities on the green TFP of enterprises.
Existing literature on green TFP mostly focuses on provincial and industry levels [7-9]. Compared with existing literature, the contributions of this article mainly include: first, from a research perspective, different from simply studying the TFP of enterprises, this article starts from the perspective of tax collection and management, explores the impact on the green TFP of enterprises, and reveals the relationship between tax collection and management and the green and high-quality development of enterprises. Secondly, in terms of research methods, this article takes the implementation of “the Third Phase of the Golden Tax Project” as a quasi-natural experiment and uses differences-in-differences (DID) for causal identification, which to some extent solves the endogeneity problem in characterizing tax collection and management and corporate tax burden. Thirdly, in terms of research mechanisms, emphasis is placed on exploring the channels that affect green TFP from the perspectives of enterprise cash flow and green technology innovation, enriching the research on the mechanism level of enterprise green and high-quality development.
The rest of the paper is structured as follows: subsection Background and Theoretical Analysis introduces the background and research hypotheses. Experimental Procedures section describes the data, variables, and empirical specifications. Results and Discussion section presents the baseline results and robustness results, a heterogeneity analysis and mechanism analysis. Conclusions section concludes.
Background and Theoretical Analysis
Background
The Chinese government established a modern tax decentralization system through the “tax sharing system” reform in 1994. In order to maintain control over tax sources and the supervision of local governments, the state administration of taxation is responsible for the formulation of national tax policies and the informationization of the tax system. The collection and supervision of tax information can fully guarantee government fiscal revenue and achieve fiscal goals [1]. In order to strengthen the tax authority and information supervision of the central government, the state administration of taxation has established the “Golden Tax Project” to be implemented nationwide. From the 1990s to the present, it has gone through the improvement of “the First Phase of the Golden Tax Project”, “the Second Phase of the Golden Tax Project”, and “the Third Phase of the Golden Tax Project”. “The First Phase of the Golden Tax Project” originated in the 1990s and was piloted in more than 50 cities across the country, with a focus on information cross audit and comparison. However, due to limitations in tax management technology and information technology, the cross audit effect of “the First Phase of the Golden Tax Project” was significantly different from the actual situation, and the expected goals were not achieved. For this reason, “the Second Phase of the Golden Tax Project” was officially launched in 1998. Based on the first phase, the value-added tax general taxpayer anti-counterfeiting tax control system was added, and a more powerful value-added tax audit system was established. The comparison of value-added tax special invoices was achieved. This project was launched nationwide in 2001 and greatly cracked down on tax evasion and strengthened tax collection and management. With the advent of the internet era, tax collection and management have become increasingly complex, which puts forward higher requirements for tax authorities. “The Second Phase of the Golden Tax Project” is difficult to meet the requirements of tax modernization. On this basis, the state administration of taxation has promoted the construction of “the Third Phase of the Golden Tax Project”, promoting the modernization of tax collection and management technology through big data, cloud computing, and other means, and achieving full coverage of tax supervision. Firstly, the technical ability and level of tax collection and management have been greatly improved, filling the previous loopholes and accurately recording the entire process of production, exchange, and distribution of taxpayers, thereby achieving supervision of taxpayers. Secondly, the tax categories are no longer limited to the supervision of value-added tax, but cover all tax categories and can intelligently analyze tax risks and identify suspicious enterprises. Thirdly, the latest golden tax project covers both national and local tax systems, facilitating tax authorities to grasp taxpayer information and enabling the exchange of tax intelligence.
Table 1.
Implementation Time of “the Third Phase of the Golden Tax Project”.
The construction of “the Third Phase of the Golden Tax Project” follows the requirements of “one platform, two levels of processing, three coverage, and four systems” and is gradually implemented nationwide, ultimately establishing a modern tax platform at the national level. The detailed implementation timeline of “the Third Phase of the Golden Tax Project” is shown in Table 1, which can be roughly divided into three stages. The first stage is the initial stage from 2013 to 2014, and “the Third Phase of the Golden Tax Project” has started pilot implementation in Chongqing, Shandong (excluding Qingdao), Shanxi, and other regions. The second stage is the promotion phase from 2015 to 2016, which began to be promoted and launched in Guangdong (excluding Shenzhen), Henan, Inner Mongolia, and other regions. The final stage is nationwide promotion. In 2017, “the Third Phase of the Golden Tax Project” was launched nationwide, achieving nationwide coverage. The implementation of “the Third Phase of the Golden Tax Project” provides a quasi-natural experiment by gradually piloting and successively launching, providing us with a good opportunity for causal identification research.
Theoretical analysis
The promotion and application of “the Third Phase of the Golden Tax Project” have established a rigorous tax collection and management information system nationwide and facilitated tax supervision by tax authorities. In China, the central government dominates the decision-making power of tax policy formulation and is the leading institution for tax collection and management policies, while local governments have the goal of achieving high-quality development of enterprises. The central government is more concerned about whether tax revenue is paid and stored in a timely manner. Local governments are to some extent concerned about the environmental emissions and energy losses of enterprises, which are closely related to their green TFP.
Existing studies suggest that an increase in tax burden will suppress the environmental demand and TFP of enterprises, while tax policies, especially green ones, will promote the improvement of the green TFP of enterprises. From an intuitive perspective, the increase in tax collection and management intensity directly increases the tax burden on enterprises, reduces their capital investment and retained earnings, and lowers their green TFP. From another perspective, enterprises have a self-selection effect. Under the condition of increasing tax intensity, enterprises will reduce cash flow, lower equilibrium price levels, and even exit the market, resulting in a decrease in green TFP [10].
Hypothesis 1: The implementation of “the Third Phase of the Golden Tax Project” has strengthened tax collection and management, increased the tax burden on enterprises, and thus reduced their green TFP.
With the implementation of “the Third Phase of the Golden Tax Project”, the tax burden on enterprises will increase, and the internal funds retained by enterprises will decrease, leading to a cash flow crisis. Enterprises are more cautious about production, operation, investment, and green and environmentally friendly production [11]. The strengthening of tax collection and management has weakened the internal financing constraints of enterprises. With the aggravation of tax collection and management penalties, the probability of enterprises being punished greatly increases, which will lower their credit rating and increase their external financing costs [12], and these are important factors that inhibit the green TFP of enterprises.
Technological progress is the driving force behind enterprise innovation and can achieve economic growth [13]. After the government increases its tax collection and management efforts, on the one hand, enterprises will pay more taxes, thereby reducing investment in the fields of technological innovation and environmental protection, resulting in a decrease in green innovation. On the other hand, due to concerns about the tax environment, companies tend to lean towards conservatism in production, operation, and technological progress, while green technology investment tends to change. Some scholars believe that after the launch of “the Third Phase of the Golden Tax Project”, the government’s tax collection and management capabilities will be significantly strengthened, and enterprises will reduce their investment in research and development, resulting in a decrease in research and development investment and output levels [14]. Technological progress, especially green technology innovation, is an important factor affecting the green productivity of enterprises, resulting in a mismatch in factor endowments and cutting-edge technologies between developed and underdeveloped economies [15, 16].
Hypothesis 2: “The Third Phase of the Golden Tax Project” reduces the TFP of enterprises by reducing their cash flow and inhibiting green technology innovation.
Experimental Procedures
Data Source
This article uses macro and micro matching panel data from 2010 to 2019, with micro enterprise data sourced from the Guotai An CSMAR database and macro data sourced from the China City Statistical Yearbook. Due to the launch of “the Third Phase of the Golden Tax Project” from 2013 to 2017, the sample period selected in this article fully covers the implementation time of this progressive reform. Furthermore, this article processed the data samples as follows: (1) Due to the particularity of the financial and insurance industries, financial and insurance companies were excluded; (2) Companies with ST, * ST, and SST stocks were excluded. (3) Samples of listed companies with missing data were excluded. A non-equilibrium of panel data containing 24017 samples was finally obtained through screening.
Green TFP
This article draws on the method of Oh and Heshmati (2010) and uses the SBM-DDF model to calculate the green TFP of enterprises using the GML index [17]. Capital input is estimated using the perpetual inventory method; labor input is measured by the number of employees at the end of the year; and energy input is obtained by multiplying the operating cost of the enterprise with the industry cost and the total energy consumption of the industry. The expected output is measured based on the enterprise’s operating income. The unexpected output is calculated based on the annual report of China’s ecological environment statistics, selecting sulfur dioxide emissions, chemical oxygen demand, and solid waste generation with the highest proportion of industrial production emissions in air pollution. The principle is the same as energy input. This article selects the OP method as the benchmark regression core method to measure green TFP and uses methods such as LP, FE, OLS, and GMM to measure green TFP as a robustness test.
The Third Phase of the Golden Tax Project: “the Third Phase of the Golden Tax Project” is used to measure the impact of changes in tax collection and management intensity on the green TFP of enterprises. When region j goes online in year t, it is recorded as 1, otherwise it is 0.
Control Variables
This article controls for a series of enterprise characteristic variables, including enterprise size, enterprise age, enterprise asset liability ratio, and Tobin Q value. At the same time, in order to control for the impact of regional economic and social development differences, this article controlled for a series of variables at the regional level, including per capita GDP, the proportion of secondary output value to GDP, the proportion of tertiary output value to GDP, and the natural population growth rate.
Table 2.
Summary statistics.
Empirical Strategy
Due to the implementation of “the Third Phase of the Golden Tax Project” on an annual basis and the heterogeneity at the time and regional levels, this article constructs a staggered DID to identify the impact of improving tax collection and management capabilities on the green TFP of enterprises. The specific empirical model is as follows:
Among them, GreenTFPijt represents the green TFP of the enterprise, subscript i represents the enterprise, j represents the regional level, and t represents time. GRPjt represents the dummy variable for the launch of “the Third Phase of the Golden Tax Project”. When region j goes online in year t, it is recorded as 1, otherwise it is 0. Xijt represents a collection of control variables, which includes control variables at the enterprise level, such as enterprise size, enterprise age, asset liability ratio, etc., as well as control variables at the regional level, such as the logarithm of per capita GDP and the proportion of the secondary industry to GDP. This article controls firm fixed effects, city fixed effects and year fixed effect. Among them, the coefficient β measures the effectiveness of the implementation of “the Third Phase of the Golden Tax Project” and reflects the impact of changes in tax collection and management capabilities on the green TFP of enterprises.
Results and Discussion
Baseline Results
This article focuses on examining the impact of changes in tax collection and management policies represented by “the Third Phase of the Golden Tax Project” on the green TFP of enterprises. Table 3 presents the baseline results, where columns (1) - (3) represent the green TFP measured by the OP method, while column (4) represents the green TFP measured by the LP method. In column (1), if we don’t add other control variables, we can find that the regression coefficient of the core explanatory variable is negative and significant at the 1% confidence level, indicating that the increase in tax administration intensity reduces the green TFP of enterprises. In column (2), variables at the enterprise level are controlled, and in column (3), all control variables at the enterprise and regional levels are controlled. We find that the regression coefficient of the core explanatory variable is still negative. After incorporating the green TFP calculated using the LP method in column (4) into the regression model, the basic conclusion remains unchanged. In baseline regression, we control for fixed effects at the individual, regional, and temporal levels of enterprises and cluster standard errors at the industry level. In summary, whether it is the OP method or the LP method, “the Third Phase of the Golden Tax Project” significantly reduces the green TFP of enterprises, and the increase in tax collection and management intensity is not conducive to the high-quality development of enterprises.
Table 3.
Baseline regression results.
Parallel Trend Test
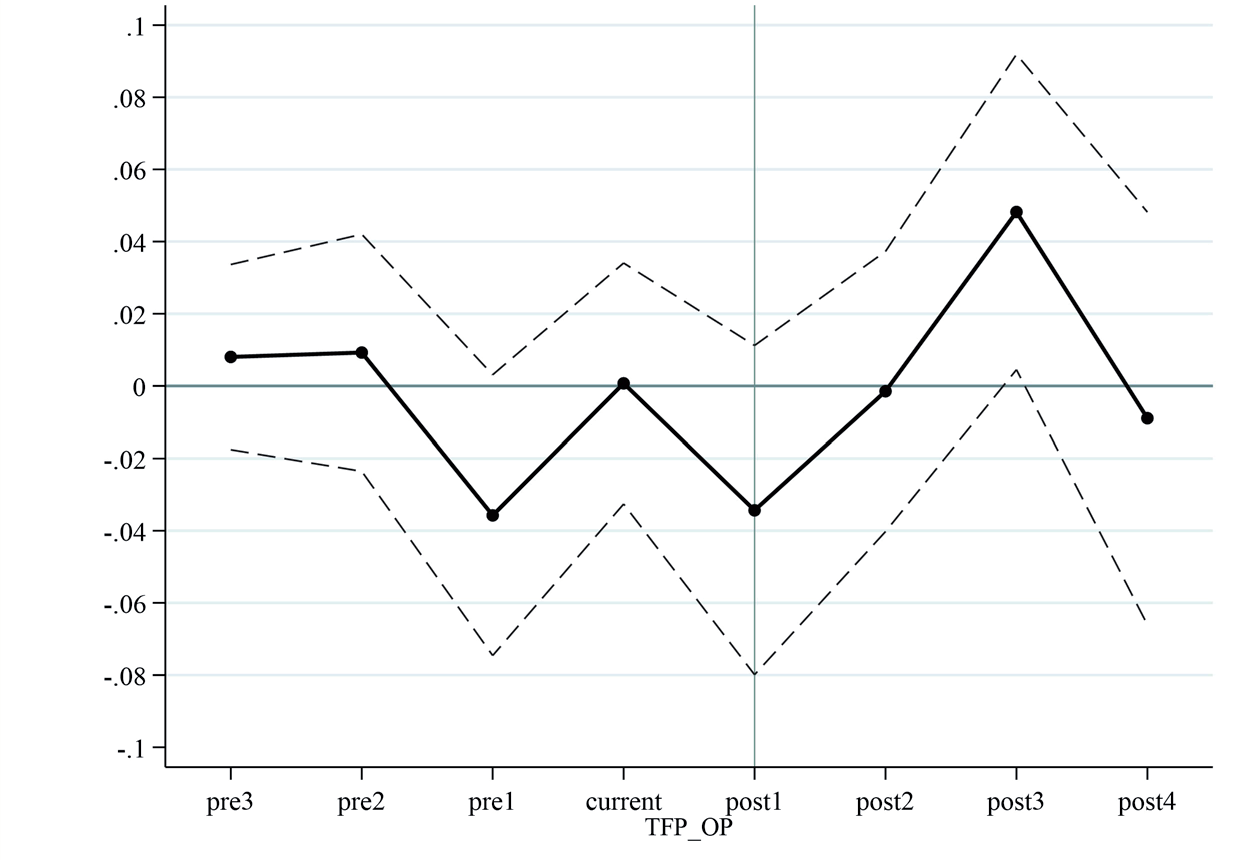
The estimation results of DID need to meet the parallel trend of the treatment group and the control group before being affected by policy shocks. In order to verify the parallel trend, this paper uses the method of Jacobson et al. (1993) to introduce dummy variables for testing [18]. The model is constructed as follows:
Among them, eventj represents the relative year of policy implementation. The variable event0 for the year when “the Third Phase of the Golden Tax Project” is launched is assigned a value of 1 in the year when “the Third Phase of the Golden Tax Project” is launched, and the other values are assigned 0. The variable event1 for the year when “the Third Phase of the Golden Tax Project” is launched is assigned a value of 1 in the year after “the Third Phase of the Golden Tax Project” is launched, and the other values are assigned 0. The definition of other variables is the same as benchmark regression. Fig. 1 shows the estimated value and 90% confidence interval of βj. It can be seen that the coefficient of the interaction term before the launch of “the Third Phase of the Golden Tax Project” is not significantly different from 0, indicating that the treatment group and the control group meet the parallel trend test, indicating that the benchmark regression results in this article are reliable.
Placebo Test
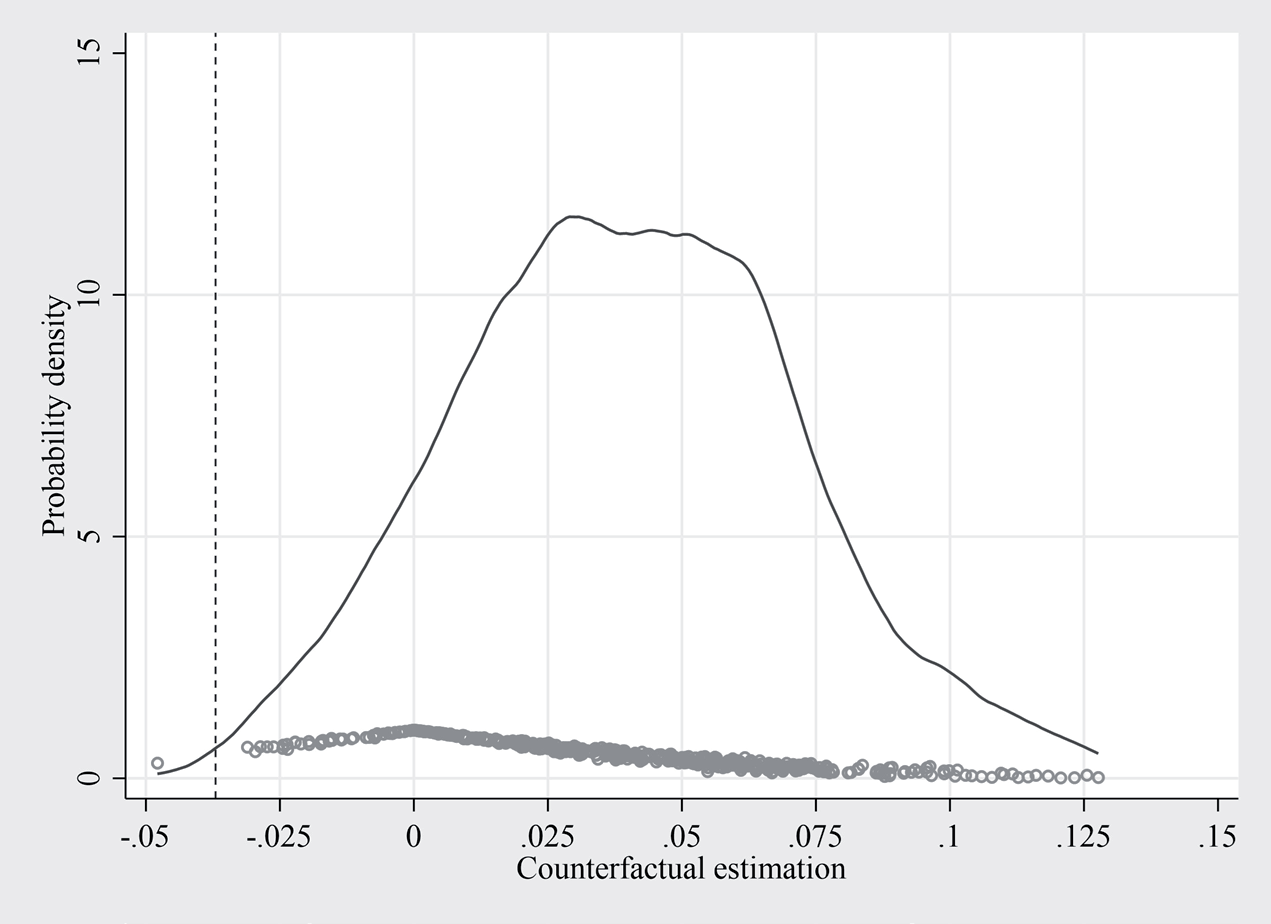
In order to further verify whether the results of this article are influenced by other unobservable factors, following the approach of Cai et al. (2016) [19], the time and region for the launch of “the Third Phase of the Golden Tax Project” were randomly assigned, virtual policy variables were set, and 500 reversals were repeated on this basis. As shown in Fig. 2, the solid lines in the figure represent the density distribution of the pseudo-regression, and the dots represent the p-value corresponding to the estimated coefficients. The vertical dashed line is the true regression result estimated by the DID model, with a value of -0.037. It can be seen that the majority of p-values are greater than 0.1. The true estimated value of the DID model is an obvious outlier, indicating that the policy implementation effect is significantly different from the placebo effect. “The Third Phase of the Golden Tax Project” tax collection and management policy is the reason for the decrease in green TFP among enterprises.
Robustness Tests
First, we test the robustness of green TFP. Although OP and LP methods have been used in previous empirical studies to measure green TFP as the dependent variable, in order to ensure the reliability of the baseline regression results in this article, multiple methods such as OLS, FE, and GMM will continue to be used to confirm each other. The results of the green TFP measured by OLS, FE, and GMM methods are reported in columns (1) - (3) of Table 4, respectively. It can be seen that the regression results are still significantly negative, consistent with the baseline regression results, indicating that changing the method of enterprise green TFP as the dependent variable will not affect the conclusion of this article.
Second, we changed the level of clustering standard error. The baseline regression results of this article cluster standard errors at the industry level. In order to obtain reliable and consistent conclusions, this article attempts to cluster standard errors at the city level. The results are reported in column (4) of Table 4, and the regression coefficient is -0.037, which is significant at a 5% confidence level, indicating the robustness of the benchmark regression results.
Finally, we add the stricter fixed effects. The implementation period of “the Third Phase of the Golden Tax Project” coincided with the deepening reform of China’s tax policies and systems. Some local governments and industry regulatory units have introduced a series of tax-related policies or related policies that affect the green development of enterprises. In order to eliminate the impact of these possible policies to a greater extent and obtain more accurate estimation results, this article controls the interaction term between regions and the industry in which enterprises operate to capture regional factors. The impact of industry policies on the regression results is shown in column (5) of Table 4. It can be seen that the regression conclusion is still robust, indicating that the results of this article are not due to regional or industry policies.
Table 4.
Robustness Test.
Heterogeneity Analysis
Heterogeneity of Enterprise Characteristics
The performance of tax administration on green TFP may vary among enterprises of different characteristics. Based on the enterprise characteristics, this article divides the sample into state-owned enterprises and non-state-owned enterprises. The regression results are shown in Table 5, where columns (1) and (3) show the regression results of the non-state-owned enterprise sample, and columns (2) and (4) show the regression results of the state-owned enterprise sample. It can be seen that although the regression results of the non-state-owned enterprise sample are negative, they are not significant. The regression results of the sample of state-owned enterprises are significantly negative. On the one hand, compared to state-owned enterprises, non-state-owned enterprises face less competition and have a lower willingness to promote high-quality development. Therefore, in the context of strengthened tax collection and management, it is even more detrimental to the green development of enterprises. On the other hand, state-owned enterprises need to follow the law by example. After tax supervision is strengthened, state-owned enterprises need to pay more resources and taxes, thereby reducing the overall green productivity of enterprises.
Heterogeneity of Enterprise Location
Different regions of the enterprise may have differential impacts. This article divides the enterprise sample into coastal enterprises and inland enterprises. The regression results are shown in Table 6, where columns (1) and (3) show the regression results of the inland area cities, and columns (2) and (4) show the regression results of the coastal area cities. It can be seen that although the regression results of the inland cities are negative, they are not significant. The regression results for the coastal cities are significantly negative. On the one hand, coastal cities are economically active and also high-risk areas for tax evasion. Once tax authorities increase their tax collection and management efforts, enterprises in the region will be greatly affected, reducing green TFP. On the other hand, compared to inland cities, enterprises in coastal cities have higher green productivity. Under the influence of tax policies, coastal cities experience significant fluctuations, leading to a decrease in green TFP.
High Tech and Non High Tech Enterprises
Whether a company is in a high-tech industry or not may also vary. This article divides the sample into non high-tech enterprises and high-tech enterprise samples based on whether the enterprise belongs to the high-tech industry. The regression results are shown in Table 7, where columns (1) and (3) are the regression results of the non high-tech enterprise sample, and columns (2) and (4) are the regression results of the high-tech enterprise sample. It can be seen that the regression results of high-tech enterprises are not significant. The regression results for non high-tech enterprise samples are significantly negative. On the one hand, the Chinese government has “flexible tax collection and management” in actual tax collection and management, often providing many tax incentives and concession policies for regional high-tech enterprises. These policies prevent these high-tech enterprises from being affected by strong tax collection and management policies. On the other hand, non high-tech enterprises face stronger financing constraints, and financial institutions such as banks and securities are less willing to lend to non high-tech enterprises, resulting in a decrease in the green TFP of enterprises in the context of strong tax collection and management.
Table 5.
Heterogeneity Results of Enterprise Characteristics.
Table 6.
Heterogeneity results of enterprise geographical location.
Table 7.
Heterogeneity results of high tech and non high tech enterprises.
Mechanism Analysis
According to the previous research hypothesis, the impact of tax collection and management on the green TFP of enterprises is mainly tested from two aspects: enterprise cash flow and technological innovation.
Corporate Cash Flow
The adequacy of a company’s cash flow directly determines the amount of funds it can use in the short term, which has a crucial impact on its production, operation, and high-quality development. If the proportion of cash in a company’s assets is high, it indicates that the company will have more capital investment and production turnover, which can promote the improvement of green TFP. Therefore, this article uses the proportion of cash flow in enterprise production and operation activities to total assets as an indicator to measure enterprise cash flow, in order to test the impact of changes in tax collection and management intensity on enterprise cash flow and whether it affects green TFP.
Among them, cflowijt represents the cash flow of the enterprise, and other variables are consistent with the benchmark regression model. If the regression coefficient β1 is significantly negative, it indicates that strengthening tax collection and management has led to a decrease in enterprise cash flow, thereby reducing green TFP. The empirical results in columns (1) - (2) of Table 8 indicate that the strengthening of tax collection and management marked by “the Third Phase of the Golden Tax Project” has significantly reduced the cash flow of enterprises, which is one of the channels leading to a decrease in TFP for enterprises.
Green Technology Innovation Effect
Green technology innovation is an important means to stimulate the growth of green TFP. If the green technology innovation of enterprises continues to increase, it is obvious that green TFP will also continue to rise. Green technology innovation requires enterprises to produce innovative products that meet both the requirements of new technologies, new products, and new methods, as well as the requirements of green environmental protection rules. These require enterprises to invest a large amount of funds and technology. In the context of strengthened tax collection and management, enterprises will reduce their R&D investment and funding for “high, new, and cutting-edge” innovations, thereby lowering the level of green technology innovation. To verify this, this article uses the amount of green patent application authorization by enterprises as a measurement standard to examine the impact of the implementation of “the Third Phase of the Golden Tax Project” policy on the green innovation effect of enterprises.
Among them, ln patentsijt represents the logarithm of the green patent authorization amount of the enterprise, and other variables are consistent with the baseline regression model. If the regression coefficient β1 is significantly negative, it indicates that strengthening tax collection and management reduces the green technology innovation of the enterprise, thereby reducing the green TFP. The empirical results in columns (3) - (4) of Table 8 indicate that the strengthening of tax collection and management marked by “the Third Phase of the Golden Tax Project” significantly reduces the level of green innovation of enterprises, which also confirms the hypothesis of this article.
Conclusion
The high-quality development of Chinese enterprises is closely related to the government’s tax policies. This article analyzes the impact of changes in tax collection and management on the green TFP of enterprises through the quasi-natural experiment of “the Third Phase of the Golden Tax Project” implemented by the central government’s tax regulatory department and explores the mechanisms involved. The research conclusion is as follows: (1) The implementation of “the Third Phase of the Golden Tax Project” has suppressed the growth of green TFP in enterprises, and the results are still significant after adding more control variables and a series of robustness tests. (2) In heterogeneity analysis, the changes in tax collection and management intensity brought about by “the Third Phase of the Golden Tax Project” have a more significant effect in samples such as state-owned enterprises, coastal area enterprises, and non high-tech industry enterprises.
(3) The mechanism analysis results indicate that “the Third Phase of the Golden Tax Project” suppresses the high-quality development of enterprises by reducing their cash flow in production and operation activities and lowering the impact of green innovation channels on green TFP.
The research conclusion of this article contains important policy implications. One is to standardize the level of tax collection, management, and law enforcement and prohibit local governments from imposing excessive taxes on enterprises in order to complete their tasks. In order to complete tax tasks, some governments in certain regions use modern tax collection and management methods to collect higher taxes from enterprises, resulting in a significant increase in enterprise tax burden and an increase in tax burden pain index, which is not conducive to the green and healthy development of enterprises. While using modern tax collection and management technology, they also need to provide tax incentives and services, release policy dividends for enterprises, and promote a fair and just market environment. The second is to provide strong tax policy support for the transformation of enterprise scientific and technological achievements and the development of green environmental protection. Independent innovation and green development are necessary paths for enterprises to improve their green TFP. Therefore, the government should use modern technologies such as big data and cloud computing to provide technical support for the transformation of scientific and technological achievements and the green development of enterprises. At the same time, supporting tax policies should be formulated to encourage enterprises to achieve green and high-quality development. The third is that the government should adopt a mixed strategy of environmental regulation and incentives to promote the green development of enterprises. Reduce high energy consuming, highly polluting, and high emission enterprises, as well as increase energy consumption and environmental standards, increase tax subsidies for energy and high-tech enterprises, and force enterprises to carry out green technology innovation and green product innovation, thereby improving green TFP.
Table 8.
Mechanism Analysis Results.

