

Introduction
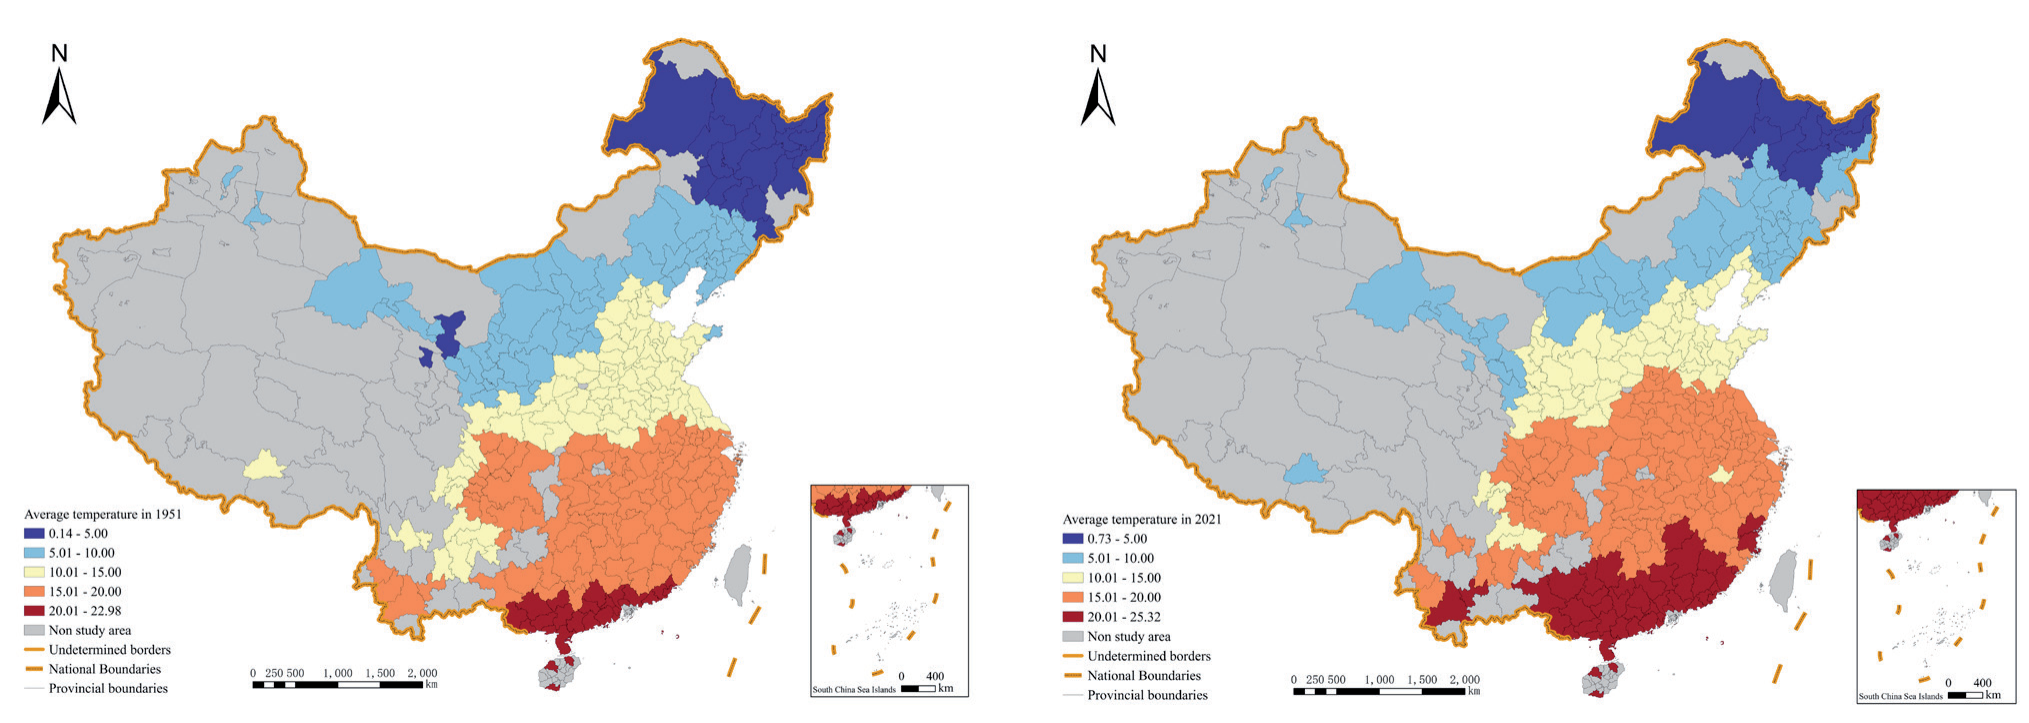
Global warming is among the most important threats that today’s society is facing [1]. In 2021, the global average temperature was found to be 1.11ºC higher than the average temperature during the pre-industrial period (1850-1900) [2]. Such an increase in temperature is expected to intensify greenhouse gas emissions [3], thus magnifying climate risk. This global warming-greenhouse gas emissions relationship was proven to have adverse consequences on sustainable development, namely on natural ecosystems, economy, and society [4]. More specifically, global warming is increasing the sea level and the frequency of extreme climate events and is altering precipitation patterns [5]. Despite the negative effects of global warming on the production environment, global warming seems to prevail and even increase in amplitude, especially in China. For instance, in 2021, China’s warming rate was found higher than the global average, and the latter was classified among the most sensitive areas to climate change [2]. Moreover, the Blue Book on Climate Change in China (2022) highlighted an increasing trend of the annual average surface temperature in China from 1951 to 2021 (see Fig. 1), within a warming rate of 0.26ºC per 10 years (the global average is about 0.15ºC per 10 years). The highest increase was observed during the last 20 years amplifying the frequency and intensity of extreme climate events [2]. Such externalities in the production environment harm all economic activities, including the agricultural sector which is one of the basic industries of the Chinese economy [6]. Since agricultural activities are land and water-based, they are the most sensitive and vulnerable to climate risk [7]. Ray et al. argued that any degree of climate risk would impact agricultural production (eg. a decrease in the yield of crops), especially extreme climate events [8]. Therefore, climate risk is expected to threaten global food security and lead to socioeconomic challenges [9].
More than 35.30% of the total population in China lived in rural areas in 2021 [10]. Since the nineties (the period of reform and opening up), the income level of Chinese farmers has been increasing steadily. This was associated with a significant decrease in the incidence of poverty in rural areas and the eradication of absolute poverty in rural areas1. However, the urban-rural gap prevails and magnifies as the per capita disposable income of urban residents (7,349 USD in 2021) was about 2.5 fold to that of rural residents (2,934 USD in 2021) [10]. Furthermore, there is also a gap within rural areas which leads to social problems [11]. Statistics show that the per capita disposable of 20.00 % of rural high-income households is 8.87 times that of 20% of low-income households [12]. Unfortunately, climate risk is expected to increase the intra-rural gap and poverty gap as it affects the most poorest households [13] and can even drive households back to poverty [14]. Therefore, it is of great significance to understand and investigate the effect of climate risk on the income of farmers by understanding the direct relationship between climate risk and the income of farmers. Further analysis is also needed regarding the possible paths that could trigger sustainable and stable growth of the income. More specifically, this paper aims to study the effect of climate risk on the income of farmers and to understand the contribution of digital inclusive finance in mitigating the effect of climate risk on the income of farmers. Such analysis is also expected to prevent the increase of climate-induced poverty in rural areas and the climate-induced income gap.
To achieve our objective, we used panel data from 288 prefecture-level cities2 in China from 2011 to 2020 to understand the relationship between climate risk and the income of farmers. A fixed-effect and unconditional quantile model was used to estimate the direct effect of climate risk on the income of farmers. A regulatory effect model was used to verify the role of digital inclusive finance in mitigating the effect of climate risk on the income of farmers. We found that climate risk has a negative and significant effect on the income of farmers. One unit increase in climate risk is expected to decrease the income of farmers by 0.021. Furthermore, the effect of climate risk on income varies according to the income level of the farmers, geographical localization, and level of agricultural insurance. Finally, the mechanism analysis shows that digital inclusion finance, depth of use, and degree of digitization of finance sectors play a moderating role in the effect of climate risk on the income of farmers.
Most of the research on climate risk and the agricultural sector focuses on the technical aspects, research linking climate risk, the income of farmers, and financial services is lacking or focusing on the traditional finance system. This paper contributes to the existing literature by providing a more detailed analysis of the relationship between climate risk and the income of farmers. We investigated the importance of agricultural insurance in mitigating the effect of climate risk on the income of farmers when most literature only seeks to understand its regional heterogeneity caused by the difference in temperature of each region [15]. Moreover, this paper proposes an in-depth investigation of the role of digital inclusive finance in mitigating the effect of climate risk on the income of farmers when existing literature focuses on the traditional financial system [16]. Finally, this paper put forward new strategies to mitigate the effect of climate risk, improve farmers’ adaptability to climate risk, and increase the income of farmers.
Fig. 1.
Average temperature change in China between 1951 and 2021. Source of base map: National Platform for Common Geospatial Information Service Standard Map Service System (http://bzdt.ch.mnr. gov.cn) 1: 22 million standard maps, review number GS (2022) 1873, with no modifications to the base map.
The remainder of this paper is organized as follows. In section 2, we provided a literature background supporting why the research is important. In section 3 is about theoretical analysis. The Materials and Methods used for this research are all presented in section 4. In section 5, we return the results of the relationship between climate risk and the farmers’ income level. Finally, section 6 presents the policy implication of this work and concludes the paper.
Literature Review
With the continuous intensification of global warming, scholars give increasing attention to climate risk. Previous research provided evidence of the negative effect of climate risk on the income of farmers [17]. Specifically, climate risk alters the production system and the layout of crops, reduces yield, and disturbs the cropping calendar [18] which results in a reduction of income of farmers. As an example, in China, climate risk shifted the planting area to the north and increased the adoption of multi-cropping systems [19]. Earlier studies on agricultural sciences proved that climate risk reduced yield as it degraded soil characteristics (water retention), reduced crop quality (composition in protein, mineral, and lipid and nutrient composition [20]), and increased pest and plant disease frequency [21]. Moreover, the effect of climate risk on crop yield was found different according to region, crops, and production environment [22]. Global warming also harms livestock as high temperatures and cold weather reduce their productivity (eg. milk, eggs), feeds, and resistance to diseases [23], thus the income of farmers. Rezai et al. and Akbari et al. argued that greenhouse gas emissions reduced income levels [24, 25]. Previous literature found that extreme climate events decrease productivity, thus trapping farmers in poverty and driving back other farmers into poverty [26]. Earlier studies showed that high temperatures and low precipitation reduced the income of farmers and magnified rural poverty [27]. A more detailed approach found that climate risk reduces labor hours [28] and labor productivity [29], thus the income of farmers. However, in the 20s, Bobojonov et al.’s findings highlighted that the effect of climate risk on the income of farmers may differ according to the type of farm size [30]. More specifically, large commercial farms may benefit from climate risk, when small farmers are negatively impacted.
The evidence of the negative effect of climate risk on economic activities urges policymakers to generate global strategies to reach various environmentally sensitive targets. Strategies go from mitigation strategies (to reduce greenhouse gas emissions or increase the exploitation of eco-friendly crops) [31] to adaptation strategies that improve the ability of producers to cope with climate risk. Since mitigation strategies require behavioral change, long-term investment, knowledge sharing, etc. [32], adaptation strategies are more likely to be effective in controlling the negative effect of climate risk on the income of farmers [33, 34]. However, the lack of capital and skills of small-scale farmers limits their adaptation to climate risk [16]. Therefore, small-scale farmers face a vicious cycle since financial exclusion in rural areas has been limiting their capital, thus inhibiting the positive effect of credit on adaptation strategies [14]. Therefore, the chain reaction of climate shock, loss of assets and collateral value, increasing default risk, financial exclusion, and lack of credit [35] is not broken trapping small-scale farmers into poverty. Nevertheless, digital finance is an alternative to breaking this chain. Digital inclusive finance reduces financial exclusion in rural areas by reaching remote areas, reducing travel time, reducing service costs, and alleviating information asymmetry [36].
Theoretical Hypothesis
Agricultural activities are climate-related activities [37] (heat, light, and water), therefore, climate risk is expected to affect agricultural productivity and the income of farmers. In an attempt to reduce the negative effect of climate risk on their income, farmers adopt various adaptation strategies [38]. Adaptation strategies include growing alternative crops, using alternative cropping systems (eg. rotation), strengthening the production system, and increasing investment in climate disaster prevention. However, these methods increase production costs [39] and potentially reduce the income of the farmers. Besides, extreme events harm productivity [40] which further reduces income. Systematically, a decrease in productivity increases the price of crops, however, the price increase is not enough to overcome the negative effect of climate risk on the income of farmers. This leads to the following hypothesis.
Hypothesis H1: Climate risk harms the income of farmers.
The effect of climate risk on income level may differ according to the income level of farmers. Since low-income farmers rely more on the production environment, they are more vulnerable to climate risk [13]. Furthermore, the adverse effects of climate risk may drive some farmers back to poverty [41]. However, wealthier farmers have higher capital and can invest more in adaptive strategies increasing their resistance to climate risk [16]. Therefore, the income gap between households in rural areas is continuously increasing [42]. The following hypothesis is generated.
Hypothesis H2: Climate risk increases the income gap among rural farmers.
Digital inclusive finance has an adjustment mechanism on the effect of climate risk on the income of farmers. For instance, digital inclusive finance combined with information technology and big data can alleviate poverty by solving financial exclusion, and alleviating information, cost, and mortgage constraints [43]. Therefore, digital inclusive finance improves farmers’ response to risk, upgrades the technology they use, and increases non-agricultural employment in rural areas. These three aspects are expected to mitigate the negative effect of climate risk on the income of farmers. First, scholars found that the lack of responsiveness to risks and the relatively low resilience of farmers to climate risk reduce the income of farmers [44]. Since most vulnerable populations are excluded from the traditional financial system, they have no choice but to use informal channels [45]. However, informal finance systems have shadow costs and are not effective when it comes to sharing risk. Moreover, informal finance systems harm social status and reputation [46], thus limiting the income of farmers [17] and improving the probability of vulnerable populations falling back into poverty [47]. However, the actual lack of capital in rural areas limits the adoption of new technologies [48]. Therefore, this study suggests that digital inclusive finance contributes to reducing financing constraints, thus upgrading the technology used by farmers and reducing the negative effect of climate risk on the income of farmers. Finally, climate risk increases the living costs in rural areas which incites farmers to seek non-agricultural employment. Previous findings highlighted the positive relationship between non-agricultural employment, financial service, and climate risk mitigation [36]. For instance, non-agricultural employment can promote the integration of rural fragmented land, upgrade the production system, reduce agricultural emissions, and reduce the negative effects of climatic events. However, going from agricultural activities to non-agricultural ones has a high cost which is too expensive for the most vulnerable population [49]. Therefore, this study suggests that digital inclusive finance can facilitate the transition from agricultural activities to non-agricultural activities. Digital inclusive finance can support the expansion of business and upgrade industries which generate new employment opportunities for rural migrant labor. These non-agricultural opportunities are expected to reduce the negative effect of climate risk on the income of farmers. These lead to the final hypothesis.
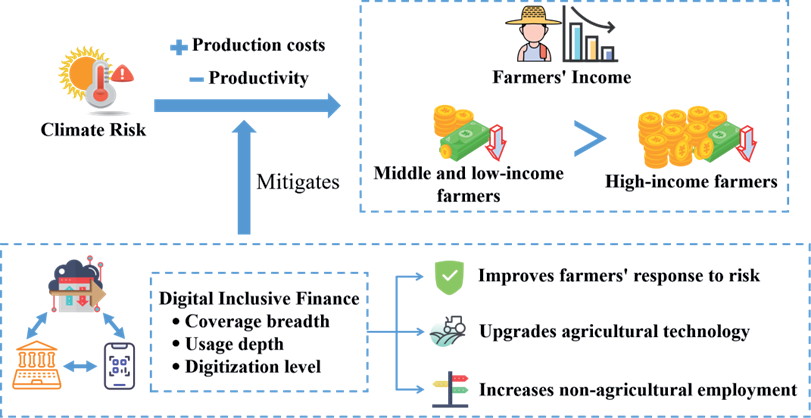
Hypothesis H3: Digital inclusive finance can mitigate the negative effect of climate risk on the income of farmers.
The analysis framework constructed in this study is shown in Fig. 2.
Materials and Methods
Data Sources
The historical temperature data in this paper was from the National Meteorological Science Data Center of China3. This database contains daily meteorological observation records of 824 meteorological monitoring stations. Digital inclusive finance-related data are from the Digital Finance Research Center of Peking University and socio-economic-related data are from official statistical yearbooks (China Urban Statistical Yearbook, China Rural Statistical Yearbook, and National Economic and Social Development Statistical Bulletin4). We collected panel data from 288 prefecture-level cities in China from 2011 to 2020.
Model Construction
Benchmark Regression Model
This research used a fixed effect model to estimate the effect of climate risk on the income of farmers (Equation 1) [50, 51].
Where:
– Lninci,t is the income of farmers in i at time t;
– Tempi,t is the climate risk variable in i at time t, with
– Xi,t is a group of control variables in i at time t, including agricultural fertilizer use (LnFui,t), agricultural machinery power (LnAmpi,t), expenditure on agriculture, forestry and water affairs (LnAfwei,t), human capital level (Hci,t), industrial structure upgrading (Isui,t), economic development level (Lnpgdpi,t), Trade openness (Toi,t);
– θi is the urban fixed effect of i to reduce endogenous problems;
– λt is the time-fixed effect at time t to absorb the impact of common regional trends and fluctuation; and εi.t is a random disturbance item.
Regulatory Effect Model
To investigate the possible relationship between climate risk, the income of farmers, and digital inclusive finance, we used the regulatory effect model proposed by Baron and Kenny [53] (Equation 2):
Where:
difi,t is the digital inclusive finance variable of i at time t, representing the interaction term between climate risk and digital inclusive finance. Note that in this section, we also used coverage breadth (difcbi,t ), usage depth (difudi,t ), and digitization level (difdli,t ) to proxy digital inclusive finance (difi,t ).
Variable Selection
Explained Variable
This paper used per capita net income of rural residents to proxy the income of farmers. Since 2014, the National Bureau of Statistics has no longer provided per capita net income data for rural residents, but instead replaced it with per capita disposable income for rural residents. So the rural per capita net income was used from 2011 to 2013 and the rural per capita disposable income was used in the rest of the study period (starting from 2014).
Explanatory Variable
According to the definition provided by the “Working Group on Climate Related Financial Information Disclosure” (TCFD, 2017), climate risk refers to the social, economic, and financial risks caused by climate factors such as extreme weather, natural disasters, and global warming. Climate risk is believed to disadvantage sustainable development, in particular, global warming which has the greatest effect on the natural ecosystem [54]. Therefore, this study used climate warming risk (hereinafter referred to as climate risks) as an explanatory variable. To proxy climate risk, this paper used the absolute value of temperature difference within 3 years [51] (Equation 1).
Adjusting Variable
This paper used the Peking University Digital Inclusive Finance Index compiled by the Peking University Digital Finance Research Center and Ant Financial Services5 to proxy the development level of digital inclusive finance. The index includes three sub-dimensions: the coverage breadth of digital finance, the usage depth of digital finance, and the digitization level of inclusive finance. To run the model we used the total digital inclusive finance index, as well as the three sub-dimensions sub-index mentioned above. It is worth noting that the income of farmers is impacted by other variables than climate risk. Therefore, this paper used a series of control variables to control for the possible impact of these factors on the income of farmers (Table 1).
Table 1.
Variable definitions.
Results and Discussion
Descriptive Statistics
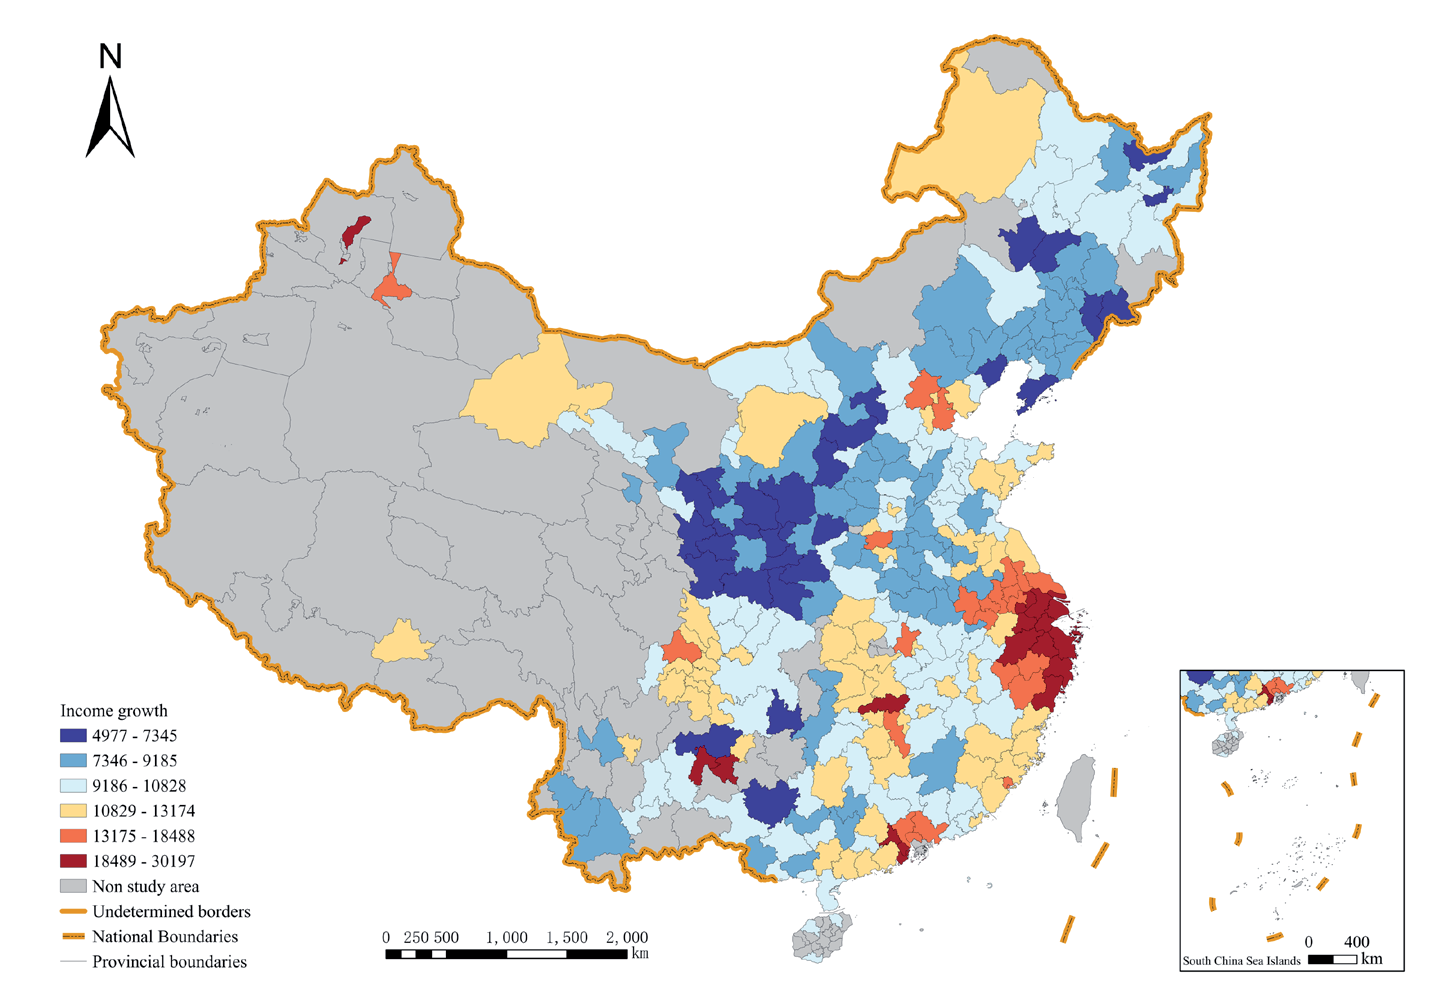
Over the past decade, farmers’ income has generally increased (see Fig. 3). But Table 2 shows that the standard deviation of the income of farmers (Lninci,t) was about 0.410, this indicates an income gap between cities. The average value of climate risk (Tempi,t) is 0.333 which is greater than its standard deviation (0.268), this indicates a risk of climate warming. The standard deviation of agricultural fertilizer use (LnFui,t) is about 1.010 with a maximum value of 14.013 and a minimum value is 5.935. Therefore, there is a large difference in the quantity of fertilizer used per city. The average total power of agricultural machinery (LnAmpi,t) is 5.456, with a minimum value of 1.065 and a maximum value of 7.621, thus the mechanization level of agricultural production is relatively high in China. The average expenditure on agriculture, forestry, and water affairs (LnAfwei,t) is 12.711, with a minimum value of 7.213 and a maximum value of 15.890. This indicates that the government’s financial support for agriculture is relatively strong. The average value of industry structure upgrading (Isui,t) is 88.191, indicating that industries in China were upgraded from the primary industry to the secondary or tertiary industry. Finally, the standard deviation of the economic development level (Lnpgdpi,t) is about 1.022 with a maximum value of 12.584 and a minimum of 1.020. There is a large economic gap between cities.
Benchmark Model Regression Results
Table 3 – Columns (1) and (2) show that climate risk has a negative and significant (at 1% level) effect on the income of farmers. Our results are consistent with the results from previous literature. Climate risk reduces crop yield and increases production cost which reduces the income of farmers [25]. Specifically, one unit increase in climate risk would decrease the income of farmers by 2.1% (in Table 3 – Column (2)). Thus, the higher the climate risk (Tempi,t), the more the income of farmers (Lninci,t) will decrease. Regarding control variables, the total power of agricultural machinery (LnAmpi,t), expenditure on agricultural, forestry, and water affairs (LnAfwei,t), industrial structure upgrading (Isui,t), economic development level (Lnpgdpi,t) and trade openness (Toi,t) have a positive and significant effect on the income of farmers. Therefore, raising the level of agricultural mechanization, increasing investment in the primary sector, promoting industrial structure upgrading, improving economic development level, and enhancing trade openness can increase the income of farmers. However, the human capital level (Hci,t) does not have a significant effect on the income of farmers. The role of human capital in promoting the growth of income of farmers has not been fully played. Therefore, the adoption of adaptation strategies to control climate risk may be inhibited by the human capital level [16] in China.
Robustness Tests
The robustness test consists of two approaches which are: using an alternative sample and using an alternative explanatory variable. First, we reduced the sample by taking out cities with low climate risk values (HTempi,t). More specifically, cities with climate risk lower than 80% of the sample quantiles were excluded (Table 4 – Column (1)). Second, we substituted the original temperature-related variable with the absolute value of the difference between the current year and the average temperature of the past 4, 5, and 6 years (Temp4i,t, Temp5i,t, and Temp6i,t) (Table 4 – Columns (2)- (4)). We used an alternative explanatory variable and added the normalized temperature (Clm50i,t) of 50 years as the explanatory variable [55] (Table 4 – Column (5)). Table 4 – Columns (1) to (5) show that climate risk has a negative and significant effect on farmers’ income. Thus, the results from Table 3 are robust.
Table 2.
Descriptive statistics.
Table 3.
Impact of climate risk on the income of farmers.
Quantile Regression
A quantile regression was done to investigate the effect of climate risk on the income of farmers following the income group level. Quantiles 10, 25, 50, 75, and 90 represent the low-income group, lower-middle-income group, middle-income group, upper-middle-income group, and high-income group respectively. Table 5 shows that the climate risk has a negative and significant effect on the income of farmers regardless of their income level (with a significance level of 1% for all quantiles except for the low-income group which is significant at a 5% level). Furthermore, the negative impact is characterized by a “U-shape” form with a left-shift feature. This indicates that farmers with a higher level of income (75%-90%) are less affected by climate risk than farmers with a middle and low level of income (10%-50%). Our results are consistent with Hallegatte et al.’s results which found that low-income farmers are not efficient in lowering risks and are more vulnerable to losses [13]. Thus, climate risk contributes to increasing the gap between the income of farmers in rural areas.
Mechanism Analysis
Table 6 reports the mechanism analysis, specifically Table 6 – Columns (1) to (4) return the interactive effects of digital inclusive finance and climate risk respectively. We found that climate risk has a negative and significant effect (at a 1% level) on the income of farmers. The coefficient of the interaction term between digital inclusive finance and climate risk (Table 6 –Column (1)) is positive and significant at the 1% level. The same is observed regarding the coefficients of the interaction term between the three dimensions of digital inclusive finance and climate risk (Table 6 – Columns (2) to (4)). This indicates that digital inclusive finance has a regulatory effect and contributes to alleviating the negative impact of climate risks on the income of farmers. Specifically, digital inclusive finance provides services to the most vulnerable population at a low cost and in an efficient way [56]. For instance, digital inclusive finance has a wide coverage that facilitates the inclusion of the most vulnerable groups (farmers in rural areas) into the financial system. Thus, digital inclusive finance contributes to reducing financial exclusion and formalizing financial services in rural areas. Moreover, usage depth has become an important driving factor for the development of digital inclusive finance. Thanks to online services, digital inclusive finance has strengthened the supply capacity of payment, credit, insurance, and other financial services. Therefore, farmers can provide guarantees for loans that can be used for climate risk adaptation measures. Moreover, digitalization has reduced the cost of financial services which makes digital inclusive finance convenient and accessible for low-income farmers. However, the coefficient of digitization level is negative and significant (Table 6 – Column (4)). Since the usage rate of digital technology in rural areas is still relatively low and farmers are characterized by relatively low digital literacy, the potential supporting role of digital technology to increase income is inhibited [57]. However, according to the results of the moderating effect diagram of the digitalization level (see Fig. 4), it can be seen that when the digitalization level is high, the variable regulates the adverse effect of climate risk on income. To sum up, digital inclusive finance can mitigate the negative effect of climate risk on the income of farmers.
Table 4.
Robustness check.
Table 5.
Unconditional quantile regression results.
Heterogeneity Analysis
Heterogeneity of Agricultural Insurance
Agricultural production is based on crop growth and development, the greater the climate risk, the greater the uncertainty of agricultural output. Thus, climate risk is more detrimental to the growth of farmers’ income. At the same time, agricultural insurance is an important tool for managing climate risk, as it has the double attributes of sharing risks and compensating for risk losses [58]. Through its loss compensation function, agricultural insurance ensures the smooth progress of agricultural production, thereby reducing the negative impact of climate risk on farmers’ income. According to risk management theory, the differences in climate risk management levels in different regions will result in different impacts of climate risk on the income of farmers in the region. This section aims to analyze the effectiveness of the insurance system in managing climate risk. First, a dummy variable (Pinsinci,t) was used to capture the development level of agricultural insurance. If the per capita premium (Pinsinci,t) is higher than the median value of the sample, Pinsinc equal 1, otherwise 0. To capture the short-term effect of post-disaster loss compensation, we used per capita compensation (Pinsindi,t). This is a dummy variable equal to 1 if the per capita compensation is higher than the median value of the sample, otherwise 0. Finally, the long-term effect of post-disaster agricultural insurance compensation was proxied using the lagged per capita compensation (LPinsindi,t). The rationale behind this is that farmers use insurance compensation to restore agricultural production in the next production cycle. This is a dummy variable equal to 1 if the lag term of per capita compensation (LPinsindi,t) is higher than the median value of the sample, otherwise 0.
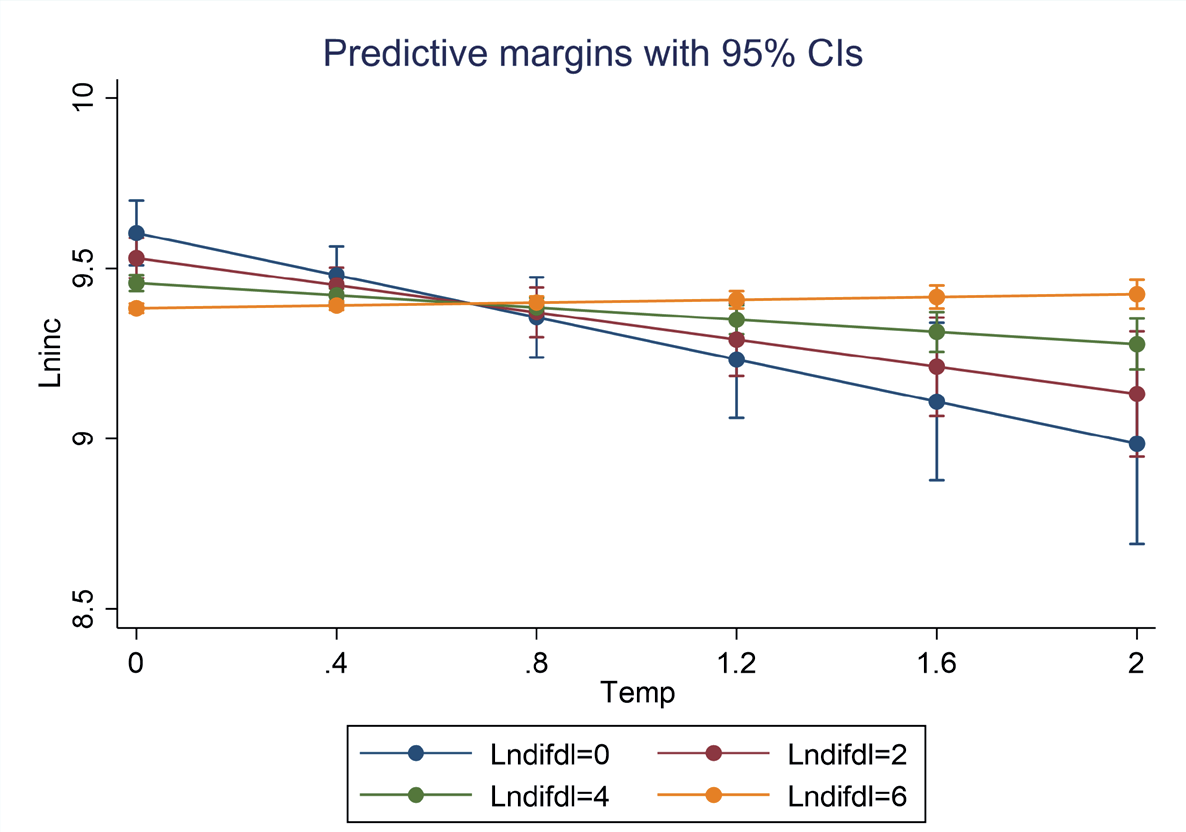
Table 6.
The regulatory role of digital inclusive finance.
Table 7.
Heterogeneity results of agricultural insurance.
Table 7 – Columns (1) and (2) show that in cities with a low development level of agricultural insurance, climate risk has a negative (–0.019) and significant (at a 5% level) effect on the income of farmers. However, climate risk does not have a significant effect on the income of farmers in cities with a high development level of agricultural insurance. Moreover, Table 7 shows that the effect of climate risk on the income of farmers is statistically different between cities with a low development level of agricultural insurance and cities with a high level of agricultural insurance. Table 7 – Columns (3) and (4) show that in cities with low per capita compensation, climate risk has a negative (–0.020) and significant (at a 5% level) effect on the income of farmers. As per previous results, this effect is not significant for cities with high per capita compensation. This indicates that per capita compensation can in the short term compensate for the loss from climate risk and increase the income of farmers. However, in the long run, if farmers fail to obtain full compensation, next year’s production will be affected, and the effect of climate risk on the income of farmers is stronger (the coefficient of climate risk is negative and significant at a 5% level Table 7 – Columns (5) and (6)). In general, the improvement of agricultural insurance can effectively reduce the adverse effect of climate risk on the income of farmers.
Regional Heterogeneity
Further analysis was done according to the geographical localization of each city. Due to the combined influence of large landscape and summer monsoon activities, the spatial distribution of China’s climate environment is extremely uneven with significant differences between the north and south regions. Previous research found that the impact of climate risk on grain production in northern and southern China has regional differences [59], thus the impact of climate risk on farmers’ income may vary between the southern and northern regions. We divided the sample into the Northern region (cities located in the north of the Qingling Huaihe (Table 8 – Column (1)) and the Sothern region (cities in the south (Table 8 – Column (2)) (Yan et al., 2019). We found that for cities in the northern region, climate risk has a negative (–0.029) and significant (at a 1% level) effect on the income of farmers when it was not significant for cities in the southern region. Generally, the average annual temperature in the south of China is significantly higher than that in the north. Thus, crops planted in the southern region are heat-resistant and have strong adaptability to climate risk [52]. Moreover, the extent and rate of temperature rise in the northern region are greater than that in the southern region [60]. Therefore, the crop calendar extended in the northern region which reduces the crop suitable for the northern region, reduces crop yield, and increases the price. These are expected to harm the income of farmers in the northern region.
Recommendation and Conclusions
Recommendation
We recommend to policymakers provide farmers with information and knowledge through sensitization campaigns on climate risk and disaster mitigation. Moreover, strengthing the transmission of information from meteorological monitoring technology is of utmost importance to get timely information. Policymakers can also provide supporting measures on adaptive strategies to climate risk. Furthermore, awareness raising on green governance and green development, and the establishment of systematic responses to climate risk and climate disaster prevention can develop the capacities of local authorities and improve the local economic system. Policymakers are also advised to support digital transformation by increasing investment in agricultural infrastructure and digital infrastructure. Efforts should focus on improving the financial system toward a more inclusive one through digital inclusive finance in rural areas. For that, it is recommended to expand the coverage breadth, usage depth, and digitization level of digital inclusive finance in rural financial markets. Such actions are expected to improve the financial services for farmers, especially for the most vulnerable population. On top of that, supporting measures such as investment in education and training on digital skills are required to improve farmers’ digital literacy and application ability. At the same time, it is of utmost importance to provide incentives to agricultural insurance companies to encourage them to work with local authorities such as meteorological departments and agricultural departments to provide a more adequate service to farmers. Examples include the consideration of climate risk, geographic localization, and crop growth in insurance policies. Sensitization campaigns and supporting services are also needed to increase the participation of farmers in the agricultural insurance system. Finally, it might be of great interest to combine agricultural insurance with credit and adapted financial services to support the increase of farmers’ income under climate risks.
Conclusion
Reducing risks is an important function of the financial system. Strengthening the resilience of farmers against the effects of risks is a key element of an inclusive financial system. Digital inclusive finance can solve the persisting financial exclusion in rural areas and increase the capital of farmers. Consequently, digital inclusive finance helps farmers to cope with the unexpected negative effect of climate risk on the production system, thus on the income of farmers. Moreover, digital inclusive finance gives more opportunities to farmers to upgrade their technology and engage in non-agricultural activities, thereby, increasing the income of farmers. This paper investigated the effect of climate risk on the income of farmers and the role of digital inclusive finance in mitigating the effect of climate risk on the income of farmers. We found that climate risk contributes to the reduction of the income of farmers. Furthermore, the effect of climate risk is expected to be stronger for low- and middle-income farmers, in the northern region of China, and cities with a low level of agricultural insurance. Therefore, climate risk is expected to increase the gap between the region and farmers in China. However, digital inclusive finance was found to mitigate the negative effect of climate risk on the income level of farmers.
The lack of data limited the study period of this study and since the focus of this study is global warming, other climate variables such as precipitation and solar radiation were not accounted for in this paper. Future research can focus on exploring the different aspects of climate change on the income of farmers.

