

Introduction
R&D investment is an important activity for firms to carry out knowledge creation and technical innovation [1]. The “new normal” of market environment volatile, uncertain, complex and ambiguous (VUCA) greatly increases the difficulty for firm decision makers to adjust the positioning of R&D investment in the right direction and the right time, exacerbates the adaptive challenge of R&D investment of existing firms.
R&D investment volatility is a controversial signal. It is generally believed that stable R&D investment is beneficial to firms due to the existence of Adjustment Cost and Sunk Cost, while the R&D investment volatility is a myopic behavior of “revenue manipulation” by senior executives. However, recent studies show that R&D investment volatility represents the process of firms actively adapting to the environment, pursuing innovation, and obtaining competitive advantages [2]. R&D opportunities are dynamic. Especially when the existing competitiveness of firms is eroded, firms tend to increase exploratory R&D to build new capabilities, which is reflected in the surge of R&D investment. When a new core capability is formed and it enters the stage of commercialized exploitative R&D, it is also reflected in the sharp decline of R&D investment. A short, significant change in R&D investment over a period of time that deviates from historical trends or deviates from expectations usually means a transition between exploratory R&D and exploitative R&D, which is essentially a Punctuated Equilibrium. R&D investment leap is an important way for firms to maintain competitive advantages in a dynamic environment [3]. Based on the logic that behavior affects performance, existing literature pays more attention to the impact of R&D investment leap on firm survival [4], growth and performance [5, 6], etc. The legitimacy and importance of R&D investment leap has been recognized.
Existing literature mainly focus on the impact effect of R&D investment leap, but R&D investment leap is technological track transitions and profound organizational changes, and it is not yet known under which scenarios and in which direction R&D investment leap will occur, and what factors will enhance the success rate of R&D investment leap. Exploring the antecedents of R&D investment leap can help enterprises build a reasonable technical knowledge system to adapt to the drastically adjusted R&D leap and ensure the smooth transition of the technological track adjustment, which is of great value to enterprises in grasping the current competitive advantages [7] and future technological opportunities. In this context, this paper moves forward to focus on the antecedents affecting R&D investment leap, and promotes the formation of a “structure-behavior-performance” framework, which contributes to the theoretical development of R&D investment volatility.
Existing studies generally believe that the essence of “exploration” is to enter new fields of knowledge and explore new knowledge trajectories, while the essence of “exploitation” is to rooted in the original knowledge domain and optimize the existing knowledge. That is to say, R&D investment leap is a natural consequence of the change in the trajectory of the enterprise’s technical knowledge, so a natural question is, what is the relationship between the enterprise’s technical knowledge and R&D investment leap? Based on the Punctuated Equilibrium perspective, this paper systematically analyzes and tests the influence of technical knowledge base (technical diversity and technical complexity) on R&D investment leap. This paper divides environment shock into advantages and disadvantages, and examines the moderating effect of environment shock, so as to deepen the research on the management of organizational R&D investment and the Punctuated Equilibrium ambidextrous transition.
Theory and Hypotheses
Punctuated Equilibrium Theory and Ambidextrous Transition
The core of Punctuated Equilibrium is sequential thawing, adjusting, and refreezing. It was first used to describe the law of organizational change and technical evolution in a specific period of time. Organizational change is a long-term, step-by-step process. Short-term discontiguous changes will break the status quo, bring new possibilities and uncertainties, and then enter a new gradual process [8]. Similarly, technical evolution presents an interweave of long-term incremental changes and short-term technical breakthroughs. Technical breakthroughs or discontinuities usher in an era of intense technical change and selection, culminating in a single dominant design that enters a new plateau [9]. Therefore, Punctuated Equilibrium refers to activities that balance and exclude each other across time. Organizational evolution and technical change follow the gradual development in a long period, at some stage, firms will trigger major changes and strategic adjustment.
Due to the inherent contradiction between exploratory and exploitative [10], Punctuated Equilibrium is also regarded as an important strategy of exploratory and exploitative in the organization of balance. That is, the organizational adaptation process is divided into a series of discrete periods, each focusing on a specific type of activity to maximize available opportunities, balancing exploitative and exploratory based on time partitions. A common view in technology and innovation management is that steady investment in technology innovation is beneficial to firm performance. However, later studies have pointed out that in some cases, companies are committed to shaping changes in the innovation trajectory and high-performing companies will show a R&D investment leap [3]. Under the Punctuated Equilibrium paradigm, the firm needs to switch between exploratory R&D and exploitative R&D. Compared with exploitative R&D, exploratory R&D often requires a large amount of capital investment at the early stage of product development, which is more expensive than exploitative R&D [11]. When R&D investment increases significantly in the short term, it means that firms shift from exploitative type to exploration type R&D, which is called upward R&D investment leap in this paper. Similarly, when R&D investment decreases significantly in the short term, it means that firms shift from exploratory R&D to exploitative R&D, which is called downward R&D investment leap in this paper. The empirical study of Mudambi and Swift [3] confirms that the significant increase or decrease in R&D investment, which deviates from the historical trend, represents the organization’s shift between different types of R&D and is the embodiment of active R&D management.
Technical Knowledge Base and Upward R&D Investment Leap
The strong technical knowledge offers the possibility to reduce the risk of uncertainty in jumping upwards in R&D investments. Firms from exploitative R&D to exploratory R&D often need to cross organizational and technological boundaries to focus on non-local knowledge search and integrate different types of knowledge. Often, exploration and innovation in a new technical field will be faced with a high degree of uncertainty [12], such as lack of ability and experience in knowledge search in the new technological field, too broad scope of knowledge search, increasing probability of making wrong decisions. However, if firms can combine the existing knowledge base to launch the search for the new technology field, it helps firm to simplify the scope of knowledge coupling and reduce the uncertainty of knowledge combination. The identification and mining of new technology knowledge depend on the existing technical knowledge base [13].
Technical diversity provides a broader knowledge portfolio and knowledge search for upward R&D investment leap. Diversified technical knowledge base is an vital condition for technical trajectory transformation [14, 15]. In terms of knowledge integration, diversified knowledge ensures novelty and heterogeneity of knowledge contact, expands firm knowledge base and increases the combination of knowledge elements [16, 17], provides new possibilities for R&D orientation transformation, and promotes the R&D investment leap. In terms of cross-border search, technical diversity helps break through the existing cognitive structure of firms, provide firms with long distance knowledge search to create new connections in different technical fields [18], which in turn leads to R&D investment leap. Katila and Ahuja [19] also show that exploratory R&D pursues relatively broad technical field, which is positively correlated with the breadth of knowledge creation.
Technical complexity provides higher-quality knowledge resources and knowledge barriers for upward R&D investment leap, fueling better accumulation of R&D leap capabilities and recognition of timing and scope. Technical complexity is an important representation of firm technology field status. Firms with cutting edge technological capabilities can make more efficient use of new knowledge and resources internally, and serve to solve existing problems and create new knowledge, boosting firms from exploitation to exploration. Externally, they are better at identifying and digesting external new technical knowledge, which can help firms enter the new technological track in advance and seize the emerging innovation opportunities. Thus, when firms identify novel and promising technical opportunities, they want to increase spending on exploratory innovation to spur an upward R&D investment leap. In terms of technical knowledge barriers, firms with high technical complexity tend to possess more patents or know-how, and are more likely to form entry barriers [20], thus achieving breakthroughs and protection from exploitative to exploratory innovations. So, the following hypothesis is proposed:
H1. Technical knowledge base has a significant positive effect on firms’ upward R&D investment leap, which is reflected in the fact that both technical diversity and technical complexity have a positive effect on firms’ upward R&D investment leap.
Technical Knowledge Base and Downward R&D Investment Leap
The shift from exploratory R&D to exploitation R&D is a shift from activities of a risk-taking, experimental nature to activities of a refinement, execution and efficiency nature [21]. This process typically shifts from a broad knowledge search to a focus on a specific, relatively narrow technical area, positively correlated with the depth of knowledge creation. This paper argues that firms with stronger technical knowledge base will hinder firms from downward R&D investment leap due to higher firm exploration ability and willingness, adjustment costs, and external signals of superiority.
First, firms with strong technical knowledge have a greater willingness and ability to shape their future competitive advantage, and are more likely to maintain exploratory R&D while delaying a shift to exploitation R&D. Stronger technical knowledge means that firms have better regulations, more advanced machinery and equipment, higher management and personnel quality, higher expected returns, and greater opportunity costs if they end an unfinished R&D project. Second, most researchers in firms with strong technical knowledge have highly specialized skills, and firing these researchers may result in the transfer of important tacit knowledge to competitors and higher adjustment costs. In addition, the endowment of technological capabilities reflected by the technical knowledge base is an important signal for investors to screen the quality and potential of firms, and technologically superior firms are more likely to build trust with financial institutions [22] and have higher feasibility of obtaining financing from external sources, which can provide financial support for firms to explore higher-order technologies and reinforce their willingness to delay the downward R&D investment leap.
It can be seen that if the exploration is abandoned early and shifted to exploitation, the firms with advantageous technical knowledge base face greater opportunity cost and realistic cost, and are less willing to shift from exploration to exploitation R&D; the availability of external financing provides a buffer for these firms’ downward R&D investment leap, making the magnitude of shifting from exploration to exploitation smaller for firms with higher diversity or complexity. In summary, this paper proposes the following hypothesis:
H2. The technical knowledge base has a significant negative impact on firms’ downward R&D investment leap, which reflects that both technical diversity and technical complexity have a negative impact on downward R&D investment leap.
Moderating Effects of Environment Shock
Environment shock emphasizes the uncertainty of whether a firm faces a positive or negative situation [23, 24], according to which, this paper divides environment shock into advantage and disadvantage, and explores the asymmetric effects of both.
First, external advantages can motivate firms with high technical diversity and complexity to make upward R&D investment leap. Firms with higher technical capabilities have a higher absorptive capacity and a higher likelihood of innovation success. Therefore, firms with higher technical capabilities have greater motivation to increase R&D investment under advantage conditions [25]. Advantage implies additional cash flow to the firm and provides financial support for innovation projects [26]. With this incentive, firms with a strong technical knowledge base have a strong incentive to significantly increase R&D investment due to high expected benefits of switching from exploitation to exploration. Even though an excessive knowledge portfolio increases the cost of managing and maintaining a firm’s knowledge, the sales growth that accompanies the opportunity and the potentially high benefits of moving to exploratory R&D can cover these costs. If a firm’s technical knowledge base is in a dominant position, it can help improve its sensitivity and responsiveness to opportunities [27], better judge the timing of the switch, and reduce risk. With its previous R&D experience, the likelihood of innovation success increases, facilitating firms to carry out upward R&D investment leap.
Second, unlike external advantages, disadvantage reinforce the negative relationship between technical knowledge base and downward R&D investment leap. Substantial adjustments in R&D investment are accompanied by high costs, disadvantage increases the probability of organizations making serious mistakes, when greater value can be gained by maintaining and waiting [28]. For firms with a strong technical knowledge base, if firms shift to exploitative R&D early due to disadvantage, they may miss out on promising technical results brought by exploration, affecting their survival and long-term performance [29]. There will be no return if R&D projects are stopped without completion, although firms with high technology expect higher returns on R&D investments. Firms with high knowledge base will slow down downward R&D investment leap under disadvantage relative to organizations with low knowledge base. Thus, the following hypotheses are formed.
H3. When environment shock is an advantage, it will strengthen the positive relationship between technical knowledge base and upward R&D investment leap.
H4. When environmental shock is a disadvantage, it will reinforce the negative relationship between technical knowledge base and downward R&D investment leap.
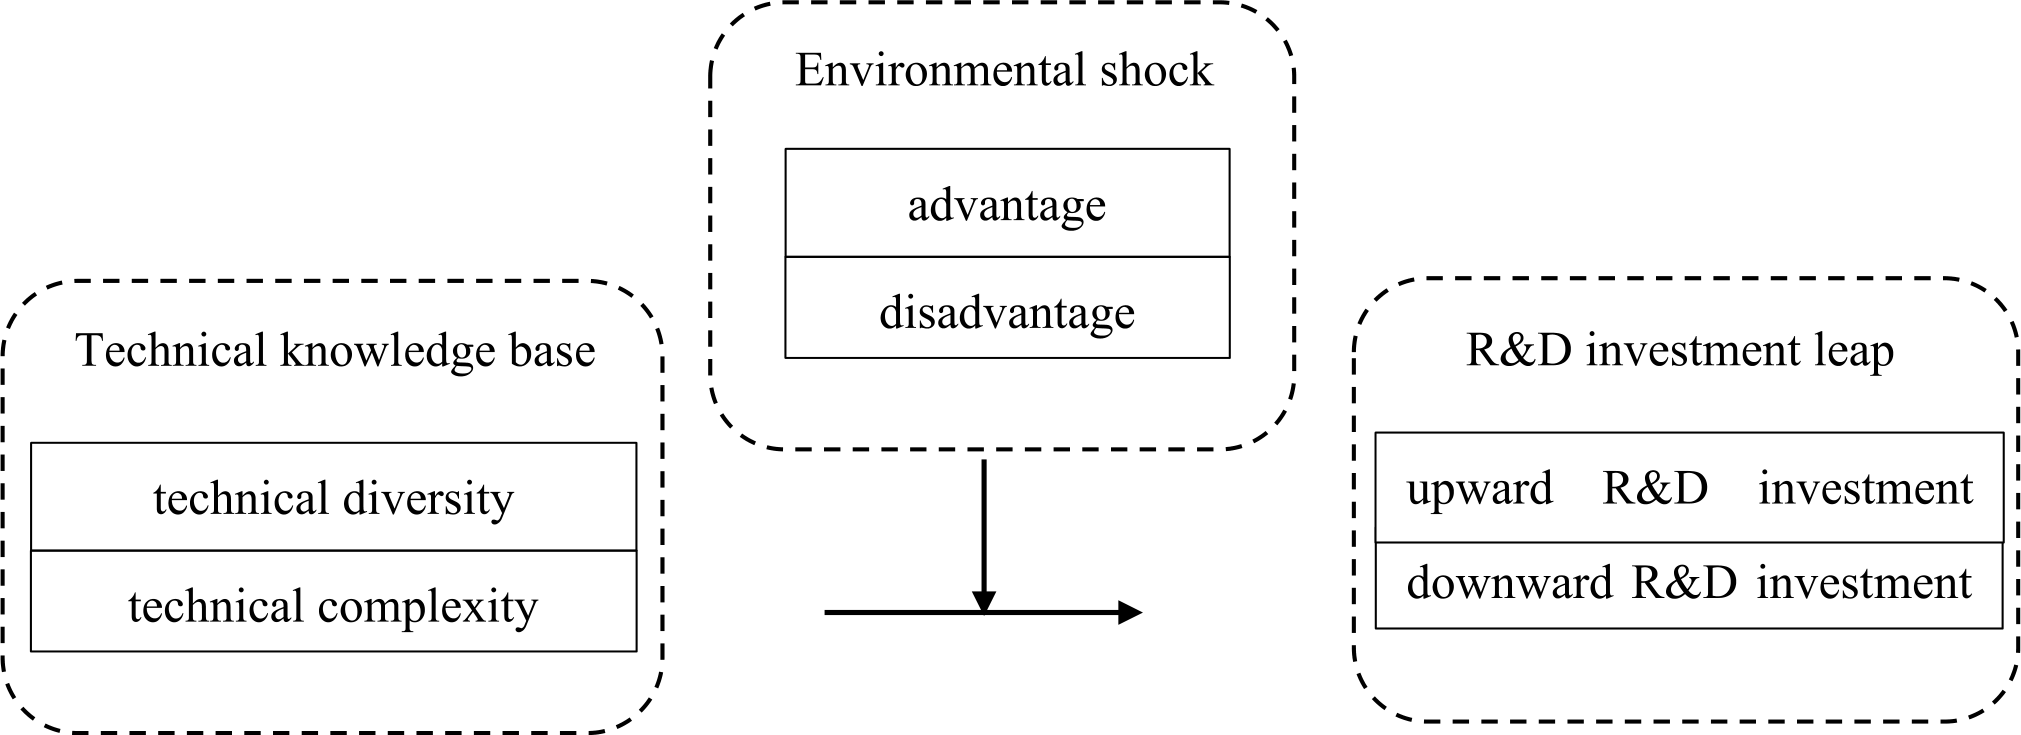
The theoretical framework of this paper is shown in Fig. 1.
Material and Methods
Variables and Measures
Independent Variables: Leap (Leapup, Leapdn)
Drawing on the measurement of Mudambi and Swift [3], GARCH model is used to measure R&D investment in a long period of time. The calculation steps are as follows: 1) based on the residuals of R&D investment, uit, construct a GARCH model; 2) generate eit by calculating the residuals uit deviating from the historical trend, accordingly, the frequency and extent of deviation from the expected R&D investment of the firm is estimated; 3) studentized residual, eit (stud), is calculated by dividing a forecast residual by the standard deviation to standardize the amplitude of R&D volatility; 4) take the maximum value of the absolute value of studentized residuals is R&D investment leap (Leap). That is:
Where si =
Dependent Variables: Technical Diversity (TechD), Technical Complexity (TechC)
The technical diversity is calculated using an entropy index based on patent filings:
Where N is the number of IPC subcategories owned by firm i, and Pj indicates the share of technology j in the total number of subcategories.
The higher the technical complexity, the fewer firms with similar technologies. According to this basic idea, this paper constructs two dimensions of uniqueness (TSH) and diversity (TechD) to measure the technical complexity (TechC).
The technical complexity is calculated as follows: First, the technical uniqueness (TSH) is calculated by measuring the degree of difference between the target firm and the average level of technical knowledge system of the industry in which it is located, with the following formula:
Where 129 is the large number of IPC, ƒik refers to the number of patent applications of firm i in the kth classification, and ƒnk refers to the average number of patent applications in the kth classification for industry n in which firm i is located. Multiply technical uniqueness with the technical diversity to obtain the technical complexity:
Moderating Variable: Environment Shock (PShock, NShock)
Environment Shock (Shock) is measured by using the ratio of the difference in sales change (Sales) in year t and year t-1 to total equity (CS), drawing on the approach of Kang et al [26]. Environment Shock are divided into advantage (PShock) and disadvantage (NShock). According to the size of Sales, if value is greater than 0, it represents advantage; otherwise, it represents disadvantage, with the following formula:
Control Variables
The control variables in this paper include: Size, which is the natural logarithm of sales revenue; Perfor, which is the net profit margin of total assets in the previous period; Growth, which is measured by the growth rate of operating revenue; Intens, which is measured by the ratio of R&D investment expenditure to operating revenue; Debt is measured as a proportion of total liabilities to total assets; Subsidy is measured by the ratio of government subsidies to R&D expenditures; Capital Intensity (CI) is the ratio of fixed assets to total assets. In addition, this paper introduces Altman' Z value (Z).
The Data
Chinese firms have belonged to the period of innovation climax in recent years, with more frequent organizational changes, which can provide a better sample for the study of R&D investment leap. This paper selects Shanghai and Shenzhen A-share listed companies from 2009-2018 as the sample. Patent data are obtained from incoPat database, the rest are from CSMAR. The original data are processed as follows:(1) exclude financial and insurance industries; (2) exclude listed companies with *ST, ST and PT; (3) exclude obviously strange samples; (4) exclude companies with missing data of key variables. Finally, 6450 observations were obtained for 701 companies. The data of the main variables are lagged by one period to enhance the rigor and rationality. Meanwhile, the interaction terms are decentralized.
Table 1.
Descriptive statistics and correlation coefficient of the variables.
Table 2.
Regression test results of Technical Knowledge Base, R&D Investment Leap and Environment Shock.
Results
Descriptive Statistics
Table 1 shows the descriptive statistics and correlation matrix of the main variables. The results indicate that the sample firms differ significantly in their performance on R&D investment leap and explains the rationality of variable selection.
Panel Data Regression
Estimation Method Selection and Endogenous Test
The data in this paper is unbalanced panel data and the fixed effects model was selected based on the Hausman test (χ2 = 74.19, p = 0.000). The modified Wald test significantly rejected the null hypotheses implying that heteroscedasticity exist. Using the lagged values of the endogenous variables (TechC and TechD) as instrumental variables, this paper uses 2SLS and DWH test to test for endogeneity. The results confirm that there is no endogeneity in the model. Therefore, FGLS method is selected.
Regression Models
Table 2 presents the regression results of technical knowledge base and R&D investment leap, and the moderating effect of environment shock (advantage and disadvantage). In this paper, we distinguish the direction of R&D investment leap. In Table 2, models 1-4 take Leapup as the dependent variable, models 5-8 take Leapdn as the dependent variable. On the basis of the regression with only control variables, model 1,5 add technical diversity (TechD); model 2,6 add technical complexity (TechC); model 3 introduces technical diversity (TechD), advantage (PShock) and their interaction term; model 4 introduces technical complexity (TechC), advantage (PShock) and their interaction term; model 7 introduces technical diversity (TechD), disadvantage (NShock) and their interaction term; model 8 introduces technical complexity (TechC), disadvantage (NShock) and their interaction term.
Results of the Regression Analyses
In models 1-2, the coefficients of technical diversity and technical complexity are significantly positive (β = 0.281, p<0.01, β = 1.401, p<0.01), which indicate that diversity and complexity of firms' technical knowledge involvement promote firms to make upward R&D investment leap, the technical knowledge base has a significant positive influence on firms' upward R&D investment leap, H1 is supported. In models 5-6, the coefficient of technical diversity is significantly negative (β = -0.094, p<0.100), the coefficient of technical complexity is negative but not significant (β = -0.147, p>0.100), H2 is partially supported.
In models 3-4, the coefficient of the interaction term between advantage and technical diversity is significantly positive (β = 0.038, p<0.100) and similarly, the interaction term between advantage and technical complexity is significantly positive (β = 0.319, p<0.010). It can be seen that H3 is supported by the fact that when an advantage arises, it induces firms with an advantageous technical knowledge base to substantially increase their R&D investment and leap from exploitation to exploration in a timely manner. To some extent, this explains why "the stronger technical ability, the greater the incentive for firms to invest in R&D" [30]. It also implies that the interaction of good external advantages and internal technical knowledge base endowment stimulates firms to commit to R&D activities in pursuit of new competitive advantages.
In models 7-8, the coefficients of the interaction terms between disadvantage and technical diversity and with technical complexity are significantly negative (β = -0.066, p<0.100, β = -0.447, p<0.100). These indicate when encountering disadvantages, firms with superior technical knowledge base will maintain their previous level of R&D investment due to the expectation that there will be higher returns on R&D investment, inhibiting significant cuts in firms' R&D investment and having a negative effect on downward R&D investment leap, which is supported by H4. In summary, the interaction between different types of environment shock and technical knowledge base has an asymmetric impact; under advantages, technical knowledge base can bring sharp increase in R&D investment, under disadvantages, technical knowledge base can restrain the sharp decrease in R&D investment.
Endogenous Treatment
The technical knowledge base may influence the R&D investment leap of a firm, and the R&D investment leap may in turn influence the technical knowledge base. In addition, the enhancement of firms' technical complexity and diversity may be endogenous. In order to alleviate the problem of reverse causality and sample selection bias, Heckman two-step method was adopted. The results are shown in Table 3, the regression findings remain consistent and IMR is not significant, indicating that there is no significant interaction relationship or self-selection bias.
Tests of Robustness
This section takes two approaches to test the robustness: replacing the variable measure and the regression method. Firstly, the measurement of environment shock is replaced. Drawing on approach of Aghion, which decomposes sales level into above-average sales level and below-average sales level. Advantage is when a firm’s sales are above the industry average; disadvantage is when a firm’s sales are below the industry average. The dummy variables, advantage = 1 and disadvantage = 0, were set, and the regression results are shown in models 13-16 in Table 4. Secondly, OLS was used to regress the data, see models17-20 in Table 4, the both regression results are consistent with the previous findings.
Table 3.
Results of endogenous tests.
Discussion and Conclusions
This paper analyzes the knowledge base antecedents of R&D investment leap along the branch of R&D investment dynamics from the Punctuated Equilibrium and Organizational ambidexterity theory perspectives, and examines the moderating effect of environment shock on the technical knowledge base and R&D investment leap. The results show that (1) technical diversity and technical complexity have a significant positive effect on upward R&D investment leap, but the negative effect on downward R&D investment leap is partially valid. (2) When environment shock are advantages, firms with stronger technical knowledge base are more capable of upward R&D investment leap; when environment shock are disadvantages, firms with stronger technical knowledge base are more capable of downward R&D investment leap.
Further, analyze why H2: “technical complexity have a negative impact on downward R&D investment leap” did not pass the test. The non-significant regression coefficients indicate that firms with high technical complexity are not obsessed with maintaining exploratory R&D all the time, which may be due to the existence of factors that prevent firms from falling into the “failure trap” by remaining in the exploratory R&D stage [31]. In particular, the exploratory R&D behaviors of high technical complexity enterprises tend to aim at cutting-edge and advanced, the initial investment is huge, and when the prospect of exploration is not yet clear, there is the hidden danger of dragging down the enterprise, and the willingness to stop loss rises.
The theoretical contributions are as follows:
This paper extends the topic of R&D investment leap from the current focus on its impact effects to explore the antecedents, thus bridging the gap in the existing research on the formation and impact factors of R&D investment leap. Since Mudambi, Swift [2, 3] analyzed R&D investment volatilitys and their effects from a R&D ambidextrous transition perspective, the existing literature has mainly analyzed the performance of R&D investment leap, but has not yet answered the question of “how R&D investment leap emerges”. In this paper, we take the perspective of Punctuated Equilibrium and knowledge base to describe the essence of R&D investment leap as a transformation of innovation orientation in the field of technical knowledge, and distinguish between two directions of transformation, which not only responds to Mudambi and Swift’s [3] call for “incorporating a knowledge perspective into innovation leap studies”, but also provides insight into the direction of R&D transition to analyze antecedents.
Table 4.
Results of robustness tests.
In this paper, technical knowledge base is divided into diversity and complexity, and the technical complexity index is rigorously constructed. This measurement method conforms to the theoretical view of the technical knowledge base, but also have good robustness in the empirical study. This paper not only explains “why firms with stronger technological strength have more motivated to invest in R&D” [30], but also advances the explanation that firms with stronger technological strength are more adept at switching between exploitation and exploration and adjusting their technological trajectory in time, which complements and enriches the knowledge base perspective of R&D decision behavior analysis. In addition, by introducing the environment shock of advantage and disadvantage, it clarifies its heterogeneous moderating role in the relationship between technical knowledge base and R&D investment leap, and enriches the study of environmental dynamics.
This paper explores the factors influencing the volatility of R&D investment based on technical knowledge perspective [32, 33]. The literature has shown that the volatility of R&D investment is divided into two camps: the “smooth theory” and the “volatility theory”. The “smooth theory” argues that stable R&D investment is a guarantee for organizations to gain and maintain competitive advantage. The “volatility theory” advocates that due to technological discontinuity, organizations should adopt an intermittent R&D investment model, emphasizing the transformation of R&D management. Studies have mainly explored the influencing factors of stable R&D investment based on the technical knowledge perspective [34], but less attention has been paid to the volatility R&D investment. So, this paper has enriched the studies of different camps of R&D investment volatility.
This paper has implications for firm R&D management. First, R&D investment leap is the act of switching between exploitative and exploratory, and firms need to seize the opportunity to carry out the R&D ambidextrous transition at the right time. Secondly, firms need to construct and make full use of their own technical knowledge base to better facilitate the R&D ambidextrous transition. Thirdly, firms need to target their R&D management plans under different types of environment shock according to their own technical knowledge base.

