

Introduction
ESG, which stands for environmental, social, and governance, encompasses an evaluation system that assesses a company’s sustainable operational capabilities across these three dimensions [1]. The concept of ESG was initially introduced by the United Nations Environment Programme Finance Initiative (UNEP FI) in 2004, and in 2006, the organization issued the Principles for Responsible Investment (PRI), advocating for the integration of ESG metrics into investment decisions made by investment institutions [2]. At the international level, many organizations have developed various frameworks and procedures to help companies meet their disclosure obligations related to ESG issues. These organizations include the Global Reporting Initiative (GRI), Sustainability Accounting Standards Board (SASB), International Integrated Reporting Council (IIRC), Carbon Disclosure Project (CDP), and the United Nations Global Compact (UNGC) [3]. These frameworks, guided by disclosure principles, provide clear guidance on how to report their non-financial issues and help them identify and address their corporate social and environmental responsibilities. ESG investment guidelines are also issued to guide investors in their investment practices based on corporate performance across the environmental, social, and governance dimensions [4].
A review of existing ESG research literature reveals a steady increase in the number of publications. Research outcomes in areas such as disclosure systems [5], responsible investment [6], and corporate ESG performance [7-10] are abundant. In recent years, bibliometric analysis has seen a significant growth in interest due to the increase of the number of software programs and multidisciplinary methods. Zhang and Huang [6] employ CiteSpace visualization technology to conduct a bibliometric analysis of hotspots in ESG responsible investment research, providing an overview of the field. Several researchers have explored the dynamic relationship between corporate financial performance and ESG performance. Bai et al. [7] investigate the connection between corporate ESG performance and investors’ preferences, while Qiu and Yin [8] examine the relationship between corporate ESG performance and financing costs. Wang [9] reviews ESG ratings and corporate performance in the relevant literature, and Drempetic et al. [10] analyze the impact of firm size, availability of resources for ESG data provision, and availability of firms’ ESG data on sustainability performance.
While the current ESG research literature is extensive, to the best of our knowledge, there is no single study on the bibliometric and content analysis of holistic ESG publications from dual perspectives. Therefore, this study sheds light on this topic. This study contributes to the literature by evaluating the most relevant topics in ESG research. We employ scientific knowledge mapping analysis to extract knowledge units from the literature, enabling the exploration of research hotspots in the field [11]. In addition, this study identifies current research limitations and addresses them in line with evolving trends. The results identified four major clusters: ESG disclosure, corporate financial performance, ESG investment, and corporate sustainable development strategy.
The remainder of this paper is organized as follows: Section 2 presents the data and methodology. Sections 3-6 present the bibliometric results and content analysis via the mapping of keyword frequency, clusters, and timelines. Section 7 presents the conclusions.
Data and Methodology
Data Sources
Sources from “Peking University Core”, “CSSCI”, and “CSCD” were selected in the CNKI database; literature types from “Academic journals”, “Dissertations”, and “Conference papers” were chosen; and the topic of “ESG” was focused on. A total of 837 pieces of literature were obtained, and after screening out commercial journals, irrelevant literature, and setting a limitation for the Chinese language, 295 pieces were excluded, resulting in a final selection of 542 pieces of local literature for the measurable analysis of ESG research. These articles were distributed between the years 2012 and 2023.
“ESG” was selected as the theme in the Web of Science Core Collection database, and the literature was refined based on criteria such as “Literature type: dissertation, proceedings, online publication, review paper” and “Language: English”. This yielded a total of 2,736 articles in English. After excluding 1,201 irrelevant articles, 1,535 articles on the measurable analysis of ESG research in English were obtained. These articles covered the period from 2007 to 2023.
Methodology
Substantial types of qualitative and quantitative literature review methods existed in the database. To illustrate, systematic literature reviews, meta-analyses, bibliometric analyses, and content reviews [12-15]. Among them, bibliometric analysis is a popular and rigorous method based on a quantitative approach for exploring and analyzing large volumes of scientific data, which enables us to unpack the evolutionary nuances of a specific field while shedding light on the emerging areas in that field [14]. Content analysis is a method to analyze qualitative data [16]. Using content analysis could further dig into the details of specific fields and facilitate exploring the rooted causes, future research trends, and research difficulties of each certain topic to get a more comprehensive understanding of the articles reviewed. According to Gaur and Kumar [17], the potential of content analysis lies in its combination with other methods. Based on that, this study employs a combination of bibliometric analysis techniques and content analysis methods to conduct research.
To analyze the research hotspots, core contents, and cutting-edge directions of local and global literature on ESG research comparatively, we imported the literature data from “2.1 Data sources” in the previous section into CiteSpace software. Firstly, we analyzed the ESG research hotspots intuitively through the visualization of keyword frequency. Secondly, we learned about the core contents of the ESG research field from keyword clustering. Thirdly, we clarified the evolution of different research clusters in the ESG field through the timeline view of keyword clustering. Finally, we summarized the frontier direction and future trend of ESG research through previous results.
Analyses of Research Hotspots
By extracting keywords from literature obtained through research, the research direction of a field can be intuitively understood. Further extraction of high-frequency keywords can analyze the research hotspots in the field [18]. The local and global literature were imported into CiteSpace, respectively. The subject word source was ticked as title, abstract, author keywords, and keywords plus. The time slice was set to 1 year, the g-index was set to k = 25, and the node type was selected as keywords. The word frequency mappings of keywords in local and global literature are depicted in Fig. 1a) and b).
The size of a node can intuitively reflect the attention given to a keyword. The larger the node is, the higher the frequency of keyword occurrence and the higher the attention should be given to ESG research on this keyword. The line between nodes indicates the co-occurrence relationship. The thicker the line, the stronger the co-occurrence relationship between keywords [19-21]. Fig. 1a) shows that the keyword frequency map of ESG literature in Chinese has 225 nodes and 280 connections, with a network density of 0.0111. The frequency of the keyword “disclosure” is much higher than that of other keywords, as high as 46 times. This indicates that local literature pays more attention to the research on ESG disclosure of enterprises. Fig. 1b) shows that the word frequency map of ESG keywords in English literature has a total of 545 nodes and 1206 connections, with a network density of 0.0081. The total number of keywords is large, and the keywords are closely linked. The frequency of the keyword “corporate social responsibility” is as high as 489 times, indicating that English literature has paid more attention to the research related to whether the enterprise implements social responsibility governance and the impacts on the results of corporate social responsibility governance on financial performance.
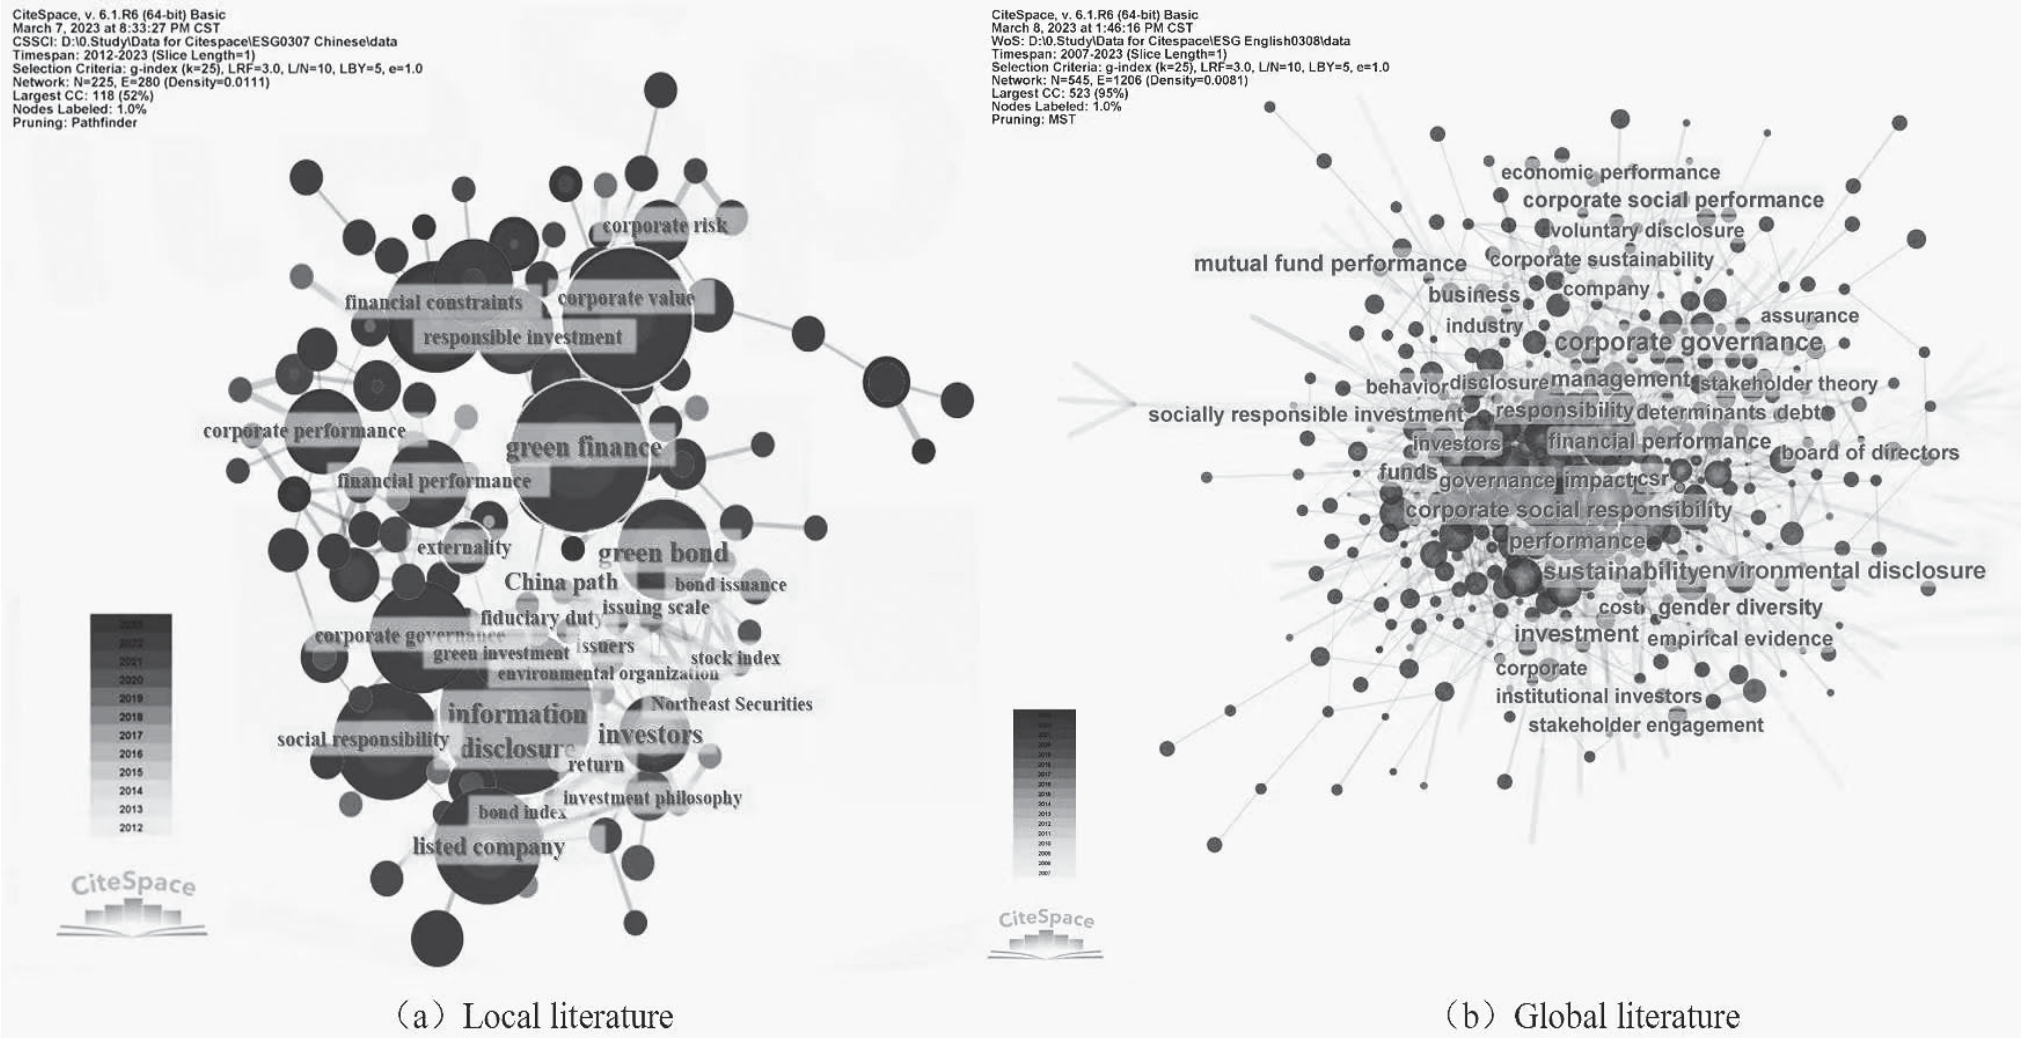
Comparing the results of keyword frequency analysis in local and global literature on ESG research, it is evident that local literature has predominantly focused on ESG disclosure. While an increasing number of companies are showcasing their environmental, social, and corporate governance performance through disclosure mechanisms such as ESG reports, corporate social responsibility reports, and sustainability reports, existing research indicates that ESG disclosure in China is selective, lacks credibility, and is hindered by inadequate policies, weak regulations, and limited voluntary participation [22]. Addressing these challenges and improving the current state of information disclosure in China is crucial for the proper promotion and implementation of ESG practices in the Chinese market. This explains why information disclosure has emerged as a prominent research area in the field of ESG in China.
On the other hand, English literature primarily focuses on corporate sustainability research from the perspectives of entrepreneurs and investors, delving into topics such as the impact of corporate social responsibility (CSR) strategies on stakeholders, the relationship between ESG activities and corporate financial performance, and the role of corporate disclosure in influencing investors’ investment decisions. The global disclosure systems and guidelines are continuously evolving, providing an opportunity for in-depth research on ESG based on high-quality disclosure data. Furthermore, there is a clear demand from investors and entrepreneurs for research on CSR, as both parties require research-based arguments to support their economic decision-making processes.
Analyses of Core Contents
Keywords Clustering Mapping Analysis
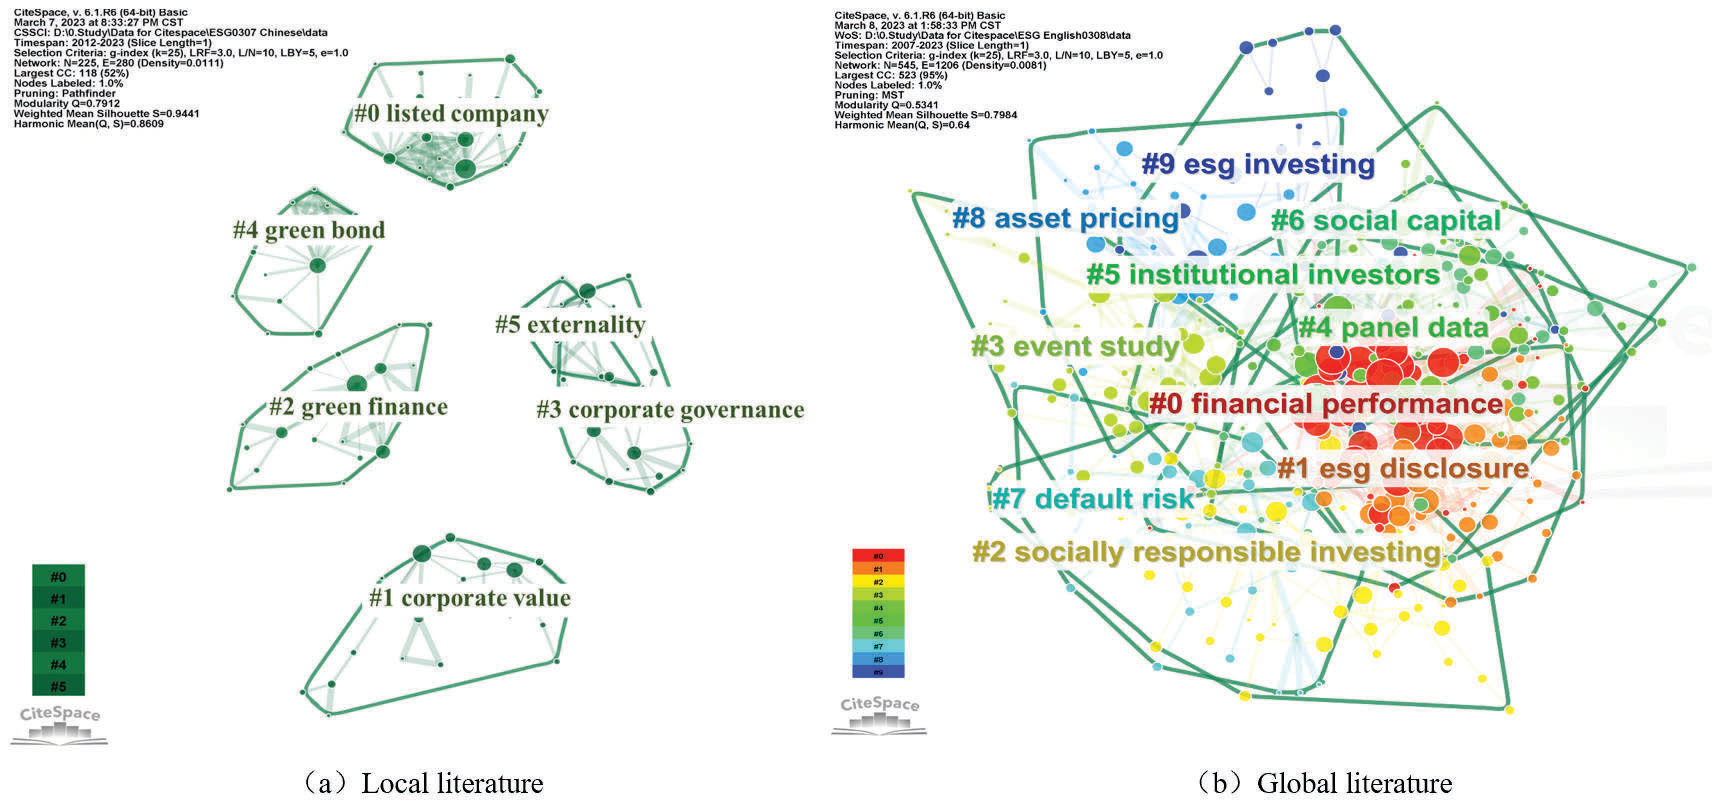
Based on the clarity of network structure and clustering, CiteSpace provides two metrics, the Modularity (Q-value) and the Silhouette (S-value), as the basis for us to judge the effectiveness of the mapping. In general, the Q-value is usually in the interval [0, 1), and a Q-value >0.3 implies that the clustering structure is significant, when the S-value is >0.7, the clustering is efficient and convincing, and when the S-value is >0.5, the clustering is reasonable [11]. Fig. 2a) and b) show the keyword clustering mapping of local and global literature in ESG research.
Fig. 2a) shows the local literature keywords clustering map with Q = 0.7912 and S = 0.9441, indicating that the clustering effect is significant and the clustering results are convincing. There are a total of six clusters of keywords in local literature on ESG research, namely: #0 “listed company”, #1 “corporate value “, #2 “green finance”, #3 “corporate governance”, #4 “green bond”, #5 “externality”.
Fig. 2b) shows the English literature keywords clustering map with Q = 0.5341 and S = 0.7984, indicating that the clustering effect of keywords in English literature is also significant and the clustering results are convincing. There are 10 clusters of keywords in English literature for ESG research, and compared with the clustering results of local literature, the keyword nodes of each cluster are more, and the relationship between the clusters is closer. The clusters are #0 “financial performance”, #1 “ESG disclosure”, #2 “socially responsible investing”, #3 “event study”, #4 “panel data”, #5 “institutional investors”, #6 “social capital”, #7 “default risk”, #8 “asset pricing”, #9 “ESG investing”.
Content Analyses of Keyword Clusters
After conducting an analysis, the ESG research literature in both English and Chinese can be categorized into four main areas. Firstly, ESG disclosure focuses on the current state of disclosure systems, standards, and regulations in the world. Many studies in this category utilize data from listed companies, such as conducting regression analyses to examine the impact of disclosure on various outcomes. Secondly, research on corporate financial performance explores the relationship among ESG dimensions (e.g., corporate social responsibility, corporate governance, organizational and management structure), corporate financial performance, and corporate value. This research draws upon theories such as stakeholder theory and sustainable investment theory, with enterprises as the primary subjects of analysis. The third category encompasses research on ESG investment, specifically sustainable and responsible investment. This area examines investment strategies that consider ESG factors and their impact on investment outcomes. Lastly, studies on corporate sustainable development strategy consider the influence of external issues on ESG development. This research examines the impact of environmental changes and environmental protection policies on industries and individual enterprises. A detailed inventory of the category division, cluster labels, and keywords can be found in Table 1 and Table 2.
Table 1.
Literature content inventory of local literature.
Table 2.
Literature content inventory of global literature.
ESG research in China has witnessed rapid development, aligning with the country’s dual-carbon goals [23]. While starting relatively late, the academic community has extensively explored various dimensions of ESG, including ESG investment, corporate financial performance, and corporate sustainable development strategy. The findings of these studies apply to the local context and stage of economic development. For instance: (1) Good ESG performance has been found to significantly enhance the enterprise value of listed companies. However, the impact of ESG performance on enterprise value exhibits heterogeneity, which is influenced by factors such as energy consumption status, nature of enterprises, and degree of marketization [7, 24]. (2) Institutional investors demonstrate preferences for ESG investments and are willing to tolerate, to some extent, the lower short-term operating performance of listed companies that exhibit strong ESG performance [7]. (3) Sustainability reporting complements financial reporting by incorporating externalities into the evaluation of corporate performance. It provides valuable insights into corporate sustainability prospects, offering a more comprehensive understanding of a company’s overall performance [25].
From the local perspective, it is evident that the relationship between corporate financial performance and ESG performance is complex. Currently, ESG disclosure by Chinese enterprises is predominantly voluntary, raising concerns about its completeness and effectiveness. Empirical research in this area still has space for further enrichment. To address these gaps, it is recommended to establish a robust and standardized ESG disclosure system. Moreover, future research can utilize cutting-edge technologies like big data and cloud computing to construct an enterprise ESG database. Additionally, it is crucial to establish a regulatory framework for ensuring data transparency. Initially, the focus can be on listed companies, gradually expanding to economic entities of varying scales as the quality and quantity of disclosure improve. This approach will enable the collection of transparent and effective ESG disclosure data, providing a solid foundation for future research on topics such as the ESG system, corporate financial performance, board organizational structure, and the intricate relationship between ESG performance and corporate financial performance. Moreover, this initiative will facilitate the iterative development of the disclosure mechanism and foster in-depth exploration of ESG concepts.
Corporate sustainability has emerged as a global trend, leading to a shift in corporate business models and management theories from a traditional shareholder-oriented approach to a stakeholder-oriented approach. This shift signifies that corporate operations now consider the interests of all stakeholders from multiple perspectives, aiming to maximize the social value associated with ESG issues. Notably, there is a significant alignment between stakeholder theories and ESG studies in the corporate dimension [26]. Several findings from ESG research in the English literature are worth highlighting. Firstly, it has been observed that the majority of ESG activities are not negatively correlated with firm efficiency, return on assets, and market value [26]. Secondly, corporate governance variables have been found to influence ESG disclosure. Specifically, a company’s CSR disclosure is associated with the presence of independent directors and a dedicated CSR committee. Moreover, it exhibits a negative correlation with the number of women on the board of directors and shows no significant correlation with the age of board members [27]. Thirdly, companies operating in the environmental sector are more likely to actively promote environmental sustainability [27]. Lastly, national institutions play a significant role in shaping companies’ ESG disclosure practices, including political, labor, and cultural institutions [28].
From a global perspective, the ESG disclosure system and rating system have undergone continuous change and growth, leading to improvements in the credibility and validity of related research data. Through keyword clustering analysis of the English literature, it is evident that the relationship between ESG development and corporate financial performance has received considerable attention from academics, with most studies concluding a non-negative correlation. Given the current significance and popularity of ESG, the research question no longer revolves around whether ESG can generate excess returns for companies. Instead, in the current era of shifting business and investment paradigms, factors such as climate change and public attitudes have become closely intertwined with the survival and success of enterprises and organizations. Consequently, institutional investors must incorporate ESG considerations into their decision-making processes. Future research should align with this evolving trend and focus on refining activity variables within the environmental, social, and corporate governance dimensions. It should investigate the complex relationship between these variables and ESG investment, disclosure, enterprise value, market efficiency, and other relevant segments in practical applications. Such research will provide valuable guidance for the development and implementation of ESG practices. Moreover, it has the potential to enhance the research and application value of ESG, aligning it with the evolving needs of companies and investors in the context of a changing business landscape.
Comparative Analysis of Core Content and Development Status
The keyword clustering mapping and content analysis of local and global literature reveal that ESG research can be categorized into four main areas, as presented in Table 1. However, there are differences in the level of refinement and focus between Chinese and English research due to different ESG development statuses, which can be observed in the following ways: (1) ESG information disclosure has emerged as a prominent research area in China, characterized by certain challenges that hinder its effectiveness. These challenges include issues of selectivity and credibility, inadequate policies, weak regulation, limited scope of disclosure entities, and relatively low levels of voluntariness. While, to some extent, some Western countries are witnessing rapid and continuous development in their disclosure systems. Notably, in the European Union, there is a gradual transition from voluntary to mandatory disclosure, indicating a significant shift in the nature of disclosure practices, which may be beneficial for further information disclosure and deeper empirical application [21].
(2) Presently, ESG research generally encompasses the three dimensions of environment, society, and corporate governance. However, the level of development differs between regions. The European Union, representing the global ESG market, may be shifting from high-speed to high-quality development. The development of ESG in China is still in its nascent stage, characterized by rapid growth but lacking full maturity. This can be attributed to several complex factors, including the imperfections within the disclosure system, which may give rise to concerns of greenwashing, as well as irregularities in ESG investment products. Nonetheless, it is worth noting that the availability of ESG information in China is experiencing significant expansion. (3) Differences in national economic conditions, including factors such as national industrial structure and industry diversity, as well as variations in social and cultural backgrounds, such as investment preferences, and the presence of specific ESG policies, contribute to the emergence of unique research focal points in different countries. In China, the interplay of factors such as the proposal of dual-carbon goals in 2020, the introduction of new ESG regulations in recent years, and the growing emphasis on green financial development have propelled the field of ESG research to the forefront. Consequently, there has been a notable surge in scholarly investigations exploring the intersection of ESG considerations with the dual-carbon policy and China’s green development trajectory. In the realm of global ESG policies, considerable emphasis has been placed on the integration of ESG principles within international organizations such as the United Nations Principles for Responsible Investment PRI (UNPRI), the International Organization for Standardization (ISO), the Global Reporting Initiative (GRI), and the Sustainability Accounting Standards Board (SASB). This tendency is often observed in existing literature, where the focus is primarily directed toward exploring the implementation and impact of ESG frameworks established by these international bodies.
(4) Local and global literature exhibit divergent research focuses when it comes to ESG investment. In Western countries, where there are relatively mature disclosure and rating systems, ESG investment research primarily revolves around exploring specific themes or sub-fields. These include ethical investment, which serves as the precursor to ESG responsible investment, corporate governance, market efficiency, and the implementation status of ESG investment. Conversely, local literature predominantly examines the “investment effects” resulting from enhancing ESG performance, particularly the influence on financing and attracting investment for economic entities. This aligns with the context of China’s opening policy [24].
Analyses of the Evolution
Analysis of Keyword Clustering Timeline View
The timeline view outlines the relationship between the clusters and the historical span of literature in a particular cluster. It allows us to observe the main keywords between the clusters as well as the distribution time of the keywords and their connection relationships [11]. Fig. 3a) and b) show the timeline view of keyword clustering in local and global literature for ESG research.
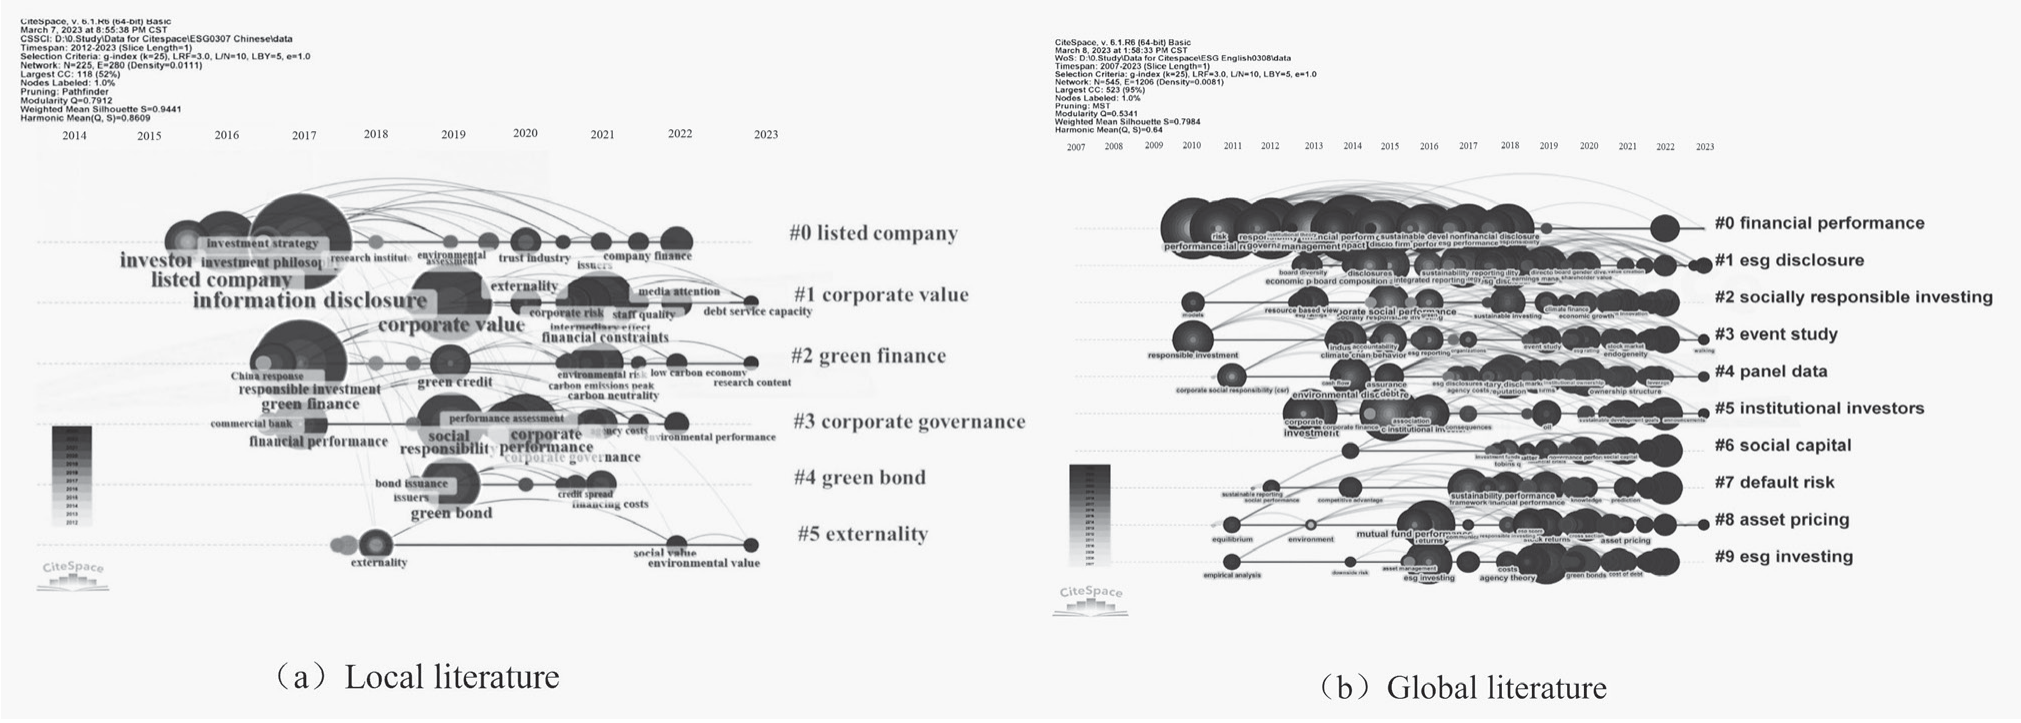
Fig. 3b) illustrates the relatively close relationship between the clusters of local literature on ESG. The four prominent clusters are labeled as #0 “listed company”, #1 “corporate value”, #2 “green finance”, and #3 “corporate governance”. The research interest in “corporate value” and “green finance” has remained consistent over time.
The high-frequency keyword nodes of the four hot clusters began to appear in 2015-2019 and had the first reference.
The research outcomes of the “listed companies”, “green finance”, and “corporate governance” clusters have increased since 2017. Moreover, the “listed companies” and “green finance” clusters initially focused on the investment field, but their core research areas differ. Representative literature from the “listed companies” cluster utilized disclosure data from A-share listed companies between 2012 and 2019 as the research sample. This literature empirically examined the impact of mandatory, imitative, and normative institutional pressures on the fulfillment of ESG responsibilities by listed companies, as well as the regulatory role played by dominant CEOs [29]. On the other hand, representative literature from the “green finance” cluster discussed the influence of corporate issuance of green bonds on debt contracts. The findings revealed that enterprises issuing green bonds experienced greater availability and lower borrowing costs for bank loans, leading to an increase in the long-term borrowing ratio [30]. In addition, the “corporate governance” cluster’s representative literature explored the relationship between the ESG performance of listed companies and their financial performance. The findings indicated a negative correlation between ESG performance and corporate financial performance [31]. Since 2019, the research results of the “corporate value” cluster have progressively increased. In representative literature, the impact of ESG rating performance on corporate value was analyzed from both book value and market value perspectives. The study examined the relationship between corporate value and ESG performance in terms of financing costs and market share [32].
From Fig. 3b), it can be observed that the connections between ESG literature clusters in English are closer compared to those in Chinese, and there are a greater number of keyword nodes. Most of the high-frequency keyword nodes appeared between 2010 and 2019. The research hotspots are mainly concentrated in #0 “financial performance”, #1 “ESG disclosure”, #2 “socially responsible investing”, #3 “event study”, #4 “panel data”, and #5 “institutional investors”. The time span of the ten clusters is extensive and continues to the present day, indicating that foreign ESG research is highly active and ongoing.
The high-frequency keyword nodes of the six hot clusters began to appear in 2010-2015 and had the first reference.
The “financial performance” cluster exhibits the highest number of high-frequency keyword nodes, indicating extensive research activities since 2010. Notably, a highly cited study within this cluster explores the relationship between CSR strategy and improved financing channels, investigating whether the exceptional performance of CSR initiatives leads to better access to funding [33]. Similarly, the “socially responsible investing” cluster and the “event study” cluster have witnessed an increase in research output since 2010. A notable study within the “socially responsible investing” cluster suggests that ESG ratings or scores can reflect both fundamental information about companies and investor preferences. The study utilizes large datasets to examine the costs and benefits associated with responsible investment [34]. On the other hand, a highly cited study within the “event study” cluster emphasizes that a company’s response to ESG ratings depends on the manager’s belief in the tangible benefits of favorable ratings and their alignment with corporate strategy [35]. The “panel data” cluster has seen an increase in research output since 2011. A prominent study within this cluster collects ESG disclosure scores and governance information from the Thomson Reuters database. It employs multiple panel data regression models and sensitivity tests to investigate the impact of board composition on ESG reporting in Gulf states [36]. Moreover, the “ESG disclosure” cluster and the “institutional investors” cluster have gradually witnessed an increase in research output since 2013. A highly cited study within the “ESG disclosure” cluster explores the influence of institutional theory and legitimacy theory on ESG disclosure practices, examining the extent of impact on environmental, social, and corporate governance dimensions [28]. In the “institutional investors” cluster, a notable study investigates institutional investors’ awareness of climate risks. The findings indicate that institutional investors tend to prioritize risk management over divestment strategies [37].
Table 3.
Evolution stages of local and global literature.
Comparative Analysis of Research Development Stages
The developmental trajectory of ESG research can be broadly categorized into three stages based on the current research timeline and progress. In the context of local literature, these stages are defined as follows: the early stage spans from 2012 to 2016, the middle stage encompasses the years 2017 to 2020, and the current stage covers the period from 2021 onwards. As for English literature, which stands on a global scale, the stages are delineated as follows: the early stage spans from 2007 to 2012, the middle stage covers the years 2013 to 2018, and the current stage extends from 2019 to the present. This classification is illustrated in Table 3.
During the early phase of ESG research conducted in China, considerable scholarly attention was devoted to the exploration of investment philosophies and investor preferences. This was followed by a progression towards utilizing disclosed information from publicly listed companies as the primary research samples. Concurrently, ESG investigations expanded to include information disclosed by other entities, with a specific emphasis on scrutinizing the relationship between ESG performance and corporate valuation. Subsequently, research in the middle stage prominently featured studies on green finance. Drawing upon the principles of green finance theory, significant advancements were achieved in elucidating the association between green credit and various dimensions such as sustainable development, risk management, and corporate performance. In the present stage of ESG research, the focus has broadened to build upon the insights garnered during the middle stage, particularly highlighting corporate risk management within the context of carbon neutrality as well as the social and environmental value of ESG considerations. Research has increasingly concentrated on the internalization process of externalities encountered by corporations. It has been acknowledged that a virtuous cycle can only be established through the internalization of ESG costs and the consequent induction of changes in corporate behavior.
In the early stages of ESG research conducted in the English language, the primary focus was on examining the correlation between CSR performance and financial outcomes, alongside the investigation of responsible investment practices. As research evolved into the middle and current stages, there was a heightened emphasis on the exploration of green finance, encompassing elements such as green bonds. These studies delved deeply into the intricate relationships between environmental disclosure, ESG investing, corporate social performance, ownership structure, financial performance, and corporate valuation. Additionally, the impact of various operational variables within the environmental, social, and governance dimensions on the sustainable development of enterprises has been rigorously examined.
The evolving trajectory of ESG research indicates a discernible pattern and predictability. The research focus has transitioned from theoretical exploration to investment practices, with a shift in research direction from the early stage emphasis on CSR to encompassing environmental disclosure and corporate financial performance. Presently, a comprehensive research framework has emerged, guided by the theory of social responsibility, supported by data-driven information disclosure, and centered around corporate financial performance. However, ESG research lacks a consolidated theoretical framework and clear research guidance, resulting in a relatively fragmented landscape. This fragmentation may be attributed to two main factors. Firstly, ESG research is significantly influenced by externalities related to the environment, society, and corporate governance. The wide range of research topics and large volumes of papers make it challenging to systematize the research efforts. Secondly, scholars hold different perspectives on the application value of ESG, leading to divergent research directions. Some scholars believe that the application value of ESG lies in guiding investors towards sustainable investments, which are expected to generate long-term high-value returns (e.g., Qiu and Yin [8]). On the other hand, some scholars view ESG as a sustainable concept that promotes comprehensive decision-making in enterprises, considering environmental, social, and corporate governance factors. This approach enhances corporate environmental awareness and fosters socially sustainable development (e.g., Huang [38]).
Analyses of Research Trends
The future research directions and trends in ESG can be outlined as follows: In China, it is imperative to prioritize the establishment of a robust information disclosure system and ESG evaluation system, primarily under the auspices of the government. These endeavors should draw upon established frameworks or guidelines such as the Principles for Responsible Investment (PRI), GRI Standards, ISO 26000, among others. In compliance with international ESG-related reports and guidelines, Chinese financial institutions can also consider local conditions and reference international institutions such as Morgan Stanley Capital International (MSCI), Thomson Reuters, FTSE Russell, Sustainalytics, etc., to establish a suitable ESG rating mechanism. This mechanism ought to be widely embraced and further refined to amplify its social impact while also yielding ample rating information for subsequent research endeavors. Additionally, there should be a concerted emphasis on empirical research pertaining to ESG investment. Moreover, in-depth research can be conducted on the mutual development of ESG investment and green finance. On a global scale, further refinement of the relationship between various stakeholders of enterprises and sustainable development, as well as the ESG performance of companies within the existing research framework, should be pursued. This includes exploring the causal relationship between shareholder value and ESG performance.
Building upon the previous content, this paper will specifically address the recommendation for future trends of ESG research in areas such as “ESG investment”, “ESG disclosure”, “corporate financial performance”, and “corporate sustainable development strategy”.
Firstly, it is crucial to enhance the theoretical research on ESG investment. This entails analyzing theories related to ESG investment across various disciplines, including economics, law, management, finance, ethics, and sociology. By doing so, a comprehensive theoretical system for ESG can be established, providing enterprises with diverse guidance to formulate sustainable investment strategies.
Secondly, it is essential to conduct research on the mechanisms through which different levels of voluntary and mandatory disclosure, as well as comprehensive and moderate disclosure, impact the development of ESG, taking into account national conditions and social backgrounds. This research should also consider the social consequences associated with the transition from voluntary to mandatory ESG information disclosure. By examining these mechanisms, we can gain a deeper understanding of how different disclosure practices shape the ESG landscape and contribute to sustainable development.
Thirdly, it is crucial to enhance ESG practices and expand empirical research. Empirical research plays a pivotal role in promoting ESG practices, as it helps identify the factors and influencers that contribute to the formation of information disclosure levels. Conversely, by improving the quality and extent of information disclosure, we can facilitate further empirical research. This reciprocal relationship between empirical research and information disclosure development is complementary and mutually reinforcing.
Fourthly, it is imperative to examine the information disclosure principles and guidelines issued by different countries to date. A comprehensive consideration should be given to how local ESG disclosure guidelines can be effectively integrated with national investment requirements, particularly in the context of the dual carbon goals. Currently, most Chinese ESG disclosures are voluntary, and there lacks a unified information disclosure regulation. Therefore, it is essential to enhance the enthusiasm of enterprises for disclosure, and efforts should be made to establish a standardized framework for ESG information disclosure.
Fifthly, the corporate value can serve as a direct manifestation of the ESG impacts on corporate financial performance in the eyes of investors. Therefore, it is imperative to delve into the intricate relationship between ESG performance and corporate value. With listed companies as the primary research subjects, clothing corporations can be suitable research subjects due to the high contamination characteristics of the textile industry [39]. This includes examining the connections between stakeholders and the ESG performance of enterprises, the impact of financial performance on ESG development deployment, the influence of organizational structure on promoting ESG development, and the relationship between enterprise scale and ESG development, among others.
Sixthly, there is a need to collect disclosure information from various industry sectors and examine the heterogeneous performance of ESG across different industries. In cases where industries have low levels of disclosure, researchers can employ reliable and authoritative ESG rating systems to quantify the non-financial information of enterprises. The resulting scores can provide a comprehensive understanding of the development of ESG throughout the enterprise business cycle.
Seventhly, while current ESG research is closely related to the investment field, it is crucial to expand future research to explore the empowerment of ESG for enterprises and industries. This entails integrating the community concept and the concept of harmonious development advocated by ESG into enterprises and industries, thereby transforming them into driving forces for both society and enterprises.
Conclusions
Based on the analysis conducted using the CiteSpace visualization literature tool, this study quantitatively analyzes 2,077 Chinese and English ESG research publications from the CNKI and Web of Science databases. It compares and analyzes the core contents and focuses of ESG research in Chinese and English, aiming to predict the frontier direction and future trends in ESG research. The key findings are as follows:
From the perspective of research hotspots, there are numerous areas of focus with a relatively close connection between these hotspots. In local literature, there is a higher emphasis on ESG information disclosure-related research, while on a global scale, more English literature concentrates on exploring the sustainable development capabilities of enterprises from the perspectives of entrepreneurs and investors. Research content related to enterprise organization management is more extensive and in-depth.
Local and global research primarily centers around “ESG information disclosure”, “corporate financial performance”, “ESG investment”, and “corporate sustainable development strategy”. Generally, ESG research is still in the exploration stage. However, there are some existing shortcomings in the current research landscape. In local literature, numerous studies have underscored the deficiencies in the current state of disclosure practices, highlighting the challenges arising from the rapid development of ESG while disclosure mechanisms struggle to keep pace with regard to information volume, transparency, and creditability. Additionally, empirical research on ESG is not yet extensive enough. As for English literature, research shows a trend of fragmentation due to the ESG development status transitioning from high-speed development to high-quality development overall.
Local literature is currently emphasizing the mutual development of ESG responsible investment and green finance, whereas English literature is placing greater attention on the relationship between stakeholders and ESG performance. Chinese enterprises and rating agencies should learn from global leading practices in ESG information disclosure and rating methods and initiate ESG initiatives based on their own investment decision-making requirements. The clothing industry exhibits a relatively high degree of globalization; future research could explore the dynamic relationship between ESG factors and environmental and social impacts within the clothing supply chain, using clothing companies as a case study. This would provide valuable insights into the interplay between ESG practices and the environmental and social dimensions of the clothing industry.
However, the study is not devoid of limitations. Despite conducting a bibliometric and content analysis of literature sourced from the CNKI and Web of Science Core Collection databases, the intricacies stemming from variances in ESG frameworks and methodologies crafted by diverse organizations or experts remain unexplored within this paper. Nevertheless, acknowledging these limitations illuminates pathways for future research endeavors to delve deeper into these nuances and to refine the analysis in subsequent studies.

