

Introduction
Background
Starting with the 18th National People’s Congress, China has balanced economic growth and environmental protection with its “ecological civilization” plan [1]. The nation has advanced global climate governance and green, low-carbon development [2-5]. Enterprises not only fuel economic growth but also degrade the environment, making them a key focus of national environmental protection [6]. The economic shift in China towards high-quality development aligns with increased environmental conservation efforts [7-10]. Environmental conditions have transformed, showing an overall improvement [11-13]. Since increasing emissions from agricultural, livestock, industrial, and other sectors [14, 15], the government has implemented environmental control laws and subsidy policies to encourage eco-friendly practices, aiming for carbon neutrality [16-18].
However, driven by profit motives, enterprises often lean toward allocating financial resources to economic projects to realize greater economic value and market advantages. Environmental protection investments, on the other hand, are primarily non-economic ventures characterized by high initial and ongoing costs [19]. These investments prioritize social and environmental benefits over economic gains, thereby potentially impeding the economic progress of enterprises [20]. The government, through its environmental control framework and policies, serves as the principal external factor influencing environmental protection investments by enterprises. There are four main contributions to the study.
Cross-Cultural Relevance: While grounded in the Chinese context, our study transcends national boundaries, offering cross-cultural relevance to the broader field of environmental science and resource policy. The implications of government actions on corporate environmental strategies explored in our study have broader applicability, fostering a nuanced understanding of how policies influence sustainability practices globally.
Informed Policy Formulation: The study examines the effectiveness of environmental protection penalties and provides practical contributions to policy formulation.
Promoting Sustainable Business Practices: The study’s research shows how government interventions promote environmentally responsible company activities. These insights are vital for corporations, politicians, and scholars advocating corporate sustainability.
Advancing Environmental Justice and Equity: The study examines the impact of government environmental actions on enterprises across diverse sectors and ownership types. By considering the deterrent effect on enterprises with a history of illegal pollutant discharge, the study contributes to discussions on environmental justice and equity within the broader framework of environmental science and resource policy.
However, the challenge lies in enterprises prioritizing economic gains over environmental protection due to high costs [19]. The study provides cross-cultural relevance and insights for policymakers on penalty and subsidy effectiveness and promotes sustainable business practices, contributing to discussions on environmental justice and equity [21-25].
Review of Relevant Studies and Literature Gaps
Extensive research on environmental protection investments spans macro and micro levels.
These authors [26] at the macro level highlighted the link between economic growth and increased environmental protection investment. However, Saygili [27] emphasized the government’s pivotal role in boosting industry awareness and enterprise investments in environmental protection. The threshold effect of industry-specific environmental regulation intensity on green investments, finding an “inverted U-shaped” relationship, is being explored by Lin et Chen [28]. Some scholars supported the impact of government-led environmental measures on enterprise investments, advocating for a robust oversight mechanism [29]. Feng et al. [30] stressed the influence of modernization and inclusive finance approaches on enterprise environmental protection investments.
At the micro level, Boiral et al. [31] analyzed how managers’ qualities influence attitudes toward social responsibility. Furthermore, they linked enterprise internal control with environmental protection investments and compared environmental protection and R&D investments, concluding that the former has a more significant impact on industrial enterprise value [32, 33].
Existing research falls short of comprehensively understanding how specific internal environmental factors influence corporate investments in environmental protection and lacks comparative analyses of the effectiveness of penalties versus subsidies. This study seeks to bridge these gaps by examining A-share-listed companies in Shanghai and Shenzhen over the period from 2010 to 2020. It aims to investigate the differential impacts of environmental protection penalties and subsidies, taking into account factors such as property rights and macro-regulatory elements like environmental regulations. By offering a nuanced view of these variables and examining their interrelationships and individual effects, the study aims to provide a thorough assessment of their influence on corporate environmental protection investments.
After the introduction, where the groundwork was laid to provide an essential context and delineate the scope of the research, the discussion deepened by reviewing relevant studies, identifying gaps in the existing literature and highlighting the contribution this paper intends to make. Then, the theoretical framework and research hypotheses are presented, offering a foundation for the study’s methodology and anticipated findings. The Materials and Methods are thoroughly described, focusing on variable selection and variable measurement, ensuring a clear understanding of the research design and analytical approach. The core findings and their implications are explored in Results and Discussion, where the data analysis is presented and interpreted in the context of the research questions and hypotheses. Conclusions summarise the key findings, discussing their policy implications, and suggesting directions for future research, thereby encapsulating the study’s contributions to the field and its relevance to both academic and practical applications.
Theoretical Framework and Research Hypotheses
Environmental Protection Penalties and Environmental Protection Investments
Environmental protection penalties directly impact enterprise finances through fines, stimulating environmentally responsible development [34]. However, these penalties may disrupt investment activities and reduce foreign direct investments due to compliance costs and green credit policy restrictions [35]. Conflicting perspectives exist on whether penalties stimulate or hinder environmental protection investments. This article posits:
H1: An increase in environmental protection penalties promotes enhanced environmental protection investment.
H2: An increase in environmental protection penalties impedes the enhancement of environmental protection investment.
Environmental Protection Subsidies and Environmental Protection Investment
Environmental protection subsidies generally contribute to increased environmental protection investment by bridging financial gaps for enterprises facing long-term, high-cost, and uncertain returns [36]. The combination of environmental regulations and subsidies effectively bolsters enterprise environmental protection investments [37]. However, challenges such as limited financial resources and difficulties in verifying recipient enterprises’ environmental efforts may hinder subsidy effectiveness. This article posits:
H3: An increase in environmental protection subsidies promotes enhancements in environmental protection investment.
H4: An increase in environmental protection subsidies does not substantially impact the enhancement of environmental protection investment.
Environmental Regulation and Environmental Protection Investment
To advance green development, the Chinese government has introduced environmental protection regulations aimed at supervising and guiding enterprise behavior [38]. Environmental regulation can be control-oriented or incentive-oriented in influencing enterprises’ green innovation [39].
The existing literature offers diverse views on the relationship between environmental regulation and enterprises’ green innovation. Some argue that stringent regulation increases enterprises’ development costs, diverting resources from environmental protection investments [40]. Therefore, strong regulations might even lead to bribery practices to alleviate pressure. Conversely, increased regulation aligns enterprise development with societal needs, fostering long-term growth [41].
Uncertainty persists on whether environmental regulation acts as a catalyst or deterrent in the government-enterprise environmental protection relationship. The study posits the following assumptions:
H5: Under controlled conditions, environmental regulation positively regulates the relationship between government environmental efforts and enterprise environmental protection investments.
H6: Under controlled conditions, environmental regulation negatively regulates the relationship between government environmental efforts and enterprise environmental protection investments.
H7: Under controlled conditions, environmental regulation has no significant regulatory relationship between government environmental efforts and enterprise environmental protection investments.
H8: Under controlled conditions, environmental protection penalties promote improvements in enterprise environmental protection investments compared to subsidies.
H9: Under controlled conditions, environmental protection subsidies promote improvements in enterprise environmental protection investments compared to penalties.
These assumptions guide further research to understand the nuanced impact of environmental regulation on the government-enterprise environmental protection relationship.
Property Rights and Environmental Protection Investment
Scholars extensively explore how property rights impact government subsidies, innovation performance, and environmental conduct in both state-owned and non-state-owned enterprises [42, 43]. State-owned enterprises, possessing greater financial resources, are expected to align with government directives, actively engage in green initiatives, and contribute to the circular economy [44]. Non-state-owned enterprises, to comply with government policies, often exhibit greater responsiveness to environmental controls and allocate substantial investments in environmental protection [45]. Given these perspectives, the nature of property rights significantly shapes the relationship between government environmental actions and enterprise environmental investments. The study posits:
H10: Under controlled conditions, state-owned enterprises, compared to non-state-owned enterprises, exhibit a positive regulatory association between government environmental actions and enterprise environmental investments.
H11: Under controlled conditions, state-owned enterprises, compared to non-state-owned enterprises, demonstrate a negative regulatory association between government environmental actions and enterprise environmental investments.
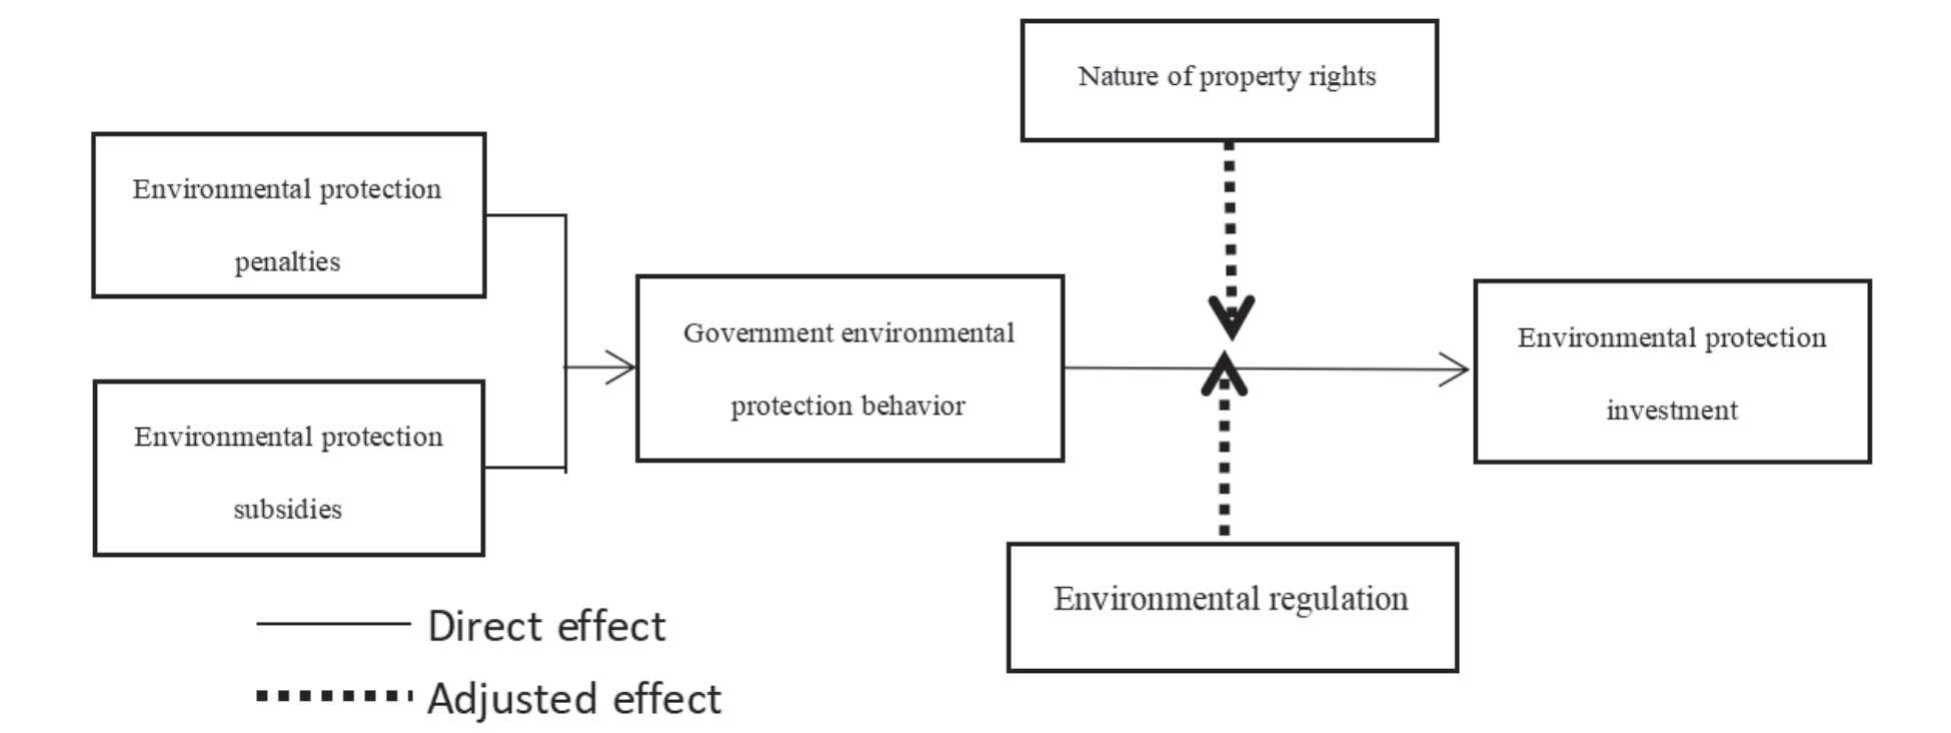
This theoretical framework establishes the foundation for further research exploring how property rights influence the dynamic between government environmental protection efforts and enterprise environmental protection investments, as represented in Fig. 1.
Materials and Methods
Variable Selection
This study utilized data from Shanghai and Shenzhen A-share listed companies spanning the years 2010 to 2020.
The final research sample was determined through a comprehensive screening process. Firstly, to ensure the overall integrity of data, enterprises with incomplete or sporadic data were removed. Secondly, companies lacking essential control data variables were excluded from consideration. Thirdly, entities designated as “ST” due to experiencing abnormal operating conditions, along with “*ST” and “PT” enterprises, were eliminated. Finally, data from financial and insurance enterprises was also omitted. The financial data of the listed companies primarily originated from the Wind and CSMAR databases, while environmental regulation data was sourced from the National Bureau of Statistics and the China Environmental Yearbook. Information concerning enterprise environmental protection subsidies and environmental protection penalties was derived from Guotai’an data, following a meticulous screening process. After this comprehensive screening procedure, our study comprised a dataset of 3,823 effective sample enterprises, resulting in a total of 22,377 valid observational data points for our analysis.
Variable Measurement
Explained Variables
The dependent variable in this research pertains to the “Total Environmental Protection Investment (EPI)” undertaken by enterprises. Using the methodologies employed by Cui An [46] and Yu Lianchao [47], we have opted to gauge this variable using the absolute magnitude of environmental protection investment. This encompasses capital outlays associated with various environmental protection endeavors, including expenditures related to the modification of production lines to meet environmental standards and the procurement of clean production equipment categorized under the “construction project” domain.
Explanatory Variable
The Environmental Penalty (Penalty) in this study, as per the practices outlined by Mengyao [48], is quantified by measuring the number of penalties imposed on enterprises for violations of environmental regulations. To mitigate the impact of potential variations in data, these penalty counts are subjected to a natural logarithmic transformation. The number of environmental protection penalties serves as an indicator of the government’s enforcement of environmental regulations within the industry. Government Environmental Protection Subsidy (GES), on the other hand, is derived from detailed data regarding government subsidy projects, as annotated in the annual reports within the Guotai’an database.
Adjustment Variables
Environmental regulation (ER) in this study is determined by employing a methodology that draws on the practices outlined by Tang Guoping [49] and Hao et Zhang [50]. To standardize the assessment of environmental control intensity and minimize variations stemming from regional development levels and geographical disparities, a comprehensive index of environmental regulation is computed. This index is derived using the entropy power method and takes into consideration data on the emissions of three waste categories across all provinces in China. Specifically, it primarily relies on the weightings associated with industrial wastewater emissions, industrial SO2 emissions, and land industrial soot emissions, which are regarded as quasi-chemical indicators of environmental regulation.
Control Variables
This study draws upon prior research findings to identify and designate the following variables as control factors: enterprise size (Size), total asset turnover rate (ATO), asset-liability ratio (Lev), top ten equity concentrations (Top10), total asset net profit margin (ROA), agency cost (Ag Encost), enterprise growth (Growth), Tobin Q value (TobinQ), and enterprise age (Age). Comprehensive definitions and measurement details for each of these variables are provided in Table 1.
Based on the above assumptions, the following measurement models are constructed:
(1)
(2)
where α0 represents the intercept term; α1, …, α10 represents the regression coefficient, μit represents the error term, i represents the cross-section individual, t represents the time, t = 1, ..., 10, indicating a total of 11 years from 2010 to 2020. The given error term (+μit) is assumed to be normally distributed at zero mean value and constant variance [51, 52].
It is worth noting that when the connection between the dependent variable and the explanatory variable can be influenced by other factors, these are referred to as control variables. In simpler terms, control variables are introduced to account for how additional factors may impact the relationship between the dependent and independent variables [53]. To conduct a more comprehensive evaluation of the influence of environmental protection penalties and environmental protection subsidies on enterprise environmental protection investments, we introduce the following model forms alongside Model (1) and Model (2) to control for environmental regulation and the nature of property rights:
(3)
(4)
(5)
(6)
Table 1.
Definitions of variables.
Results and Discussion
Descriptive Statistics and Correlation Analysis
In this study, the Stata16 software was used for conducting descriptive statistical analyses of the data, with the results presented in Table 2. To aid in a clearer presentation of the research data, total assets (Size) were expressed in millions, while the top ten equity concentrations (Top10) were represented in percentiles. Due to the presence of incomplete data from some enterprises, such data were excluded, and a comprehensive range of enterprise data was analyzed.
The data summarized in Table 2 reveal that the average logarithm of environmental protection investment (EPI) for the sampled enterprises stands at 4.543. Concurrently, the average environmental protection penalty score is relatively low at 0.003, suggesting that, on average, enterprises have incurred few environmental protection penalties. In contrast, the average score for environmental protection subsidies is considerably higher at 0.317, and the average score for environmental regulation is 0.648. The figures show that a smaller percentage of sampled businesses have received penalties for environmental violations, while a larger number have received subsidies for environmental protection. This pattern suggests that China favors incentive-based measures for promoting green development and environmental protection.
Furthermore, when analyzing enterprise-specific data, significant variability is observed in multiple variables, such as the total asset turnover rate (ATO), asset-liability ratio (Lev), top ten equity concentrations (Top10), enterprise growth (Growth), agency cost (Agencost), and enterprise age (Age). This variation highlights the diverse nature of the enterprises in terms of their size and business strategies, reflecting the heterogeneity within the sample.
The correlation analysis results in Table 3 provide informative interpretations and comparisons to environmental investment and regulation research. Environmental protection investment (EPI) and government environmental subsidies (GES) are positively correlated at 1%, with a coefficient of 0.329. Higher government subsidies may raise corporate environmental spending. This supports Wang’s [54] findings that government incentives boost enterprises’ eco-friendly investments. EPI, however, correlates negatively with environmental restrictions (ER) at –0.066 at the 1% significance level. This suggests that tougher environmental rules may reduce business environmental investment due to compliance costs. This matches Ren et al. [55], who found comparable trends. The investigation also found a greater positive association between EPI and state-owned companies (SOEs) at 0.155 and 1%. SOEs are more likely to invest in environmental protection than private enterprises, indicating that ownership affects green investment decisions. This supports Wang et Lei [54], who found that government policies motivate SOEs to invest in the environment. The data also shows that EPI is positively connected with company size, leverage, and age. This indicates that larger, more indebted, and older enterprises invest more in environmental protection. Finally, the low correlations between independent variables support the no-multicollinearity assumption for regression analysis [56]. Previous empirical models, such as Yang et Liu [57], support the findings.
Table 2.
Descriptive statistics.
Table 3.
Correlation analysis.
The variance inflation factor (VIF) analysis in Table 4 further verifies the absence of multicollinearity issues in the data. All VIF values are below the cutoff of 10, with a mean VIF of 1.260. This satisfies the assumption of no high correlations among predictor variables required for the regression analysis.
Impact of Environmental Penalties and Subsidies
Environmental Penalties
The regression coefficient for environmental penalties (Penalty) is positive and statistically significant at the 1% level in all models. This indicates that higher penalties imposed by the government are associated with increased environmental protection investments by companies. Specifically, a 1% increase in penalties leads to a 0.011% to 0.014% increase in corporate environmental investments. This finding is consistent with past studies such as Wen et al. [58], which also found a significant positive relationship between environmental penalties and corporate green investments. The deterrent effect of penalties encourages firms to invest in environmental protection to avoid being penalized for non-compliance.
Environmental Subsidies
The regression coefficient for environmental subsidies (GES) is also positive and significant at a 1% level across the models. A 1% increase in subsidies is associated with a 0.092% to 0.098% increase in corporate environmental investments. This aligns with the findings of Zhang et al. [59], who demonstrated that government subsidies effectively motivate companies to devote more resources to environmental sustainability initiatives. Overall, the results provide strong evidence that both environmental penalties and subsidies are effective policy tools to promote corporate environmental protection investments in China.
The coefficient for environmental protection penalties among enterprises is a notable 2.596, showing significance at the 1% level, while the coefficient for environmental protection subsidies is 0.744, also significant at the 1% level. This indicates that both environmental protection penalties and subsidies significantly influence the enhancement of enterprises’ environmental protection investments, confirming hypotheses 1 and 3. The results are in line with the previous study [60]. However, considering the relative magnitudes of these coefficients, it is evident that environmental protection penalties are more effective in promoting enterprise environmental protection investments compared to subsidies, thereby validating hypothesis 8.
Influence of Environmental Regulation on Corporate Investment in Environmental Protection
Role of Environmental Penalties and Subsidies under Enhanced Regulation
The findings from the hierarchical regression analysis were significant (Table 6). The interaction between environmental protection penalties and environmental regulation (Penalty × ER) showed a positive regression coefficient (β = 2.093, P<0.05), indicating that environmental regulation reinforces the relationship between penalties for environmental protection and investments in environmental protection. In a similar vein, the interaction of environmental protection subsidies and environmental regulation (GES × ER) revealed a positive coefficient (β = 2.32, P<0.1), suggesting that environmental regulation effectively strengthens the link between subsidies for environmental protection and investments in environmental protection. These results offer strong support for hypothesis 5.
Table 4.
Estimation of VIF.
Table 5.
Regression results for impacts of environmental penalties and subsidies on corporate environmental investments.
Advancing Corporate Environmental Responsibility
As China’s environmental regulatory framework evolves, enterprises are starting to view environmental challenges as avenues for profit and innovation, resulting in increased investments in environmental protection (Table 6). Previous studies also found similar results [61, 62]. The relatively modest overall level of environmental protection investments in Chinese enterprises implies that well-crafted environmental regulatory measures can effectively encourage companies to increase their resource allocation towards environmental protection. Wang et al. [63] has previously highlighted the significant role of government policy in motivating corporate environmental investment.
Table 6.
Regulatory role of environmental regulations.
Regulatory Role of Environmental Regulation
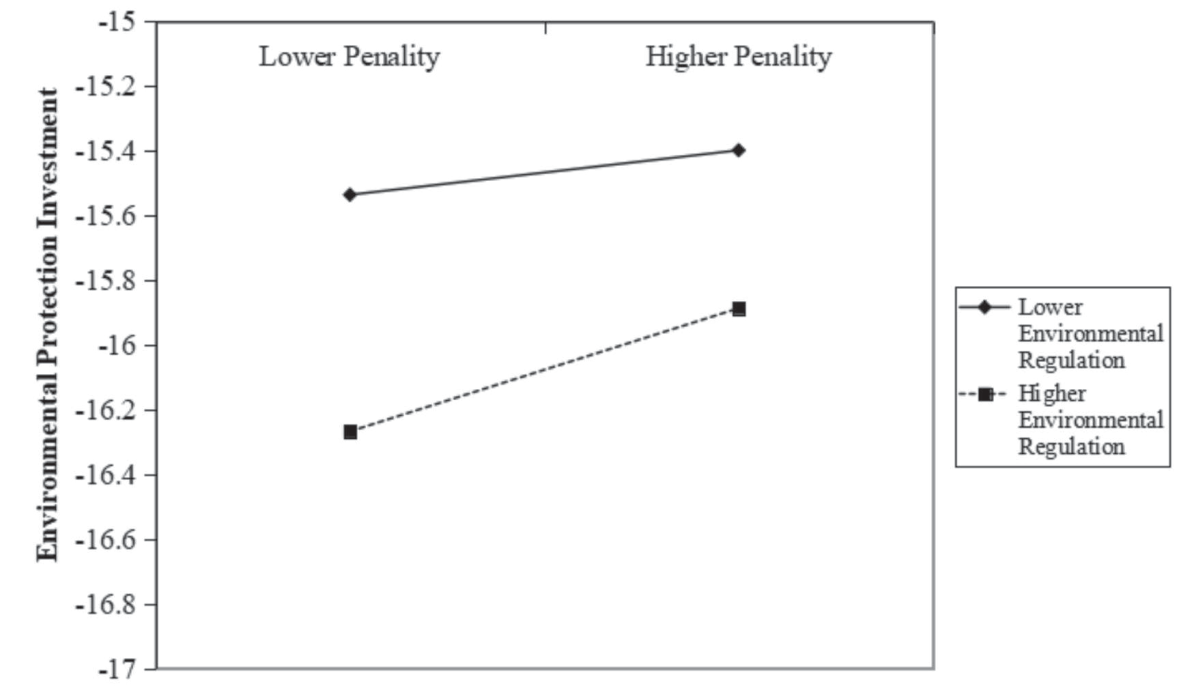
Environmental regulation moderates environmental penalties, as shown in Fig. 2. This graphic shows the dynamic relationship between regulatory strictness and business environmental protection spending. Penalties on corporate environmental investments increase as environmental legislation tightens, a favorable trend. This shows that severe rules push companies to prioritize environmental sustainability to avoid penalties. This graphic may also represent the tipping point where regulatory pressure becomes significant, demonstrating the optimal regulation level for environmental goals.
Regulatory Role of Government Environmental Subsidies (GES)
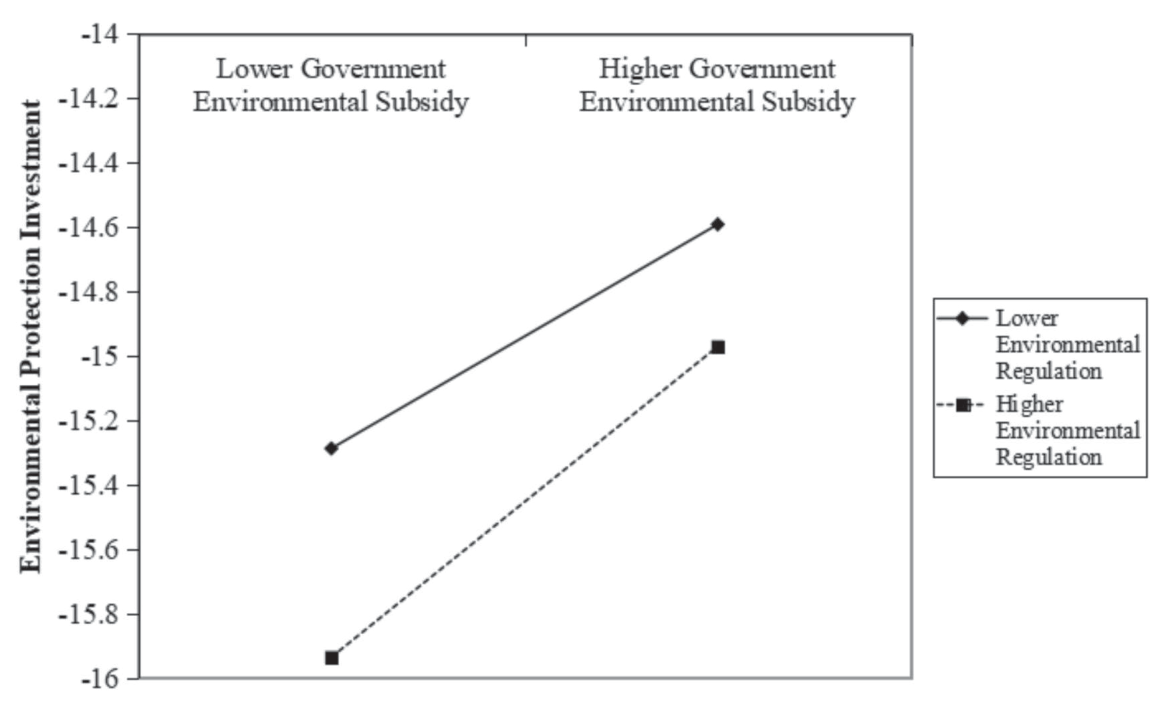
Fig. 3 indicates that government environmental subsidies (GES) encourage company environmental spending when environmental restrictions tighten. This implies that subsidies can help enterprises meet environmental goals in heavily regulated environments. The image also shows how regulatory context affects financial incentives for environmental sustainability.
Influence of Property Rights on Corporate Environmental Investment Decisions
Impact of Environmental Penalties and Property Rights
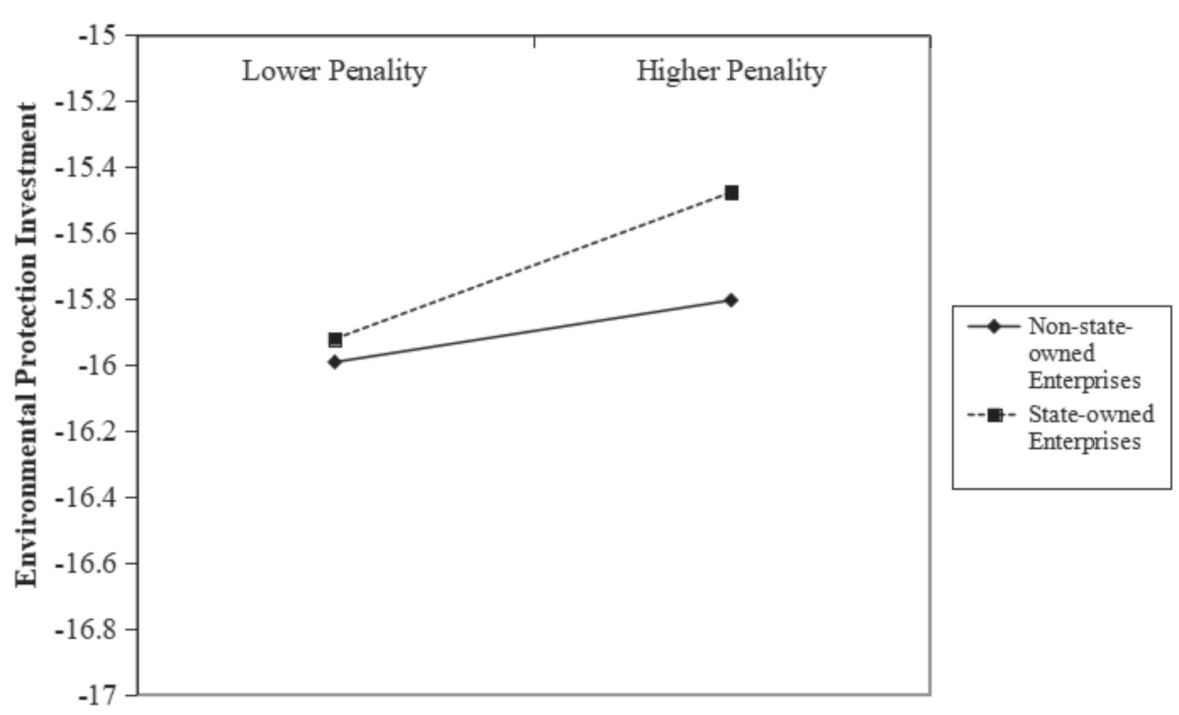
Table 7 shows how environmental penalties affect property rights. A regression coefficient of 2.562 indicates a significant interaction between environmental penalties (Penalty) and property rights (Soe) at the 5% level (P < 0.05). Property rights dramatically improve the link between environmental protection penalties and investments. Due to their better access to resources and conformity with government policy, corporations, especially SOEs, are likely to boost their environmental protection investments in reaction to penalties. That property rights increase the influence of environmental fines on environmental investments is consistent with Zhao et al. [64], who found that state-owned businesses (SOEs) are more responsive to government laws, including penalties. Table 7 illustrates environmental fines and property rights. At the 5% level (P < 0.05), the regression coefficient of 2.562 shows a significant interaction between environmental penalties (Penalty) and property rights (Soe). Property rights significantly strengthen the environmental protection penalty-investment relationship. In response to penalties, firms, especially SOEs, may increase their environmental protection efforts due to their improved resource access and government policy compliance. Property rights increase environmental fines’ impact on environmental investments, supporting Zhao et al. [64], who found that state-owned firms (SOEs) are more responsive to government rules, including penalties.
Role of Environmental Subsidies and Property Rights
Table 7 reveals a substantial positive relationship of 0.257 (P<0.1) between subsidies (GES) and property rights (Soe). This suggests that property rights favorably affect environmental protection subsidies and investments. Due to their unique characteristics and stronger linkages to government policy, state-owned firms may be more responsive to environmental subsidies, resulting in larger environmental sustainability investments than non-state enterprises. The environmental subsidies encourage SOEs to invest in environmental protection. SOEs achieve economic, social, and environmental goals, which contributes to this. In contrast, He et al. [65] found that subsidies are effective, but financial restrictions can increase their influence on private firms’ environmental protection spending.
Exploring the Effect of Property Rights on The Impact of Environmental Penalties
The given Fig. 4 shows that higher government environmental subsidies (GES) lead to more corporate environmental protection investments (EPI). The positive relationship between GES and EPI is amplified by environmental regulation (ER). When ER is more stringent, the impact of GES on EPI is greater, indicating that strict regulations reinforce the motivational impact of subsidies on corporate green investments. In conclusion, the figure highlights the importance of a strong regulatory framework for promoting pro-environmental corporate behavior through government incentives.
Understanding the Role of Property Rights in the Effectiveness of Environmental Subsidies
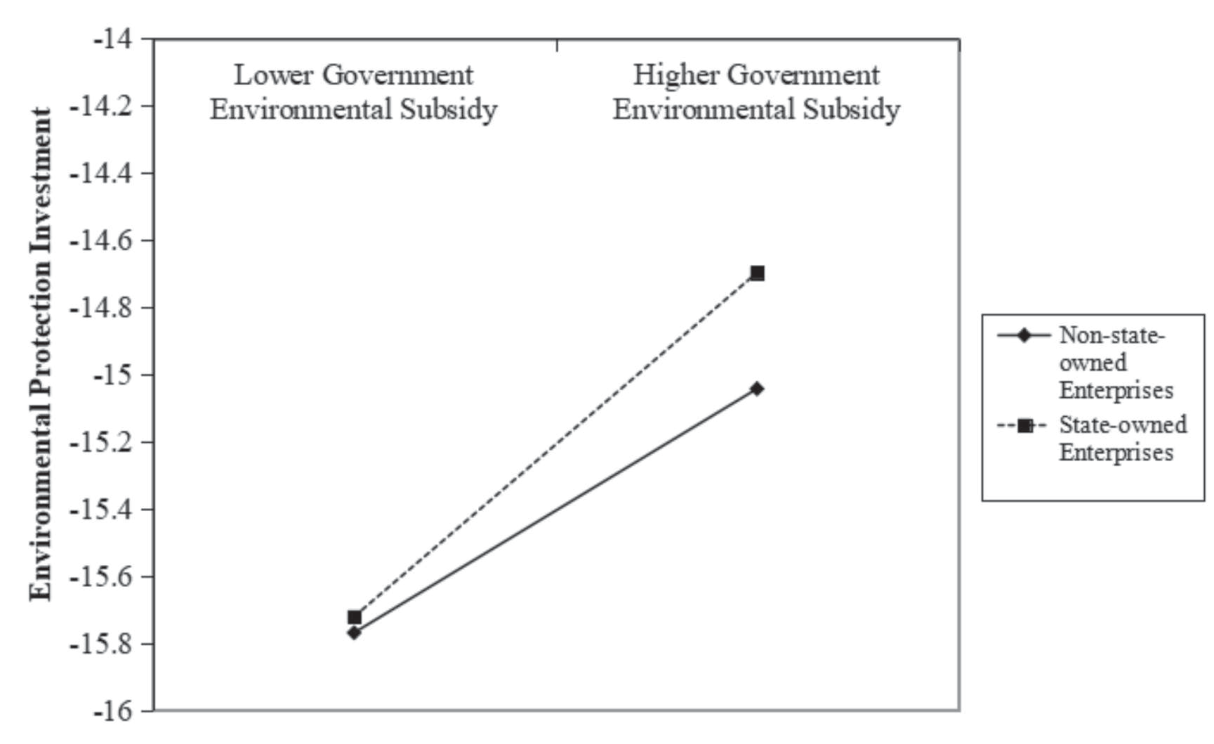
Fig. 5 shows the moderating effect of property rights on the relationship between government environmental subsidies (GES) and corporate environmental investments (EPI). The upward-sloping lines indicate that higher GES is associated with increased EPI for both state-owned enterprises (SOEs) and non-SOEs. However, the slope is steeper for SOEs compared to non-SOEs. This means the marginal effect of environmental subsidies on environmental spending is greater for SOEs. The visualization provides evidence that SOEs respond more actively to sustainability subsidies by investing more in environmental protection initiatives compared to non-state-owned firms. Overall, the figure highlights how the nature of property rights regulates the effectiveness of environmental subsidies in shaping pro-environmental corporate conduct. State ownership enhances the role of government incentives in driving corporate environmentalism.
Table 7.
Regulatory role of nature of property rights.
Robustness Test
In the pursuit of confirming the impact of environmental protection subsidies and penalties on enterprises’ green environmental investments, adjustments were made to the explanatory variables. Specifically, the variable “environmental protection penalty” was transformed into the “environmental protection penalty tendency index,” represented as a binary variable. This modification distinguished enterprises that had incurred environmental protection penalties during the year, assigning them a specific value. A similar approach was applied to subsidies. As observed in Table 8, the regression coefficients for environmental regulation, environmental protection penalties, and environmental protection subsidies remained consistent with the original empirical findings regarding their positive and negative directions.
Consequently, this study restricted the sample period to 2017-2020 and employed a fixed-effect model for reevaluation. The results, as shown in Table 8, upheld the stability of the regression coefficients for environmental regulations, environmental protection penalties, and environmental protection subsidies, consistent with the original empirical outcomes.
Table 8.
Robustness test
This reaffirmed the assertion that environmental protection penalties exert a stronger influence on promoting environmental protection investments compared to environmental protection subsidies, aligning with the research paper’s central conclusions. Considering the characteristics of left-truncated end data for enterprise-level environmental protection investments, the study opted for a robustness test using the xttobit model regression. The outcomes, presented in Table 8, demonstrated that both environmental protection penalties and environmental protection subsidies had a significant and positive impact on enterprises’ environmental protection investments, as indicated by the 1% significance level. The analysis revealed that environmental protection penalties were more effective than subsidies in driving environmental protection investments. These findings corroborated the core research conclusions of the paper. This section of the article performs robustness tests by altering the calculation method of explanatory variables, narrowing the sample scope, and replacing the regression model. These tests consistently validate the hypotheses presented in the article, specifically hypotheses 1 and 3. Furthermore, the results consistently indicate that environmental protection penalties are more effective than environmental protection subsidies in driving enterprises’ environmental protection investments. This reaffirms the validity of hypothesis 8, emphasizing the stronger impact of penalties as incentives for environmental responsibility within the business context.
Conclusions
Employing data from A-share listed firms in Shanghai and Shenzhen covering the years 2010 to 2020, this research aimed to dissect the influence of environmental penalties and subsidies on corporate environmental investments. In addition, it delved into the roles of regulatory frameworks and the structure of enterprise ownership in shaping the response to government environmental initiatives. Through rigorous variable selection and measurement methodologies, including the exclusion of firms with incomplete data, consideration of financial and environmental regulation data, and the application of specific models to assess the impact of penalties, subsidies, and regulatory intensity, the study offered a nuanced analysis of these dynamics.
The conclusion drawn from this analysis highlighted that both punitive measures and incentives play crucial roles in encouraging businesses to invest in environmentally friendly practices. Interestingly, the study found that penalties were more effective than subsidies in promoting environmental investments. Furthermore, the influence of environmental regulations was seen to positively moderate the interaction between government policies and corporate environmental commitments, enhancing the effectiveness of governmental interventions. The ownership structure of enterprises further influenced their environmental investment behaviors, with state-owned enterprises showing a more pronounced reaction to both penalties and subsidies. This underscores the differential impact of government policies on enterprises based on their ownership status, suggesting that state-owned entities are more influenced by such policies.
The study’s findings contribute valuable insights into the effectiveness of different government measures in driving corporate environmental responsibility, emphasizing the significance of tailored regulatory and incentive approaches to foster greater environmental stewardship within the corporate sector. Considering these outcomes, strategic recommendations include:
Judicious use of environmental penalties to motivate less proactive firms, with local governments enhancing governance capacity. A tailored approach combining penalties and subsidies can optimize enforcement efficiency.
Flexible application of regulations based on local contexts, with stringent oversight systems to incentivize green development. Focused efforts on state-owned firms while also motivating private companies through supervision and incentives.
Enterprises acknowledge green development’s pivotal role by prioritizing eco-friendly practices and aligning with government policies as opportunities. State-owned companies are taking leadership roles in sustainability.
These recommendations aim to foster collaboration between government initiatives and corporate actions to advance China’s green development collectively.
This study, while providing significant insights into the effects of environmental penalties, subsidies, and regulatory frameworks on corporate environmental investment decisions, faces certain limitations that suggest directions for future research. One limitation is the focus on A-share listed firms in Shanghai and Shenzhen, which may not fully represent the diversity of corporate behaviors across different regions and industries in China. The period of analysis from 2010 to 2020, while extensive, does not capture the long-term effects of recent policy changes or the ongoing evolution of corporate environmental strategies. Additionally, the study’s reliance on publicly available data may limit the depth of understanding of internal corporate motivations and the nuanced mechanisms through which environmental policies influence corporate behavior.
Future studies could address these limitations by expanding the scope of research to include a wider range of industries and regions, thereby capturing a more comprehensive picture of the corporate response to environmental policies in China. Longitudinal studies extending beyond 2020 could examine the sustainability of observed trends and the impact of newer policies. Qualitative research methods, such as interviews or case studies, could provide deeper insights into corporate decision-making processes and the internal and external factors influencing environmental investments. Additionally, further investigation into the role of innovation in enhancing corporate environmental performance could shed light on the pathways through which firms can achieve both environmental and economic goals.

