

Introduction
The Chinese government has clearly proposed to accelerate the green transformation of the economic development mode and actively and steadily promote the goal of carbon peaking and carbon neutrality, aiming to mitigate the increasingly prominent contradiction between resource constraints and environmental pollution [1, 2]. In this context, the green transformation and upgrading of real enterprises has become an urgent issue. Green innovation is the premise for green transformation of enterprises, and effective green innovation can reduce pollution, improve resource utilization efficiency, and mitigate the negative impact of economic activities on the environment, with the dual characteristics of knowledge spillover and positive externality [3, 4]. Therefore, balancing the relationship between economic growth and ecological environment requires attention to the role of green innovation [5]. However, due to the characteristics of green innovation activities such as large investment, long cycle time, high risk and strong externality, enterprises pursuing profit maximization usually lack the willingness to green innovation [6]. Especially since the economy has entered the new normal, real enterprises have narrowed their own profit margins due to weakening cost advantages, prominent technological bottlenecks and imbalance in supply and demand structures, while the financial industry has gained excess profits due to rapid market development and open financial interest rate regulation [7]. In this context, investment in financial assets becomes an important way for real enterprises to gain profits. Given the relatively limited resources of firms, what is the impact of financial asset investment on their green innovation activities? It has been shown that financing constraints can limit the green innovation ability of enterprises [8], and financial investment by real enterprises can make their profit sources no longer limited by traditional product business channels [9], thus providing a certain financial base for their green innovation activities. However, under the premise that the overall amount of capital is relatively limited, the investment in financial assets of real enterprises can also crowd out the investment in fixed assets and R&D [10-13], which hinders corporate green innovation [14]. In addition, enterprises’ green innovation decisions will also be constrained by the external environment. With the increasing attention to environmental protection, the Chinese government has formulated various environment-related policies, designed corresponding market transaction mechanisms, and the public’s awareness of green environmental protection is gradually increasing. These external environmental regulatory tools can also constrain and guide the green innovation activities of enterprises to a certain extent [15-18].
There is no specific research on how the financialization of real firms affects green innovation. The existing studies related to the factors influencing corporate green innovation have focused on the external institutional environment, internal resources and capabilities of firms, and executive characteristics and cognitive perspectives. Among them, the studies from the external institutional environment perspective focus on the influence of policy-based institutional environment and non-policy-based institutional environment on green innovation [19-22]. Most of the relevant studies based on policy-based institutional environment affirm the positive role of regulatory policies such as environmental protection laws and financial policies such as green credit policies in green innovation [23- 25]. The relevant studies based on non-policy-based institutional environment mainly examine the impact of market-based environmental regulatory instruments such as carbon emissions trading and SO2 emissions trading on green innovation [26-28]. Research under the perspective of internal resources and capabilities focuses on exploring the differential impacts of different types of resources and capabilities within companies on green innovation. Specifically, research on the impact of internal firm resources on green innovation explores the impact of, for example, financing constraints, human resource management, intellectual property rights, and government supportive resources on green innovation. It has been found that financing constraints limit the green innovation capability of enterprises, especially in private enterprises [8]. Green human resource management, represented by green recruitment, hiring, training, and performance evaluation, can promote green innovation and achieve sustainable environmental performance and development [29, 30]. Firms with intellectual property rights and government support can significantly promote green process innovation and green product innovation [31, 32]. Studies on the factors influencing corporate green innovation from the perspective of internal capabilities focus on the differential impact of internal management capabilities such as absorptive capacity, corporate governance, quality management, and digital transformation on green innovation. More specifically, it has been found that absorptive capacity plays a key role in the sustainability and application of green innovation in SMEs [33]. Firms with poorer governance generate fewer green patents relative to other forms of innovation and the negative effect between these two is greater for firms with smaller institutional ownership, fewer green patent inventories, and stronger financing constraints [34]. Quality management has a significant negative impact on the probability of firms implementing green technological and managerial innovations, which can be effectively mitigated by environmental regulation [35]. Digital transformation can improve firms’ green innovation performance, and for firms with excellent digital performance, they need to ensure sufficient digital operational output and digital innovation input, while for firms with poor digital performance, more attention should be paid to managing digitalization so as to better leverage the contribution of digital transformation to the green innovation performance [36]. In addition, research on the factors influencing corporate green innovation from the executive characteristics and cognitive perspectives focuses on examining the impact of differences in characteristics and cognitive differences of executive teams and core members on corporate green innovation. Specifically, studies under the executive characteristics perspective have examined the impact of executive team experience, management power, and CEO political connection on green innovation [37-39]. Besides, a few studies have also explored the impact of executive cognitive differences on corporate green innovation [40].
Through the literature review on the influencing factors of corporate green innovation, we can see that existing studies mainly focus on three perspectives: external institutional environment, internal resources and capabilities, and executive characteristics and cognition, and the identification of the influencing factors of corporate green innovation has been relatively systematic and comprehensive. However, there are relatively few studies based on the perspective of internal financial resources, and there is a lack of in-depth contextual analysis. Corporate green innovation activities need the effective support of financial resources, and unreasonable financial resource allocation may inhibit green innovation activities that are beneficial to corporate sustainable development. Then, what is the impact of financialization on corporate green innovation? What is its intrinsic influence mechanism? How does this impact differ in heterogeneous environmental regulatory contexts? The answers to these questions cannot only enrich the research on the influencing factors of corporate green innovation from a micro-finance perspective, but also guide the green development practices of real enterprises. In view of this, this paper empirically analyzes and examines the impact and mechanism of financialization on corporate green innovation, and further investigates the differential impact of heterogeneous environmental regulation on the relationship between the two, using Chinese A-share listed companies from 2007 to 2020 as a research sample. It provides useful insights for perfecting corporate green innovation investment decisions, improving the regulatory system of financialization, and promoting regional green development.
The contributions of this paper are: (1) Existing studies on the influencing factors of green innovation from the perspective of internal resources have mainly explored the effects of financing constraints, intellectual property rights and political connections on green innovation. For example, Yu et al. (2021) found that financing constraints limited firms’ green innovation capabilities, especially in private firms [8]. Zhang et al. (2022) found that political connected state-owned enterprises promoted green patent authorizations through corporate entrepreneurship strategies [32]. Different from these findings, the marginal contribution of this paper is to explore the impact of financialization on corporate green innovation, which to a certain extent enriches the research on the factors influencing corporate green innovation;
(2) Existing research on the relationship between environmental regulation and corporate green innovation focuses on examining the direct impact of environmental regulation on corporate green innovation. For example, Liu et al. (2021) investigated the impact of China’s new Environmental Protection Law on the green innovation of listed companies in high-polluting industries [16]. Xie et al. (2017) examined how different regulatory instruments and the relative stringency impacted “green” productivity [22]. Unlike existing studies, the marginal contribution of this paper is to consider the role of environmental regulation as an external contextual factor rather than a direct driving factor, deepening the research on the relationship between environmental regulation and corporate green innovation; (3) Few existing studies on green innovation driving factors opened the “black box” of internal mechanisms and explored the intrinsic influencing channels in depth. The marginal contribution of this paper is to reveal the main mechanism of financialization inhibiting corporate green innovation from two channels: innovation input and financial constraints. (4) Few studies provided in-depth analyses of different types of green innovation and differentiated industry and regional contexts. While the results of our extended analysis provide an in-depth analysis of the differential effects of financialization on different types of green innovation and green innovation of enterprises in different industries and regions, which deepens the related research and helps to understand the relationship between financialization and green innovation in a more comprehensive way. Overall, the findings of this paper not only help to improve the internal investment decision-making mechanism of enterprises, but also provide certain insights to improve the regulatory mechanism of financialization.
Theoretical Basis and Hypothesis
Financialization and Corporate Green Innovation
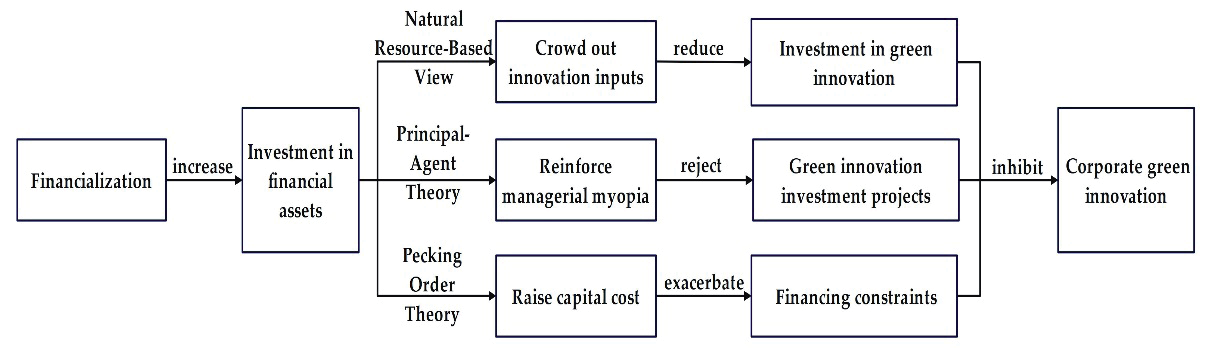
Green innovation can, to a certain extent, achieve a long-term balance between strategic objectives such as shareholder value and sustainable development, and help companies gain competitive advantage [41]. Therefore, many companies include green innovation in their strategic planning. However, green innovation activities are usually characterized by large investment, long cycle time, high risk and strong externalities, which often lead to serious financing constraints [42, 43]. Since China’s economy has entered the period of new normal, the downward pressure on the economy has increased and the profitability of industrial investments has decreased, while financial investments have shown high profitability due to the rapid market development and the liberalization of financial interest rate control [7]. In this context, more and more enterprises invest their relatively limited cash surpluses in the financial sector in order to obtain excess profits, which means implementing financialization decisions. The main motive of financialization of Chinese real enterprises is capital profit-seeking, and the financialization decision of enterprises based on profit-seeking motive will pay more attention to the investment return of financial assets, strengthen management short-sightedness, reduce the capital investment in R&D activities such as green innovation, and intensify the financing constraint of enterprise green innovation activities, thus affecting enterprise green innovation in at least the following three aspects.
Based on the Natural Resource-Based View, companies can use their own resources and capabilities to achieve environmental management goals to gain competitive advantages, such as, reducing costs by reducing pollution and waste, improving production efficiency, and integrating green development concepts in the product de-sign and development process [44, 45]. Green innovation is a strategic management goal for enterprises to achieve sustainable development and one of the important ways for them to gain competitive advantage [46]. Corporate green innovation requires sufficient R&D capital investment to provide a resource base for its smooth implementation, so as to resist the uncertainty risk in the process of innovation activities. Financialized enterprises usually aim at profit maximization, and their excessive pursuit of financial profits will make them focus more on short-term financial gains and neglect the positive impact of long-term investment in green innovation projects on the long-term interests and sustainable development of enterprises [47]. Under the premise that the total amount of capital available to enterprises is relatively limited, investment in financial assets will have a “crowding-out effect” on innovation investments with high uncertainty and long investment cycles, that is, reduce the capital investment in green innovation activities [48, 49], which is contrary to the continuous and stable financial support required for green innovation activities. Therefore, financialization will crowd out innovation investment, thus inhibiting green innovation in enterprises.
Based on Principal-Agent Theory, managers as agents may maximize their personal interests based on self-interest motives at the expense of their principals’ interests when exercising their fiduciary responsibilities to the board of directors. Therefore, in order to meet the assessment or incentive conditions of the board of directors, avoid the threat of dismissal, and better realize personal interests, managers may invest limited corporate capital in the financial sector to pursue rapid short-term performance improvement, while the short-term returns of financial assets will further strengthen managers’ myopia [50-52]. Corporate green innovation activities are usually characterized by a long investment return cycle and a high degree of uncertainty, and managers’ myopia will make them more likely to ignore the environmental benefits brought by green innovation and reject green innovation projects that can bring positive benefits to the company in the long run [53]. Therefore, financialization will exacerbate managerial myopia and make managers reject green innovation projects, thus inhibiting corporate green innovation.
Based on the Pecking Order Theory, due to the imperfection of capital market, the internal funding cost of enterprises is lower than the external funding cost, and the financing ability of enterprises will largely affect their investment behavior [54, 55]. Under the premise of relatively limited internal capital, if the enterprise invests its limited capital into financial assets, it will lead to its lack of internal capital to support green innovation investment [49]. Then, enterprises need to engage in exogenous financing to meet the capital needs of green innovation, but due to information asymmetry and the characteristics of green innovation activities such as long cycle, large investment and high risk, external investors need to bear higher financial risks when investing in enterprises’ green innovation projects. Therefore, a higher risk premium is required as compensation, that is, enterprises need to bear a higher cost of capital to obtain investment from external investors, which exacerbates the dilemma of corporate financing constraints, and serious financing constraints will limit the motivation and ability of corporate green innovation [8], thus inhibiting corporate green innovation. Based on the above analysis, we construct the influence mechanism model of financialization on corporate green innovation as shown in Fig. 1.
In summary, financialization crowds out corporate innovation inputs, reinforces managerial myopia, and exacerbates corporate financing constraint dilemma, thus inhibiting corporate green innovation. Accordingly, we propose research hypothesis 1.
Hypothesis 1. Financialization can significantly inhibit corporate green innovation.
Financialization, Environmental Regulation and Green Innovation
According to the theory of organizational open systems, organizations, as open and dynamic systems, need to adapt to the external environment and respond positively to its requirements. The green innovation behavior of enterprises is not only influenced by the internal allocation of funds, but also constrained by the external environmental regulation [7, 56, 57]. Therefore, when exploring the relationship between financialization and corporate green innovation, the constraining effect of external environmental regulation on the relationship between the two should also be examined. With the increasing emphasis on environmental protection, the Chinese government has formulated various environmental laws and regulations to constrain firms to save energy and reduce emissions, and effective environmental regulation can guide firms to carry out more green innovation activities [58, 59]. This paper refers to the studies of Peng et al. (2021) and Xie et al. (2017), and classifies environmental regulation into three categories: command-and-control, market-incentive, and public participation based on the characteristics of different types of environmental regulation [22, 60]. Among them, command-and-control environmental regulation has the compulsory binding nature of policies and regulations. Under its constraints, company managers actively or passively make changes to promote corporate green innovation, thus complying with the legitimacy requirements of external policies and regulation [22, 61]. Therefore, command-and-control environmental regulation can weaken the inhibitory effect of financialization on corporate green innovation. In addition, when firms face strict environmental laws and regulation, due to limited internal resources, they will consider reallocating existing resources to transfer capital, talent, and other resources from other investment projects to green innovation, thus conforming to the requirements of the external environmental policies and regulation. Therefore, command-and-control environmental regulation will weaken the inhibitory effect of financialization on corporate green innovation; market-incentive environmental regulation is to use the market as a medium to guide enterprises to save energy and reduce emissions, balancing profit goals with emission restrictions [62]. The use of market mechanisms can reduce the cost pressure of enterprises and make them invest more resources in green innovation, thus weakening the inhibiting effect of financialization on green innovation to a certain extent. Public participation-based environmental regulation is to monitor the environmental behavior of enterprises through the environmental awareness of the public, so as to restrain the environmental pollution behavior of enterprises [63]. In an environmental regulation situation where the public is more aware of environmental protection, companies are more inclined to fulfill their social responsibility and implement environmental protection measures to cater to the public’s environmental supervision, so as to establish a good social image and avoid negative news. Therefore, public participation-based environmental regulation can promote companies to divest resources from financial assets investment to green innovation in order to respond to public scrutiny and establish a green corporate image, thus weakening the inhibiting effect of corporate financialization on green innovation. In summary, we propose the following research hypotheses:
H2a. Command-and-control environmental regulation can weaken the inhibiting effect of financialization on corporate green innovation.
H2b. Market-incentivized environmental regulation can weaken the inhibiting effect of financialization on corporate green innovation.
H2c. Public participation-based environmental regulation can weaken the inhibiting effect of financialization on corporate green innovation.
Methodology
Sample Selection and Data Sources
This paper selects Chinese A-share listed companies from 2007 to 2020 as the research sample and deals with them as follows: First, China’s real estate industry has certain virtualization and independent characteristics, and investment real estate is usually regarded as a special category of financial assets. Therefore, when determining the range of enterprise samples, special industry samples with financial attributes such as finance, insurance and real estate are excluded; second, samples of listed companies that were specially treated (special treatment (ST) firms, particular transfer (PT) firms, etc.) are excluded; third, some samples with missing values are excluded; fourth, in order to avoid the influence of outliers on the empirical results, 1% and 99% quantile tailing is applied to all continuous variables. Finally, 6370 firm-annual observations were obtained. In this paper, the data related to green patent applications are obtained from CNRDS database. The data related to finance and governance are obtained from CSMAR database and Wind database, and the data of managers’ short-sightedness are obtained from WinGO financial text data platform.
Main Variables
Explained variable: corporate green innovation (GI). Drawing on Liu et al. (2021), this paper measures it in terms of innovation output, using the natural logarithm of the total number of green patent applications plus 1 to measure green innovation [16], and drawing on Huang et al. (2021), the natural logarithm of the number of green invention patent applications plus 1 is used for robustness test [39].
Explanatory variable: the financialization of the real enterprise (Financial). The measure of financialization in the existing literature is generally the proportion of financial assets to total assets of the enterprise. Drawing on the study of Yang & Li (2023), financial assets are defined into four categories: trading financial assets, investment real estate, new financial assets such as entrusted loans, and long-term financial equity investments, and the proportion of the above four categories of financial assets to total assets is used to measure financialization [7]. In addition, this paper further adopts the ratio of the sum of seven items, namely, trading financial assets, net investment properties, net loans and advances granted, net available-for-sale financial assets, derivative financial assets, net held-to-maturity investments, and net long-term financial equity investments, to total assets as a replacement indicator for robustness test.
Moderating Variables: Environmental regulations. Drawing on Xie et al. (2017), the following indicators are used to measure command-and-control, market-incentive, and public participation-based environmental regulations, respectively [22]. (1) Command-and-control environmental regulation (CER): the proportion of industrial “three wastes” (industrial waste water, gas and sludge) emissions to the industrial GDP of each province in China is used as a measure. The larger its value is, the more serious the environmental pollution situation. The government will be under greater pressure to protect the environment and formulate stronger environmental policies, which will lead to stricter environmental regulation on enterprises. (2) Market-incentivized environmental regulation (MER): measured by the share of industrial pollution control investment in the GDP of each Chinese province; (3) Public participation-based environmental regulation (PER): we use the annual average value of Baidu environmental pollution search index in each region of China to measure public environmental concern. The main reasons for using this indicator are: First, Baidu is the largest Chinese search engine with wide coverage and high data availability; Second, the public is more and more inclined to pay attention to environment-related issues by web search than by traditional petition.
Table 1.
Variable definitions.
Control Variables: Corporate green innovation is also affected by many external factors, and we control for the effects of firm size (Size), debt ratio (Debt), firm performance (ROE), growth (Growth), firm age (Age), institutional investor ownership (Insti), government subsidy for innovation (Subsiby), operating cash flow adequacy (OCF), capital density (CD), equity concentration (CR1), board size (Board), board independence (Indep), and duality (Duality) based on existing studies [38,39,64]. In addition, the effects of year and industry dummy variables are controlled. The specific variables are defined and measured in Table 1.
Regression Model Design
Fixed effects models are employed to test the research hypotheses proposed above after the F-test and Hausman test. To test these hypotheses, the following regression models are constructed.
First, to test the effect of financialization on corporate green innovation, regression model (1) is constructed as follows:
Where i represents the listed company, t represents the year, GIi,t denotes the level of green innovation, Financiali,t indicates the degree of financialization, ΣControlsi,t refers to the set of control variables, and Year is the time fixed effect, Industry is the industry fixed effect, εi,t represents the standard residual term.
Second, to test the effects of financialization, environmental regulation and their interaction terms on green innovation, i.e., to test the moderating effect of environmental regulation, Model (2)-Model (4) are constructed as follows:
Where i represents the listed company, t represents the year, GIi,t denotes the level of green innovation, Financiali,t indicates the degree of financialization, CERi,t, MERi,t, and PERi,t are moderating variables, ΣControlsi,t refers to the set of control variables, and Year is the time fixed effect, Industry is the industry fixed effect, εi,t represents the standard residual term.
Empirical Results
Descriptive Statistics
Table 2 shows the descriptive statistics of the sample, where Panel A shows the results of descriptive statistics for the full sample. The results show that the average value of GI is 0.7525 and the median value is 0, which indicates that the overall number of green patent applications of Chinese A-share listed companies is low and half of the companies do not apply for green patents; the standard deviation is 1.0703 and the difference between the minimum and maximum values is large, which indicates that the green patent applications vary greatly among the sample companies; The average value of financialization is 0.0387, indicating that the average ratio of financial assets to total assets of the sample companies is 3.87%; In addition, the differences between the minimum and maximum values of the three environmental regulations are large, indicating that there are large differences in the environmental regulations in the regions where different sample companies are located; The average values of all types of environmental regulations are slightly higher than the median, indicating that more than half of the sample companies are subject to environmental regulations slightly below the average level. As for the control variables, there are different degrees of differences in indicators such as company size, debt ratio, and company performance.
Panel B shows the results of the mean difference t-test for the number of green patent applications after grouping according to different levels of financialization and environmental regulations. The results show that the number of green patent applications is lower for companies with financialization above or equal to the mean compared to those with financialization below the mean, and there is a significant difference between the two groups. In addition, the green patent applications were significantly different in different types of environmental regulation subgroups.
Regression Analysis
Table 3 shows the regression results for the impact of financialization on corporate green innovation and the moderating role of environmental regulation. Among them, columns (1)-(2) show the regression results of the impact of financialization on green innovation without considering the control variables and after introducing the control variables, respectively. The results in column (2) indicate that after considering the control variables, the estimated coefficient of financialization is -0.7702 and is significant at the 1% level. Therefore, financialization moves inversely with corporate green innovation, i.e., Panel A. Full sample descriptive statistics financialization inhibits corporate green innovation, and hypothesis H1 is supported. Columns (3)-(5) show the test results of the moderating effects of the three types of environmental regulations, respectively. The coefficients of the interaction terms of the three types of environmental regulations and financialization on green innovation are 0.0521, 253.0058 and 0.0025, but only the coefficient of the inter-action term of CER and financialization is significant at the 10% level. This indicates that command-and-control environmental regulation can weaken the inhibitory effect of financialization on green innovation to a certain extent. Therefore, hypothesis H2a receives empirical support. However, market-incentive and public participation-based environmental regulations do not significantly inhibit the negative relationship between financialization and corporate green innovation. Therefore, hypotheses H2b and H2c are rejected.
Table 2.
Descriptive statistics.
Robustness Tests
Replacing Variables and Models
To ensure the robustness of the research results, we replace the main variables to re-test the research hypotheses. In Table 4, Column (1) shows the regression results using the natural logarithm of adding 1 to the number of green invention patent applications as the green innovation replacement variable; Column (2) shows the regression results using the sum of seven items as the composition of financial assets, i.e., trading financial assets, net investment properties, net loans and advances granted, net available-for-sale financial assets, derivative financial assets, net held-to-maturity investments, and net long-term equity investments, and then using the ratio of financial assets to total assets as the replacement variable for financialization; Columns (3)-(5) are the regression results after adopting the emissions of three types of pollutants, wastewater, sulfur dioxide and smog per unit of industrial GDP as a replacement variable for CER, the share of regional investment in environmental pollution treatment in GDP as a replacement variable for MER, and the regional Baidu haze search index as a replacement variable for PER, respectively. The regression results are presented in Table 4, which indicate that all the research findings remain robust after replacing the main variables. In addition, since there is a certain percentage of sample firms that are not allocated to financial assets, i.e., their financialization is zero, we re-test the impact of financialization on corporate green innovation using the Tobit model, and the regression results in column (6) of Table 4 show that the basic findings remain unchanged.
Table 3.
Regression results.
Endogeneity Analysis
Considering that firms with a high level of green innovation may require more capital investment and thus less investment in financial assets. To exclude the potential endogeneity problem caused by possible reverse causality and take the possible long-term impact of financialization on corporate green innovation into account, we lag all continuous explanatory and control variables by one, two and three periods, respectively. The regression results in columns (1)-(3) of Table 5 show that the previous findings are basically unchanged after considering the reverse causality issue, and the inhibitory effect of corporate financialization on green innovation is found to last for two periods. In addition, considering the possible problem of omitted variables in the model construction process, we add control variables such as CEO gender, CEO education and CEO financial background to reflect the influence of CEO personal traits on green innovation. The empirical results in column (4) of Table 5 indicate that the basic research findings remain robust.
Table 4.
Changing Metrics and Models.
Excluding the Interference Samples
Excluding Green Enterprises
Since green enterprises’ business scope is mostly green products, they are more active in green innovation than non-green enterprises, which may affect the robustness of the results. Therefore, the regression test is conducted after excluding the sample of green enterprises. The screening criteria for the sample of green enterprises is that an enterprise is recognized as a green enterprise if it is screened by the CSMAR database’s “Business Scope” indicator for keywords such as “environmental protection”, “ecology”, “green”, “new energy development”, or other entries with similar meanings. The regression results after excluding the green enterprise samples are shown in column (5) of Table 5. The regression coefficient of financialization is still significantly negative, which indicates that the basic regression results of the previous study remain unchanged.
Excluding the Sample After the Adjustment of Financial Assets Classification Way
Considering that the Accounting Standards for Chinese Enterprises No.22 adjusted the classification of financial assets and started to be implemented in January 2019, the regression test is re-run by excluding the samples in 2019 and 2020 in order to avoid the impact of the difference in the classification of financial assets on the empirical results. The regression results are shown in column (6) of Table 5, and the coefficient of financialization is still significantly negative. The results indicate that the benchmark results are robust.
Excluding the Years of Major Financial Event Shocks
Considering the impact of shocks from two major financial events, the global financial crisis and the China stock market crash, on the investments of the sample firms, we exclude the samples of the global financial crisis of 2008-2010 and the two years afterward, as well as the samples of the Chinese stock market crash of 2015-2017 and the two years afterward. The regression results are shown in column (7) of Table 5, where the coefficient of financialization remains significantly negative, and the results verify the reliability of the benchmark results.
Table 5.
Robustness test results.
Placebo Test
Considering that one potential interference to the findings is the effect of certain random factors that lead to the statistical significance of the impact of financialization on green innovation. In order to improve the robustness, we adopt a placebo test by randomly generating experimental groups so as to exclude the interference of other random factors. The results show that the estimated coefficients are mainly distributed near 0 value. According to the regression results in column (2) of Table 3, the true regression coefficient is -0.7702, so the main research findings remain robust after excluding the influence of other unobserved factors.
Transmission Mechanism Test of Financialization Affecting Corporate Green Innovation
In the theoretical basis and hypothesis section, we conducted theoretical analysis and empirical tests on the impact of financialization on green innovation, and found that financialization significantly inhibits green innovation, but the three transmission paths proposed in the theoretical analysis have not been tested. Based on the previous analysis, financialization will squeeze out innovation inputs, strengthen managers’ myopia, and exacerbate the predicament of corporate financing constraints, thus inhibiting corporate green innovation. Therefore, we examine the mediating effects of innovation inputs, managerial myopia and financing constraints in the process of financialization affecting corporate green innovation, respectively.
Financialization, Innovation Inputs and Green Innovation
To reveal whether financialization inhibits corporate green innovation by crowding out innovation inputs, the natural logarithm of the amount of R&D inputs (RD) is used as a measure of innovation inputs and tested using a mediating effect model. The results are presented in columns (1)-(2) of Table 6. Column (1) examines the effect of the explanatory variable (Financial) on the mediating variable (RD), and the estimated coefficient of Financial is -2.1749 and is significant at the 1% level, which indicates that financialization crowds out innovation inputs; Column (2) includes both the explanatory variable (Financial) and the mediating variable (RD), and the estimated coefficients are significant at the 1% level. Through further Sobel test, the Z-statistic is -8.602 and significant at the 1% level, and the mediating effect accounts for about 49.1%, which indicates that innovation input plays a partial mediating role between corporate financialization and green innovation, i.e., corporate financialization affects green innovation by influencing innovation input. The test results support the transmission mechanism of “financialization-innovation input-green innovation”.
Financialization, Managerial Myopia and Green Innovation
To test whether financialization inhibits corporate green innovation by reinforcing managerial myopia, we measure managerial myopia (Myopia) by using the ratio of the total word frequency of myopic terms to the total word frequency of the Management Discussion and Analysis (MD&A) section of listed companies’ annual reports [65]. We then apply a mediating effect model to test the results, which are presented in columns (3)-(4) of Table 6. Column (3) examines the effect of the explanatory variable (Financial) on the mediating variable (Myopia) with an estimated coefficient of 0.0228 for Financial, but it is not significant; Column (4) includes both the explanatory variable (Financial) and the mediating variable (Myopia), and the estimated coefficients of both are significant at the 1% level. Since the estimated coefficient of the effect of the explanatory variable (Financial) on the mediating variable (Myopia) is not significant, a Sobel test is required in order to test whether the mediating effect of managerial myopia (Myopia) holds. The test results show that the Z-statistic is not significant, which indicates that managerial myopia does not play a significant mediating role between corporate financialization and green innovation, i.e., managerial myopia is not effective transmission mechanism of financialization affecting corporate green innovation.
Financialization, Financing Constraints, and Green Innovation
To elucidate whether financialization inhibits corporate green innovation by exacerbating financing constraints, the absolute value of the SA index (SA) is used as a measure of corporate financing constraints [66]. We conduct the test using a mediating effect model, and the results are presented in columns (5)-(6) of Table 6. In column (5), the estimated coefficient of the explanatory variable (Financial) is significantly positive at the 1% level, indicating that financialization exacerbates corporate financing constraints; In column (6), the estimated coefficients of both the explanatory variable (Financial) and the mediating variable (SA) are significant at the 1% level. Trough further Sobel test, the Z-statistic is -3.706 and significant at the 1% level, and the mediating effect is about 8.1%. This indicates that financing constraints play a partial mediating role between financialization and green innovation, i.e., financialization affects green innovation by influencing financing constraints. The test results support the transmission mechanism of “financialization-financing constraints-green innovation”.
Table 6.
Transmission mechanism test results.
Further Analysis
Financialization and Different Types of Green Innovation
Does Financialization Inhibit Substantive or Strategic Green Innovation?
Corporate green innovation can be classified into substantive green innovation and strategic green innovation based on the purpose of innovation. According to the distinction between substantive and strategic innovation that has been proposed by scholars, the green innovation behavior that aims to promote the green technological progress of enterprises is substantive green innovation. While the pursuit of the quantity and speed of green innovation to meet the requirements of government policies is called strategic green innovation. In practice, the green innovation behavior of enterprises is sometimes manifested as a strategic behavior, aiming to obtain certain benefits or cater to the government’s green innovation policy [67]. To reveal whether corporate financialization has a differential impact on substantive and strategic green innovation, we conduct a further test. Drawing on Du et al. (2022), the number of green inventive patents (GreenIno) is used to measure substantive green innovation and the number of green utility patents (GreenPra) to measure strategic green innovation [68], and regression analyses are conducted separately. The regression results are presented in columns (1)-(2) of Table 7. Among them, column (1) of Table 7 examines the effect of financialization (Financial) on firms’ substantive green innovation (GreenIno), and the estimated coefficient of Financial is -0.5942 and is significant at the 1% level, indicating that the more financialized a firm is, the lower the number of its green inventive patents, i.e., financialization inhibits firms’ substantive green innovation; The estimated coefficient of the effect of financialization on strategic green innovation (GreenPra) in column (2) is -0.5175 and is significant at the 1% level, indicating that the higher the level of financialization, the lower the number of green utility patents, i.e., financialization inhibits strategic green innovation of enterprises. A further test of the difference in regression coefficients between groups shows that the p-value is 0.5257, which is not significant at the 10% level, indicating that financialization has an inhibiting effect on both substantive and strategic green innovation, and there is no statistically significant difference in this effect. The results indicate that whether it is substantive green innovation that can promote green technological progress and bring long-term benefits to enterprises or strategic green innovation to meet policy requirements, when enterprises allocate more financial assets and cannot provide sufficient resources for green innovation activities, enterprises will not prioritize the long-term benefits of substantive green innovation and give limited resources to substantive green innovation. Instead, they will reduce both types of green innovation activities without any difference.
Does Financialization Inhibit Independent or Joint Green Innovation?
Independent green innovation and joint green innovation are two common ways of corporate green innovation. Does financialization affect the way companies engage in green innovation? What are the differential effects of financialization on independent and joint green innovation? To reveal the impact of financialization on corporate independent green innovation and joint green innovation, we conduct a further test. The number of green patent applications for independent inventions (GreenInd) and the number of green patent applications for joint inventions (GreenJoint) are used to measure the independent green innovation and joint green innovation of enterprises, and regression analyses are conducted separately. The regression results are shown in columns (3)- (4) of Table 7. Among them, column (3) of Table 7 examines the effect of financialization (Financial) on corporate independent green innovation (GreenInd), and the estimated coefficient of Financial is -22.7804 and is significant at the 1% level, indicating that financialization significantly inhibits firm-independent green innovation; The estimated coefficient of the effect of Financialization (Financial) on firms’ joint green innovation (GreenJoint) in column (4) is -7.4786 and is significant at 1% level, which indicates that financialization significantly inhibits firms’ joint green innovation.
Further test results of the difference in regression coefficients between groups show that the p-value is 0.0057 and significant at the 1% statistical level, which indicates that the inhibiting effect of financialization on corporate independent green innovation is significantly higher than its inhibitory effect on corporate joint green innovation. When firms allocate more financial assets and cannot provide sufficient resources for green innovation activities, they will preferentially reduce independent inventions of green innovation. While joint green innovation, which involves cooperation with external firms, has certain strategic significance, makes firms likely to be more prudent in cutting resources and reducing joint innovation.
Table 7.
Financialization and different types of green innovation.
Heterogeneity Analysis of Industry Pollution Intensity
Under the current overall strategic goal of national green development, both heavily polluting industries and non-heavily polluting industries face a certain degree of pressure to reduce emissions. When enterprises invest in financial assets and reallocate internal resources, the difference in industry pollution intensity will affect the resource supply for enterprise green innovation activities, which has a differential impact on enterprise green innovation. Therefore, to reveal the heterogeneous effects of financialization on green innovation by firms in different industries with different pollution intensity, we conduct a further test. The 16 industries, such as mining, thermal power, metallurgy, chemical, and petroleum, etc. delineated in the 2010 Environmental Information Disclosure Guidelines for Listed Companies by the Chinese Ministry of Environmental Protection are defined as heavily polluting industries, and the rest of the industries are non-heavily polluting industries [68]. On this basis, grouped regression is conducted by dividing the sample into two sub-sample groups of non-heavily polluting firms and heavily polluting firms, and the regression results are shown in columns (1)-(2) of Table 8. Column (1) of Table 8 examines the effect of financialization of enterprises in non-heavy polluting industries on green innovation, and the estimated coefficient of financialization (Financial) is -0.8017 and significant at the 1% level, indicating that financialization of enterprises in non-heavy polluting industries significantly inhibits green innovation; Column (2) examines the effect of financialization of enterprises in heavy polluting industries on green innovation, and the estimated coefficient of financialization (Financial) is -0.5444 but not significant, which indicates that financialization of firms in heavy polluting industries does not significantly inhibit their green innovation. The results of this test support the previous analysis, indicating that for the heavily polluting enterprises, due to the greater environmental and cost pressures, there is a stronger incentive to improve the efficiency of corporate green technology and resource utilization through green innovation and reduce pollution emissions. Even if enterprises allocate more financial assets, they may secure the resource supply for green innovation activities through reallocation of overall resources or striving for more external resources. Therefore, the financialization of heavily polluting enterprises does not significantly inhibit corporate green innovation. In contrast, non-heavily polluting industries have relatively less pressure to reduce emissions and are more likely to engage in green innovation based on profit-seeking motives or establishing an environmentally friendly image [46]. When firms want to realize their capital profit-seeking motives through financialization, they will naturally reduce the supply of resources for green innovation activities and allocate resources to financial investment activities instead, thus more significantly inhibiting corporate green innovation.
Table 8.
Heterogeneity test results of pollution intensity and regulatory pressure.
Heterogeneity Analysis of Regional Regulatory Pressure
Differences in environmental regulatory pressures exist in different regions. When the region where the enterprise is located is a priority city for environmental protection, the local government will strengthen the environmental protection regulation of local firms by formulating a series of regional environmental policies. When firms invest in financial assets, they need to adjust their internal resource allocation, and the adjustment of resources to green innovation activities will be differentiated by the impact of differentiated local environmental regulatory pressure. Therefore, to reveal the heterogeneous effects of different regional regulatory pressures on the impact of firms’ financial asset allocation on green innovation, we conduct further tests. Based on the 113 priority cities for environmental protection identified in “The National Eleventh Five-Year Plan for Environmental Protection” issued by the State Council of China in 2007, firms are categorized according to whether they are priority cities for environmental protection. If an enterprise is located in a priority city for environmental protection, it faces more regulatory pressure; Otherwise, it faces less pressure [68]. On this basis, grouped regressions are conducted by dividing the sample population into two sub-sample groups of firms with low regional regulatory pressure and firms with high regional regulatory pressure, and the regression results are shown in columns (3)-(4) of Table 8. Column (3) of Table 8 examines the impact of financialization on green innovation of firms with low regional regulatory pressure, and the estimated coefficient of financialization (Financial) is -0.2522, but it is not significant. The empirical results suggest that financialization of enterprises with low regional regulatory pressure does not significantly inhibit their green innovation; Column (4) of Table 8 examines the effect of financialization on green innovation for enterprises with high regional regulatory pressure, and the estimated coefficient of financialization (Financial) is -0.8593 and significant at the 1% level. The empirical results indicate that the financialization of enterprises with high regional regulatory pressure significantly inhibits green innovation. The above results indicate that in regions with low regulatory pressure, enterprises are relatively less willing and motivated to green innovation, and even if they do not invest in financial assets, they may not put resources into green innovation activities. This means that enterprises originally did not use resources for green innovation, and resources for financial investment may be transferred from other investment projects, so their financialization does not significantly inhibit green innovation. In regions with high regulatory pressure, enterprises have stronger willingness and motivation for green innovation driven by the external environment. However, when enterprises invest in financial assets, under the premise that the total amount of internal resources is limited, they will still satisfy the investment demand of financial assets by reducing investment in green innovation, thus significantly inhibiting corporate green innovation.
Conclusions
Combined with the current macroeconomic green development background, this study analyzes the mechanism and transmission paths of financial asset investment decisions on corporate green innovation based on the perspective of corporate financial resources. Moreover, we further investigate the differential effects of heterogeneous environmental regulation contexts on the relationship between financialization and green innovation. The following main conclusions are obtained: (1) Financialization significantly inhibits corporate green innovation. (2) Command-and-control environmental regulation can weaken the inhibiting effect of financialization on corporate green innovation. (3) In terms of transmission paths, financialization inhibits green innovation mainly by affecting corporate innovation inputs and financing constraints. (4) The extended analysis shows that there is no significant difference between the inhibiting effect of financialization on strategic green innovation and substantive green innovation, but the inhibiting effect on independent green innovation is significantly higher than that on joint green innovation. (5) The inhibiting effect of financialization on green innovation is more significant for enterprises in non-heavily polluting industries and enterprises in regions with higher regional regulatory pressure.
Our research provides micro-level empirical evidence for managing the negative effects of financialization and guiding the practice of green development of enterprises, and proposes the following policy implications: First, enterprises should be alert to the crowding-out effect of financialization on green innovation, improve the internal investment decision-making mechanism, so as to avoid enterprises from using their limited resources for financial speculation out of short-term profit-seeking motives and rejecting the green innovation projects that can bring long-term economic and environmental benefits to enterprises. Second, in view of the inhibiting effect of financialization on corporate green innovation, the relevant government departments should target to increase the supervision of the financialization of real enterprises, and guide real enterprises to focus their investment on their main business and long-term development, so as to effectively promote the implementation of policies on financial services for the real economy, and to promote the green and low-carbon development of enterprises. Third, give full play to the external constraining effect of command-and-control environmental regulations such as environmental protection policies and regulations, while continuing to improve the inhibiting effect of market mechanisms and public supervision on the financialization of enterprises crowding out green innovation. By integrating the constraining effects of external formal and informal mechanisms, we can avoid the over-financialization of enterprises crowding out green innovation resources and promote green innovation. Fourth, government departments should build a long-term mechanism that helps enterprises carry out green innovation and give them long-term financial support, which will help enterprises have sufficient cash flow to guarantee green innovation investment, alleviate financing constraints, and promote green innovation. Fifth, relevant government departments should formulate differentiated policies to support enterprises’ green innovation in the light of the actual situation of different industries and regions, create a policy environment conducive to enterprises’ green innovation, and encourage enterprises to carry out green innovation activities.

